


Why Pennant Group (PNTG) Is Back In The Spotlight
Pennant Group (PNTG) is back in focus after fresh analysis highlighted its modest revenue base, thin free cash flow, and relatively high net-debt-to-EBITDA, raising questions about how much flexibility the balance sheet really offers.
Pennant Group’s recent review comes after a strong run, with the share price up 52.96% year to date and a 1-year total shareholder return of 68.53%. The 3-year total shareholder return of 293.07% signals momentum that investors are now weighing against balance sheet constraints.
Spot under-the-radar healthcare operators with similar balance sheet pressures by scanning our hand picked list of solid balance sheet and fundamentals (24 results).Pennant Group now carries a richer share price and a balance sheet that is working harder. Does that trade off still leave enough upside to justify today’s valuation tags?
Most Popular Narrative: 9% Undervalued
Pennant Group’s most followed valuation story places fair value at $46.67 against a last close of $42.57, so the narrative implies some remaining upside if the assumptions hold together.
The accelerating aging of the U.S. population, with more than 4 million people turning 65 each year and living longer, continues to expand the pool of seniors who prefer home health, hospice, and senior living services that Pennant Group provides. This can underpin long term revenue growth.
The ongoing shift by payers and families toward lower cost, home based care settings relative to institutional care aligns with Pennant Group’s focus on home health and hospice agencies. This can support volume growth and help protect segment margins as demand concentrates in these service lines.
See why 6 investors see Pennant Group as 9% undervalued.
Result: Fair Value of $46.67 (UNDERVALUED)
Still, Pennant Group’s reliance on Medicare-driven home health and hospice payments, along with the national moratorium on new sites, could quickly challenge that 9% undervalued story.
Find out about the key risks to this Pennant Group narrative.
Another View: Pennant Group Through Its Earnings Multiple
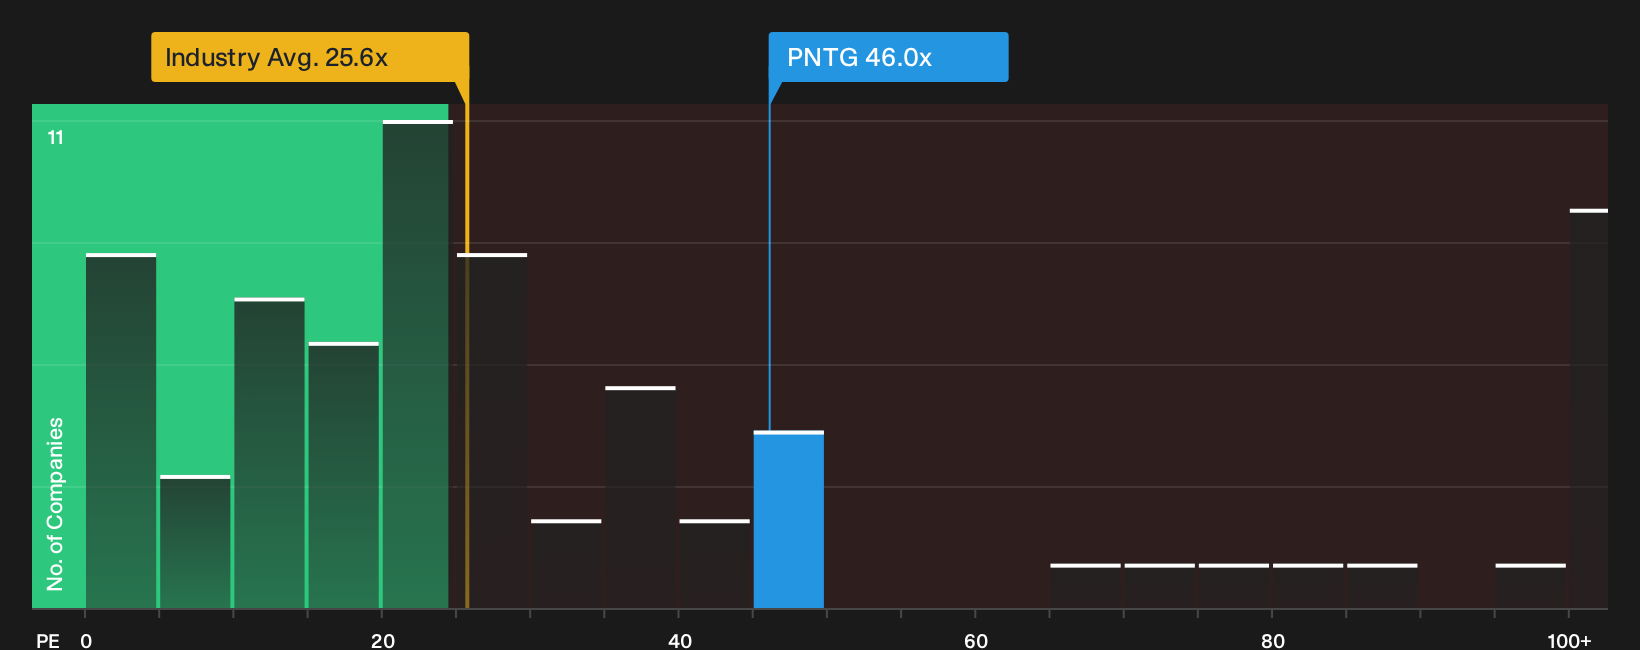
Pennant Group might look cheap against one fair value line, yet its current P/E of 46x tells a different story. The ratio is above the US Healthcare sector at 25.7x and above its own fair ratio estimate of 29.2x, which points to less margin for error if growth expectations soften.
For investors who lean on earnings multiples rather than cash flow models, this gap between a 46x P/E, a 29.2x fair ratio, and richer pricing than the broader Healthcare group and peer set raises a simple question. Is this a premium that feels comfortable to pay for Pennant Group right now, or is it time to demand more evidence before accepting it as justified, especially with a balance sheet already pulling its weight, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Pennant Group’s valuation and balance sheet can be hard to weigh. Pull up the data, pressure test the assumptions, and anchor your own thesis around the 3 key rewards and 1 important warning sign.
Looking for more Pennant Group style ideas?
If Pennant Group has sharpened your focus on valuation and resilience, do not stop here. Use targeted screeners to surface other opportunities before the crowd.
- Target potential value opportunities early by reviewing the 29 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them yet.
- Zero in on balance sheet strength by scanning the list of solid balance sheet and fundamentals (24 results) so you are not caught off guard by hidden financial strain.
- Unearth fresh prospects beyond the usual tickers by working through the 21 high quality undiscovered gems that pair solid financial profiles with lower investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com