


What Exelixis Shareholders Got Right
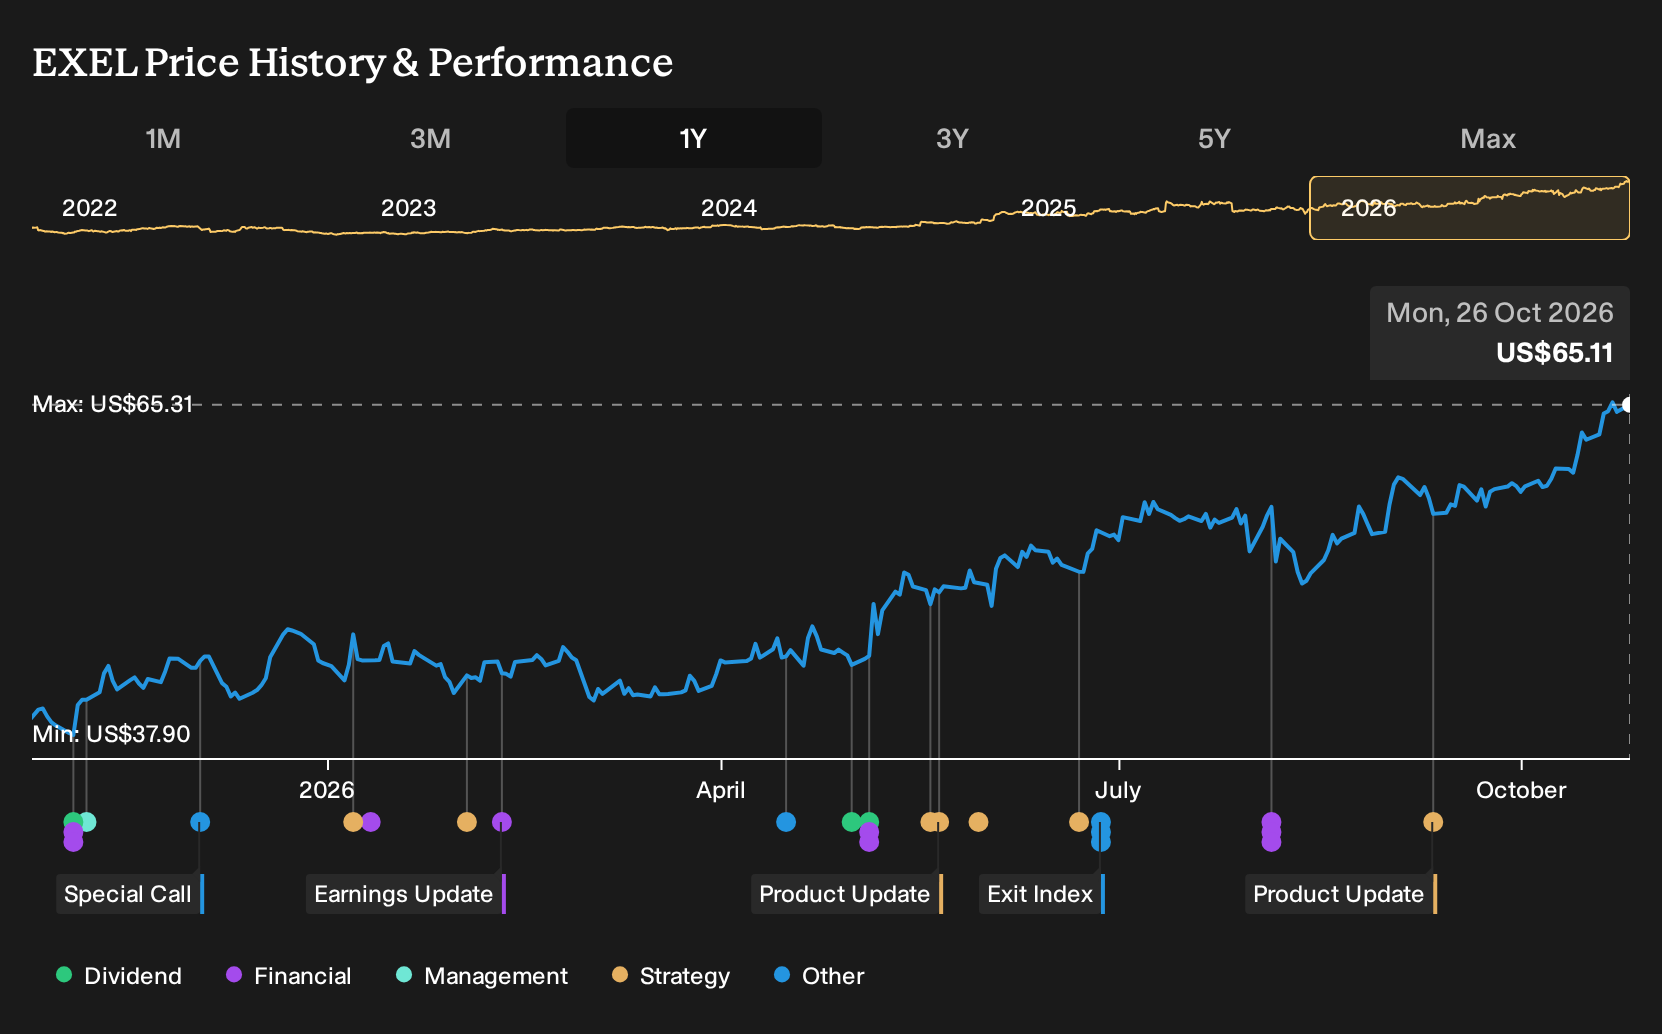
If you had looked at Exelixis in late October 2025, you would have seen a heated split between bulls pointing to expanding CABOMETYX use and bears focused on 340B pressure and regulatory risk. For Exelixis shareholders, the return over the past year was 62.8%, including dividends. If you were weighing a buy decision then, would the concentration in one oncology franchise or the early promise of zanzalintinib have mattered more to you?
Exelixis has already moved. Pinpoint other ways to investigate the theme among 34 healthcare AI stocks.
The Two Exelixis Stories Investors Had To Choose Between
The shares cost US$38.74 at the start of the period, and Exelixis sat between two very different but plausible stories about its future.
On the bullish side, one narrative saw a fair value of US$44.06, a price implied by assumptions such as revenue rising 11.7% a year with profit margins reaching 36.7% within three years as global oncology access widened.
The bearish view anchored on a fair value of US$36, built around concerns that growing 340B exposure and tighter drug pricing would compress margins and keep earnings growth closer to 4.5% a year.
What The Evidence Around Exelixis Actually Tested
Exelixis reported Q2 2026 revenue of US$628.69 million and net income of US$212.05 million, with net margin at 33.7% compared with 32.5% a year earlier. That tilt in profitability supported optimistic expectations for rising earnings power, while continued dependence on the cabozantinib franchise and FDA extensions around zanzalintinib sustained a more cautious perspective. Overall, the evidence pointed in both directions.
The lesson is clear. When a thesis hinges on margin expansion and franchise concentration, track the reported net margin and revenue mix by product in each filing to see which narrative is gaining ground.
What Exelixis Buyers Are Paying For After A 63% Climb
Today Exelixis changes hands at US$65.11, while the selected Narrative’s Fair Value sits below the current price. That view rests on cabozantinib still funding the story as management works to turn zanzalintinib and other programs into a broader oncology platform.
The key question is what must keep going right for that price to add up. This Narrative frames that requirement as disciplined spending and successful new launches offsetting a future cabozantinib patent cliff.
"The main execution priority is turning CABOMETYX’s current multi billion dollar run rate and the planned zanzalintinib launches in GI and GU oncology into durable, multi franchise cash generation before the cabozantinib patent cliff early in the next decade."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Go Straight To The Source
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 22% below our estimate - focuses on filling new manufacturing lines with higher value AI driven optics contracts.
- Company 2 - 30% below our estimate - supplies chips and software that keep digital infrastructure running across evolving AI needs.
- Company 3 - 35% below our estimate - expands high horsepower engine capacity to support demanding data center power requirements.
Three companies from the same screener. Open the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com