


Western Midstream Partners (WES) Just Gave Investors Something To Think About
Western Midstream Partners (WES) just reaffirmed its income profile, with the general partner’s board declaring a third quarter 2026 cash distribution of $0.93 per unit, matching the prior period’s payout.
At a unit price of $45.17, Western Midstream Partners has seen its share price gain 13.72% year to date, while the 1-year total shareholder return of 27.56% and 5-year total shareholder return of 217.12% point to momentum that income-focused investors are watching closely around this reaffirmed payout.
Scan how Western Midstream Partners compares with other income plays by sifting through 5 dividend fortresses, while this reaffirmed $0.93 payout keeps yield firmly in focus.
For Western Midstream Partners at $45.17, that reaffirmed $0.93 payout and hefty long term return record put a higher entry bar in front of new buyers. Does the current valuation justify paying up now instead of waiting?
Most Popular Narrative: 9% Undervalued
On the most followed narrative, Western Midstream Partners screens as undervalued, with that framework putting fair value at $49.69 against the recent $45.17 close. This puts the reaffirmed distribution into a different light for anyone focused on both income and entry price.
Investment in large Delaware Basin projects such as the Pathfinder produced water pipeline and the North Loving II gas processing train, which are moving toward expected 2027 in service dates, is set to add fee based capacity that could lift Western Midstream Partners’ revenue and adjusted EBITDA as volumes ramp through those assets.
See why 41 investors see Western Midstream Partners as 9% undervalued.
Result: Fair Value of $49.69 (UNDERVALUED)
Still, this income story depends on big spending paying off, with Pathfinder, North Loving II and Brazos integration all exposed if producer activity or contracts disappoint.
Find out about the key risks to this Western Midstream Partners narrative.
Another View: What The P/E Says About Western Midstream Partners
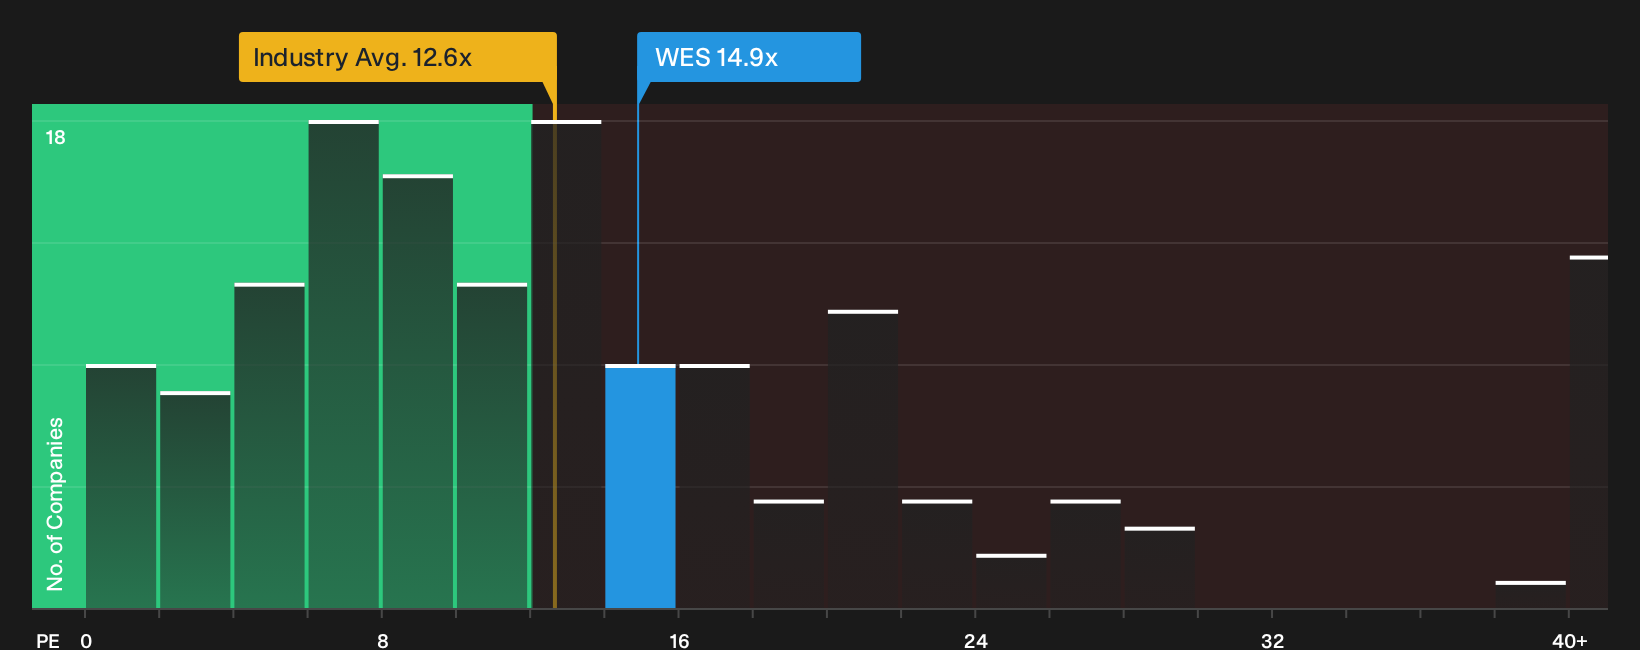
The story looks different when you shift from that $49.69 fair value to simple P/E math. Western Midstream Partners trades around 14.9x earnings, above the US Oil and Gas industry at 12.5x, yet below a peer average of 20.9x and a fair ratio estimate of 19.6x.
That mix means investors are already paying more than the broader sector, while the fair ratio suggests the market could still move closer to a higher multiple over time. Is that gap a cushion for valuation risk, or a sign expectations are already running hot for WES at $45.17?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Western Midstream Partners can be useful if you move quickly and pressure test the thesis yourself across both income and valuation angles. To weigh those trade offs and see how risks compare with potential upsides, start with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Western Midstream Partners?
You do not need to stop at Western Midstream Partners. Broaden your watchlist with fresh ideas that line up with your income goals and risk comfort.
Use the Simply Wall Street Screener to quickly filter opportunities that fit your style and avoid leaving potential ideas on the table.
- Target stability first by reviewing companies that show strong balance sheets and solid fundamentals through the list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a discount by scanning the 21 high quality undiscovered gems and see which businesses the market might be overlooking.
- Prioritize resilience by checking the 30 resilient stocks with low risk scores so you are not the last to spot companies with steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com