


Is Manulife Financial (TSX:MFC) Fully Valued On Its New Cards And AI Push?
Manulife Financial (TSX:MFC) has been busy. Over October, the group rolled out new Manulife Bank credit cards focused on health and wellness rewards and introduced several AI tools aimed at underwriting and advisor support.
These launches land at a time when Manulife Financial’s momentum has been building, with the share price at CA$62.59 and a year to date share price return of 25.68% alongside a 1 year total shareholder return of 40.98%. The 5 year total shareholder return of 224.84% points to a long stretch of strong compounding, despite a slightly weaker 90 day share price performance that suggests some of that enthusiasm has cooled in the very short term.
Spot 39 profitable AI stocks that aren't just burning cash that, like Manulife Financial, are using AI to reshape financial services while already generating real profits rather than just burning cash.After that kind of run and with Manulife Financial still trading below both an intrinsic estimate and analyst targets, is the market correctly pricing in risk, or leaving too much on the table as the valuation story unfolds next?
Most Popular Narrative: 4% Undervalued
On the most followed view, Manulife Financial screens slightly undervalued, with a narrative fair value of CA$65.40 against the last close of CA$62.59. That gap rests heavily on how Asia and fee income shape the next few years.
The earnings mix is continuing to shift toward fee based and protection businesses, with Global WAM already reporting a 31.2% core EBITDA margin and legacy LTC and VA together contributing comfortably less than 10% of earnings, which can support more capital-light earnings and steadier net income.
See why 141 investors see Manulife Financial as 4% undervalued.
Result: Fair Value of CA$65.40 (UNDERVALUED)
Still, pressure on alternative long duration assets and weakness in the Canada group long term disability segment could easily challenge the current Manulife Financial bull case.
Find out about the key risks to this Manulife Financial narrative.
Another View: What Manulife Financial’s P/E Is Really Saying
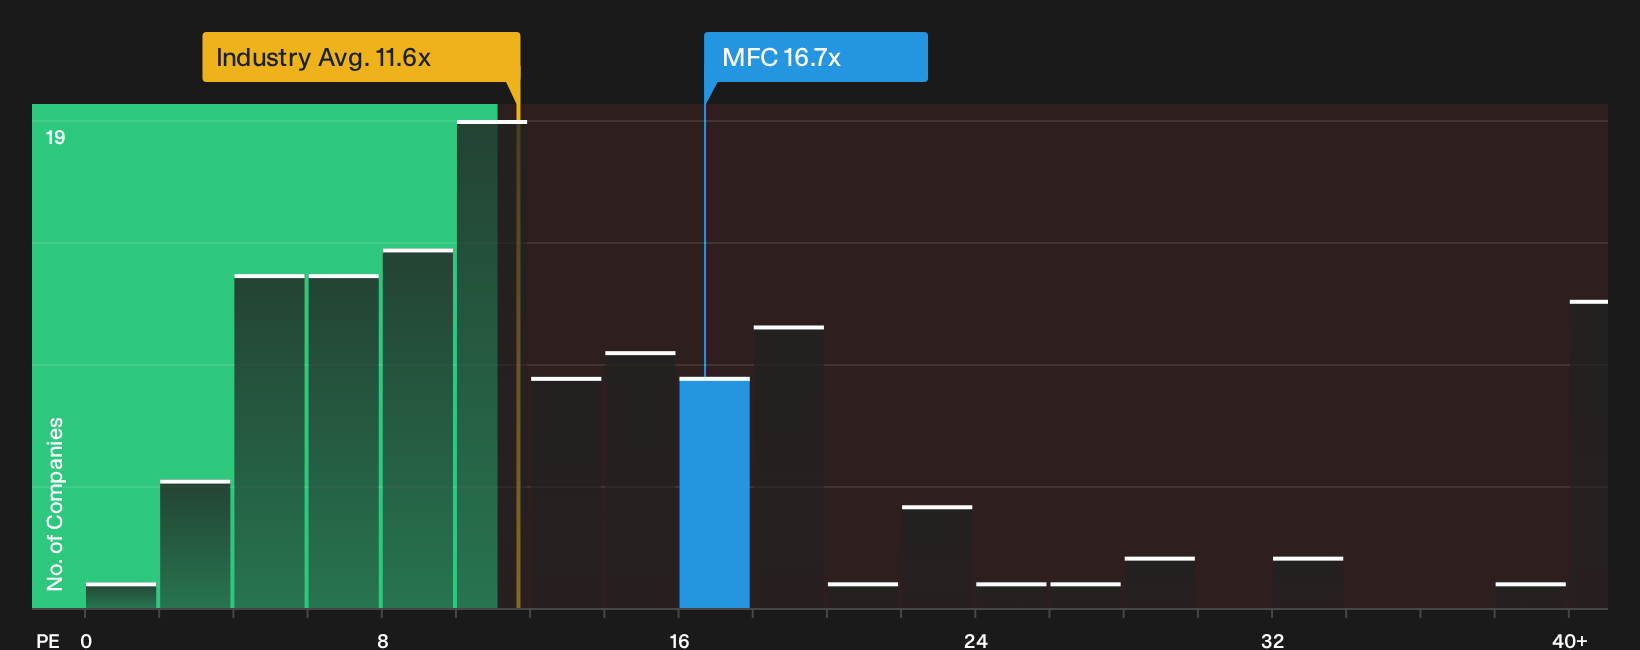
Manulife Financial might look appealing on a cash flow lens, yet its P/E of 16.7x tells a different story. That multiple is richer than the broader North American insurance group at 11.6x and even above its own fair ratio of 15.1x. This suggests there may be less room for error if expectations slip.
For investors weighing that trade off, it helps to see what the numbers imply about valuation risk and upside in detail, rather than just the headline discount to cash flows. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Manulife Financial is clearly optimistic, yet the real test is how the data lines up with your own risk tolerance and goals. If you want to see what is driving that optimism in detail, take a closer look at the 4 key rewards.
Looking For More Ideas Beyond Manulife Financial?
If Manulife Financial has sharpened your appetite for quality opportunities, do not stop here. Use the Simply Wall Street screener to surface fresh, data driven ideas quickly.
- Target resilient businesses with healthy balance sheets and consistent fundamentals through a curated list of solid balance sheet and fundamentals (7 results) that keeps financial strength front and center.
- Hunt for mispriced opportunities by scanning a focused 3 high quality undervalued stocks that highlights companies where quality and current pricing appear out of sync.
- Prioritise income potential by zeroing in on a handpicked 3 dividend fortresses designed for investors who care about both yield and durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com