


How Investors Are Reacting To Gjensidige Forsikring (OB:GJF) Stronger Q3 Earnings
- Gjensidige Forsikring reported third quarter 2026 net income of NOK 2,076.7 million and basic earnings per share of NOK 4.08, with nine month net income of NOK 5,924.9 million and basic earnings per share of NOK 11.62.
- The comparison with the prior year shows higher net income and earnings per share for both the quarter and the first nine months, which indicates resilient profitability across Gjensidige Forsikring's core operations through 2026 so far.
- The next step is to consider how Gjensidige Forsikring's investment narrative could be influenced by this stronger third quarter net income performance.
Benchmark Gjensidige Forsikring's latest earnings momentum against other resilient insurers and financials by scanning our hand-picked list of 223 resilient stocks with low risk scores.
Gjensidige Forsikring Investment Narrative Recap
For you to stay interested in Gjensidige Forsikring, the core belief is that disciplined pricing, cost control and a broad Nordic footprint can keep underwriting solid while the pension arm gradually stops dragging on results. The latest quarter, with higher net income and earnings per share versus last year, supports that view but does not radically change it.
In the short term, the key watchpoint is still how well pricing keeps up with claims inflation and any residual impact from the Danish workers compensation ruling. The main operational risk remains the pension segment, which previously booked a sizeable pre tax loss and could again weigh on group returns if profitability does not stabilise.
The fresh earnings release is the most relevant update. Net income of NOK 2,076.7 million for the quarter and NOK 5,924.9 million for nine months, alongside higher earnings per share than a year ago, indicates that the insurance engine is doing the heavy lifting while management continues to work through known headwinds.
For catalysts, this matters because a stronger profit base gives Gjensidige Forsikring more room to keep investing in digitalisation, direct and partner distribution and the pension build out, even with concerns around dividend coverage by free cash flow. Your focus now is whether this level of performance proves repeatable as claims, bond yields and regulatory issues evolve.
Gjensidige Forsikring's current earnings are NOK 6.4b, with analysts forecasting NOK 10.3b of earnings on NOK 51.3b of revenue by 2029. This implies revenue growth of 2.6% a year and an earnings increase of about 61% from today.
Uncover why Gjensidige Forsikring's fair value indicates a 9% potential upside to its current price that could narrow quickly.
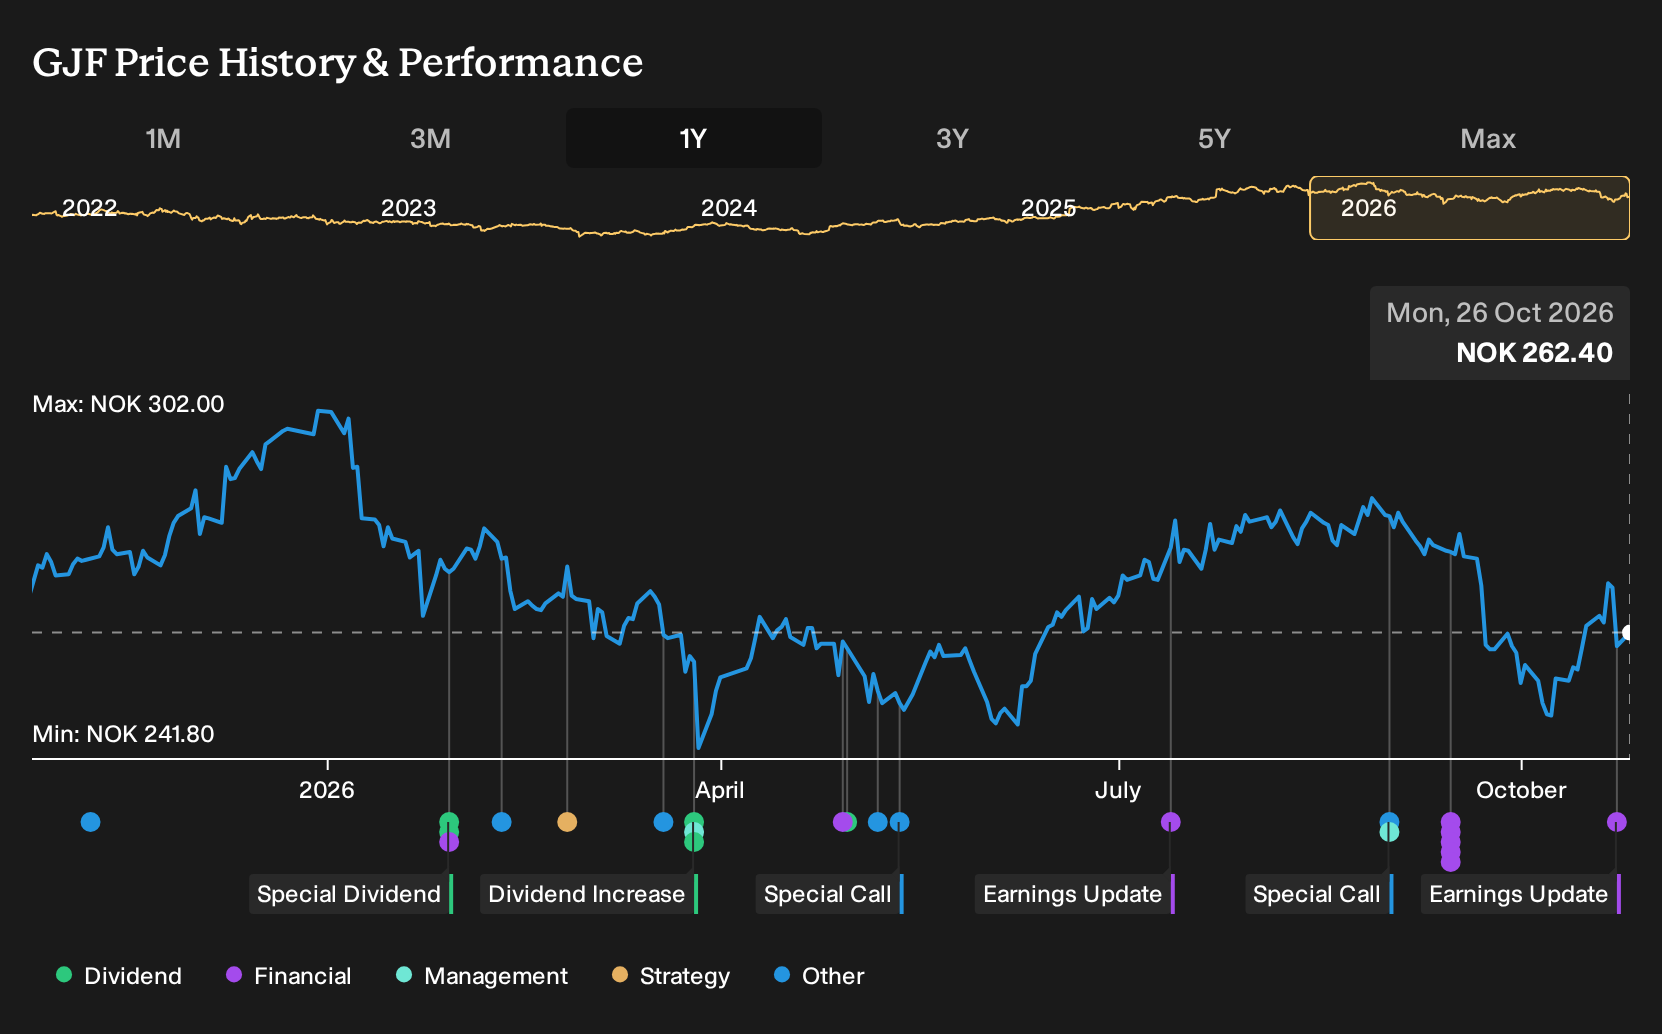
Exploring Other Perspectives
Some of the most optimistic analysts focus on Gjensidige Forsikring’s pension build out as the real swing factor. They were already pencilling in NOK 54.6b of revenue and NOK 11.1b of earnings by 2029, compared with NOK 51.3b of revenue and NOK 10.3b of earnings in the consensus case. This earnings beat may push those forecasts to be revisited, so use it as a cue to compare several viewpoints before deciding what you find credible.
Explore 3 other Gjensidige Forsikring fair value estimates, including one that suggests as much as 72% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Gjensidige Forsikring research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Gjensidige Forsikring. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gjensidige Forsikring's overall financial health at a glance.
Looking For More Investment Ideas Beyond Gjensidige Forsikring?
Once you have formed a view on Gjensidige Forsikring, it can help to cross check that thinking against other opportunities with different risk and income profiles. Use the Simply Wall St Screener to line up a wider watchlist and see how this insurer compares with alternatives that fit your own return and risk preferences.
- If capital protection is your priority, start with a basket of companies that score well on resilience and stability through the 223 resilient stocks with low risk scores.
- If you want income to play a bigger role in your portfolio, scan for higher yielding payers that still clear quality hurdles using the 224 dividend fortresses.
- If you are hunting for under followed opportunities with solid fundamentals, broaden your search to potential future leaders via the 610 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com