


Political Uncertainty Tests The Case For XP Stock
- XP Inc. reported that board member Martin Emiliano Escobari Lifchitz resigned in October 2026 and the board unanimously appointed Microsoft executive Rodrigo Kede Lima as an independent interim director through the 2027 annual meeting.
- Rodrigo Kede Lima brings experience from senior roles at Microsoft, IBM, TOTVS and other Brazilian corporates. This background could influence how XP balances technology investment, efficiency and product expansion decisions at board level.
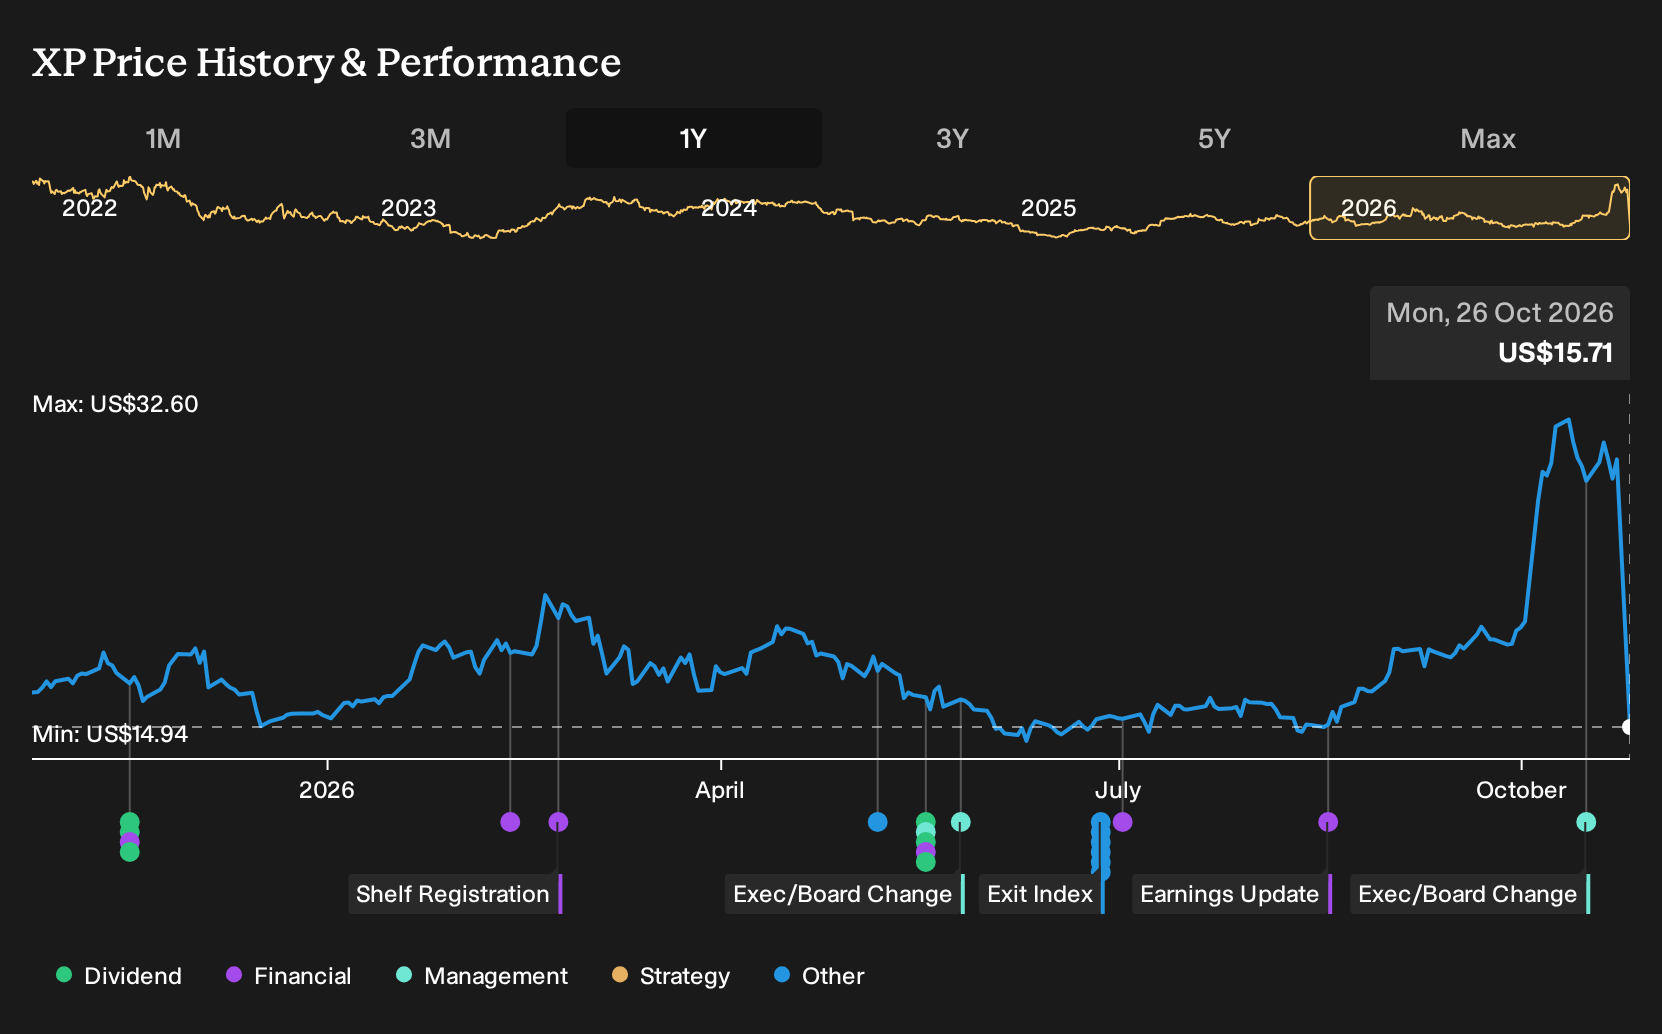
- We will examine how XP's investment narrative interacts with heightened Brazilian political uncertainty following President Lula's unexpected election victory.
Balance your view on XP by scanning a curated 30 resilient stocks with low risk scores that may hold up better when politics and boardroom changes start to weigh on sentiment.
XP Investment Narrative Recap
To own XP, you need to believe the business can keep turning Brazil’s growing investor base and product diversification into consistent fee income, even as client assets tilt toward lower take rate fixed income. The short term swing factor is sentiment around Lula’s policy direction, since that has already dragged Brazilian financials, including XP, lower. Board news itself does not materially shift that near term driver.
The bigger risk sits inside the model. Competitive pressure and a heavier mix of daily liquidity products and lower margin verticals could keep squeezing pricing just as XP keeps spending on technology and sales expansion. If revenue momentum softens while the efficiency ratio stays roughly flat, earnings and return metrics could struggle to keep pace with what investors might want to see.
The fresh appointment of Microsoft executive Rodrigo Kede Lima as an independent director is the governance angle most tied to this story. His track record across Microsoft, IBM and TOTVS plugs a clear gap for XP, which is trying to scale a tech heavy platform, broaden digital product usage and manage a complex, capital light brokerage and banking model.
For you as a shareholder, the link to catalysts is practical. XP is investing in AI tools, technology and a wider product suite while trying to hold its efficiency ratio steady and offset lower investment take rates through cross sell. A director steeped in large scale enterprise tech and Latin American operations could help the board scrutinize those investments, execution risk and payback periods at a moment when political uncertainty and share price volatility are already front of mind.
XP Through The Numbers
XP's narrative projects R$26.9b revenue and R$7.9b earnings by 2029. This rests on analysts assuming 13.0% yearly revenue growth and an earnings increase of about R$2.6b from R$5.3b today.
Uncover why XP's fair value indicates an 83% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You might see XP very differently if you focus on the risk that revenue grows more slowly than consensus expects. The most pessimistic analysts were already pencilling in R$25.3b revenue and R$7.5b earnings by 2029 before this board change. That is below the baseline R$26.9b and R$7.9b view, which shows how widely opinions vary. You can use this news to reassess which narrative feels closer to your own expectations.
Explore 2 other XP fair value estimates, including one that suggests it could be worth just $25.14!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your XP research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for XP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate XP's overall financial health at a glance.
Looking For More XP Investment Ideas Beyond This Stock?
If this XP story has you rethinking your portfolio mix, it can help to line it up against other companies with different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential upside without taking on extreme balance sheet risk, check out a curated 21 high quality undiscovered gems that combine quality fundamentals with quieter market attention.
- If capital preservation matters just as much as returns, compare XP with a list of solid balance sheet and fundamentals (24 results) and see which businesses look better equipped to handle bumps in the macro backdrop.
- When you are hunting for steadier income to sit alongside a stock like XP, line up the yield and payout profile against a selection of 5 dividend fortresses that focus on stronger cash distribution potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com