


How EU Label Expansion Will Impact Ionis Stock
- Ionis Pharmaceuticals reported that the EMA’s Committee for Medicinal Products for Human Use issued a positive opinion in October 2026 to extend TRYNGOLZA’s indication in the EU for adults with severe hypertriglyceridemia, grounded in Phase 3 data showing up to 72% placebo adjusted triglyceride reduction and fewer acute pancreatitis events.
- The CHMP opinion, arriving ahead of the expected timeline and covering a broader sHTG population, indicates a potential step up in TRYNGOLZA’s commercial reach for Ionis and its ex US partner Sobi if the indication extension is approved.
- This development could influence how investors view Ionis Pharmaceuticals’ overall narrative in light of the early positive CHMP opinion for TRYNGOLZA.
Ionis Pharmaceuticals Investment Narrative Recap
To own Ionis Pharmaceuticals, you need to believe the RNA medicine platform can support a shift from a largely R&D driven story to a multi product commercial business. TRYNGOLZA is central to that view. The early positive CHMP opinion signals regulatory momentum for sHTG in Europe, but the key near term catalyst remains final EC approval timing and label details.
The largest operational risk still sits in pricing and access as TRYNGOLZA moves from a rare FCS setting into a broader sHTG group. A wider label could deepen reliance on a few late stage assets and make any delay, restrictive label, or tougher than expected reimbursement more visible in revenue volatility.
The TRYNGOLZA sHTG CHMP opinion ties directly into prior expectations that expanding beyond rare disease patients could reshape Ionis Pharmaceuticals’ revenue mix. The CORE and CORE2 data package, including triglyceride reductions up to 72% and lower acute pancreatitis events, supports that thesis and will likely inform payer and physician views on clinical value.
The extension, if confirmed by the EC, would plug into an existing commercialization split where Ionis handles the U.S. and Sobi manages most ex U.S. markets. That keeps execution risk focused on label wording, pricing discussions, and partner performance rather than new infrastructure build out, while still leaving Ionis exposed to potential price pressure and reimbursement complexity in a larger chronic population.
Ionis Pharmaceuticals' current analyst narrative points to US$2.2b in revenue and US$261.6m in earnings by 2029, based on a forecast 36.3% yearly revenue growth rate and an earnings change of roughly US$827m from a loss of US$565.2m today to the 2029 consensus level.
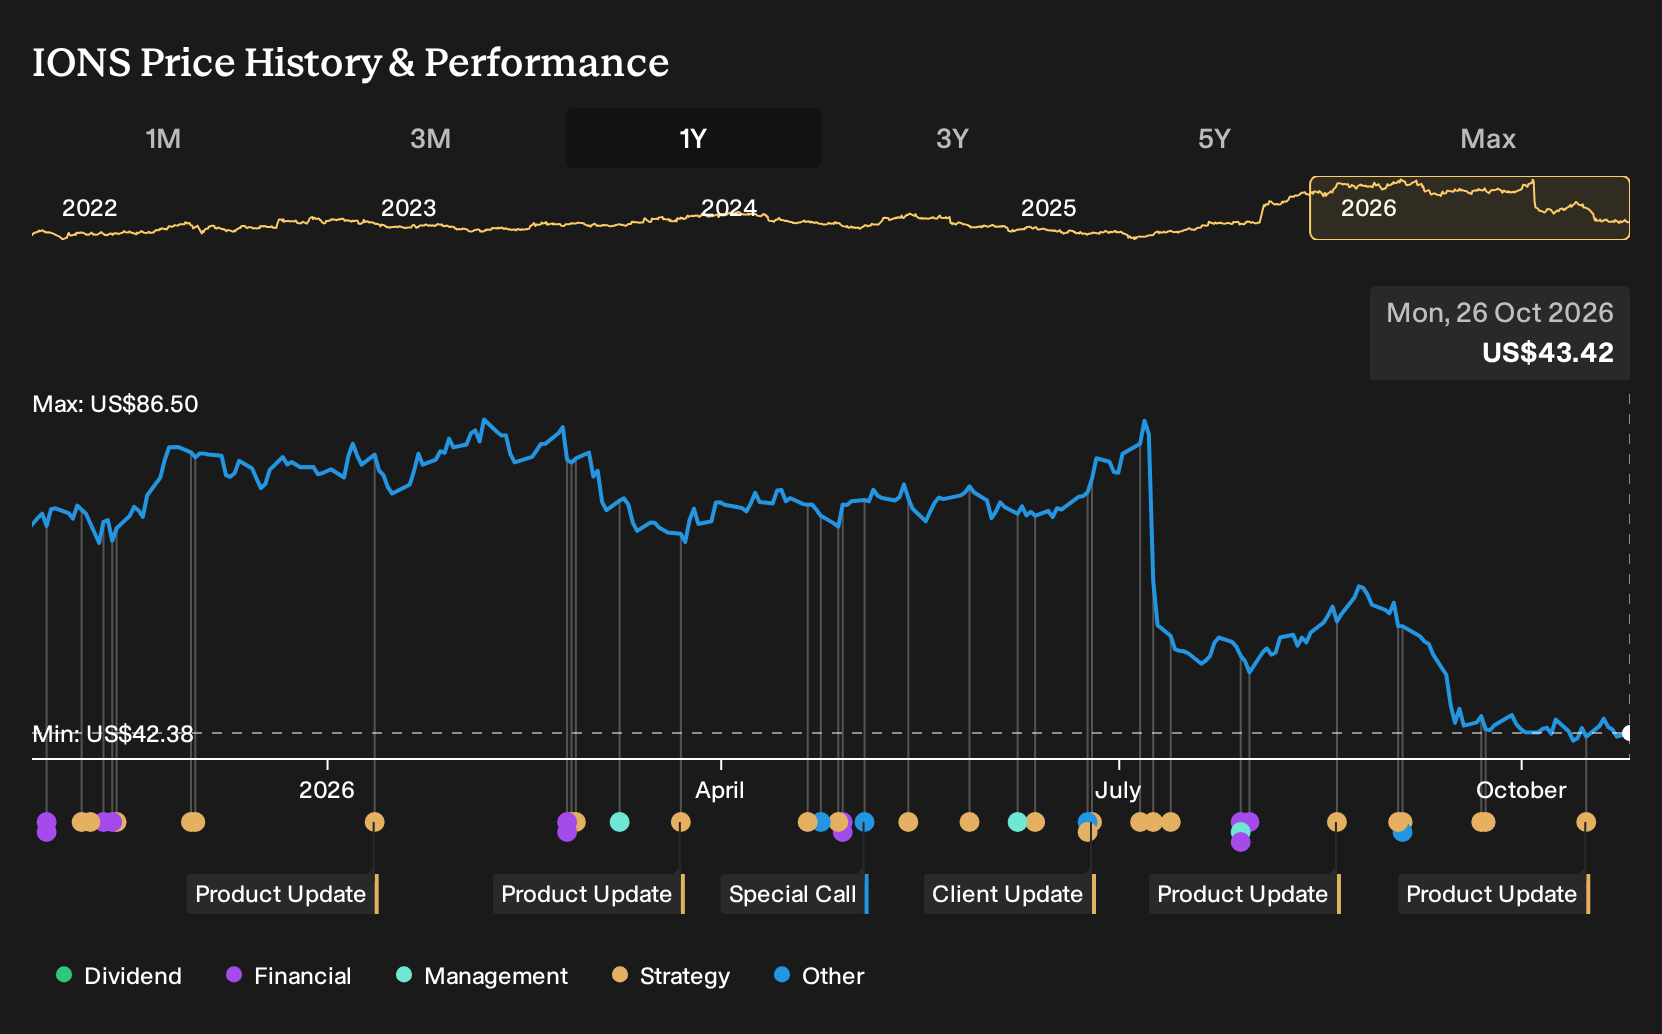
Uncover how Ionis Pharmaceuticals' fair value indicates a 93% potential upside to its current price that could close more quickly than many investors expect.
Exploring Other Perspectives
You also see a very different angle if you focus on the bullish revenue story around Ionis Pharmaceuticals. Before this CHMP news, the highest analysts were already penciling in about US$3.0b of 2029 revenue and US$712.1m of earnings. That is a far more optimistic story than the consensus, and it may shift again as this EU decision plays out.
Explore 3 other Ionis Pharmaceuticals fair value estimates, including one that suggests potential upside of as much as 604% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ionis Pharmaceuticals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Ionis Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ionis Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Ionis Pharmaceuticals?
If the Ionis Pharmaceuticals story has you thinking about where regulation, balance sheets, and future cash flows intersect, it makes sense to cast a wider net. The Simply Wall St Screener lets you filter for the kind of risk and quality profile that actually suits your approach, rather than relying on a single headline or forecast.
- Prefer resilience and capital preservation over drama? Start with a basket of companies screened for stability using the 30 resilient stocks with low risk scores to see which names score well on fundamentals and risk metrics.
- If you are hunting for quality at a sensible entry point, the 29 high quality undervalued stocks can spotlight businesses that pair stronger cash flows and solid balance sheets with prices that look appealing on key valuation checks.
- For readers who care most about income durability, the 5 dividend fortresses highlights companies offering higher yields while aiming to keep payouts supported by their financial profile.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com