


Is Profit Drop Altering The Investment Case For Lazard (LAZ)?
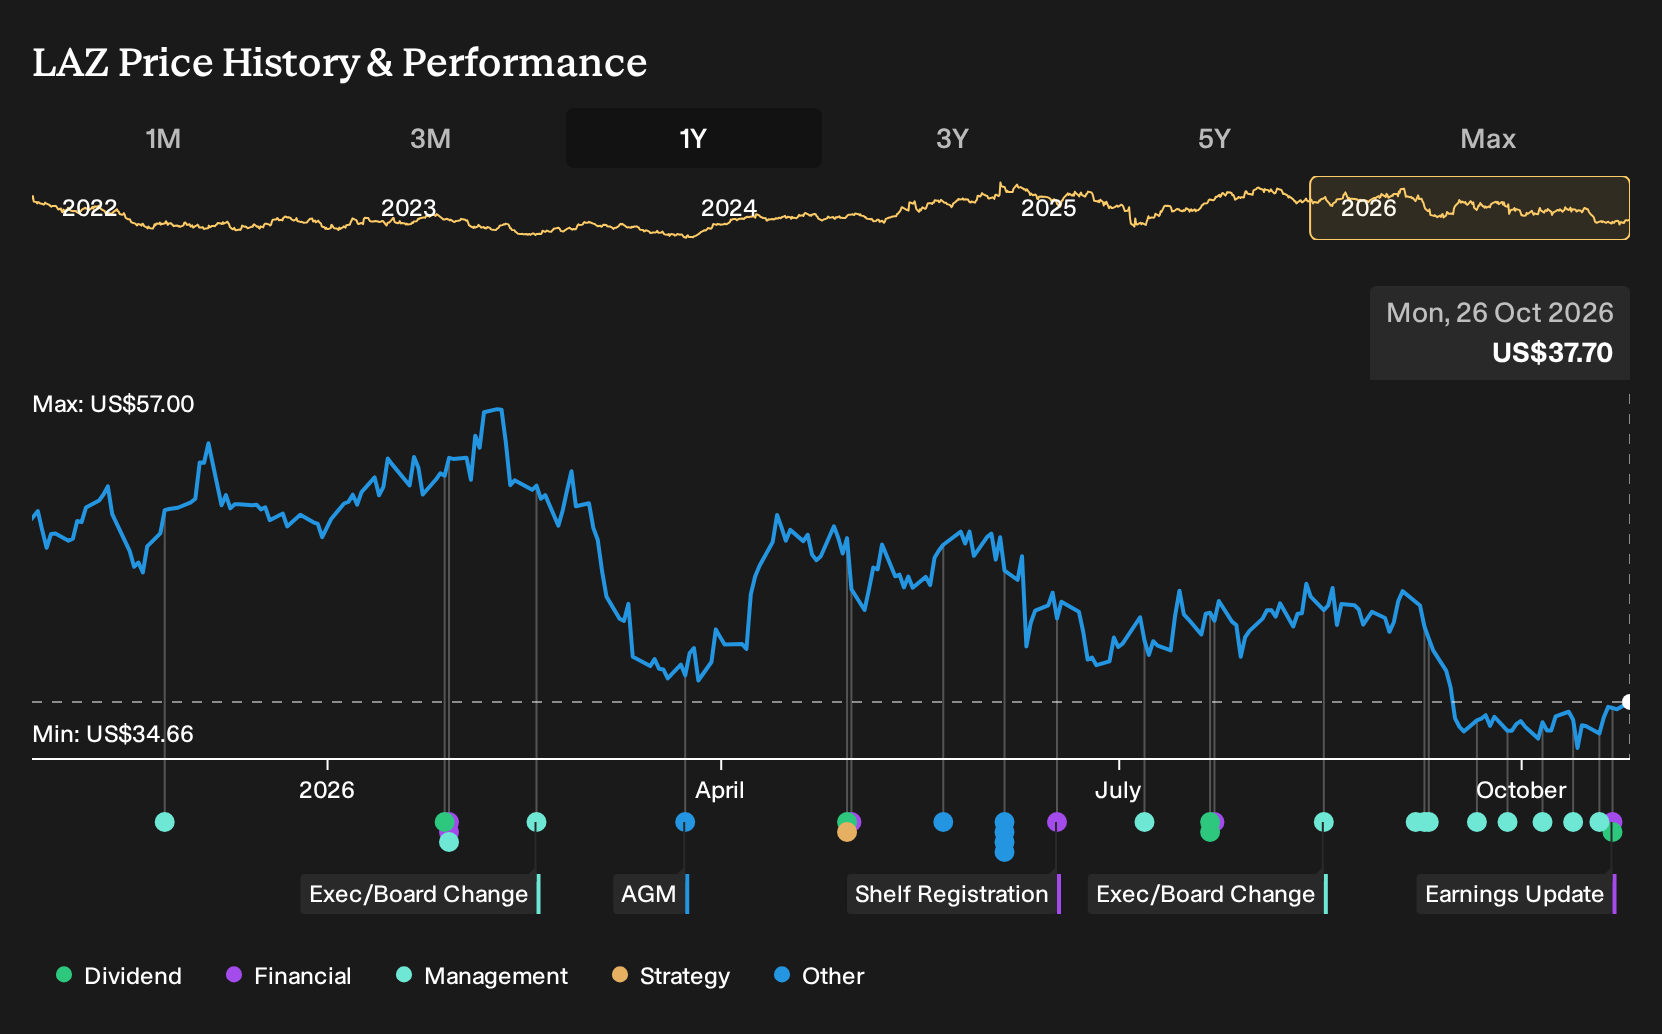
- Lazard, Inc. reported third quarter 2026 net income of US$29.16 million and basic EPS from continuing operations of US$0.27, both lower than the same period in 2025. The company also declared a quarterly dividend of US$0.50 per share, payable in November 2026.
- The earnings update highlights pressure on profitability while Lazard continues to invest in senior advisory talent and implement leadership changes tied to its Lazard 2030 plan.
- This article will examine how Lazard's weaker third quarter earnings may influence its broader investment narrative, which is built around diversification and productivity gains.
Scan how Lazard's mix of softer earnings and a maintained dividend compares with other income-focused opportunities by reviewing our curated list of 5 dividend fortresses.
Lazard Investment Narrative Recap
To own Lazard today, you need to believe the advisory rebuild, private capital push and asset management repositioning can outweigh a softer earnings patch. The third quarter drop in net income and EPS underlines that this transition is still costly. The near term swing factor is whether deal activity and fee pools stay firm enough for new hires and AI tools to show through.
The biggest risk right now is that elevated compensation and pressured net margins linger while assets under management waver, leaving earnings stuck. Third quarter results already show margin strain, so any further pullback in AUM or slower private capital progress could keep that pressure in place.
The most relevant fresh data point is the third quarter 2026 earnings release. Lazard reported net income of US$29.16 million, down from US$71.25 million a year earlier. Basic EPS from continuing operations moved from US$0.71 to US$0.27, with nine month net income at US$134.88 million versus US$186.97 million in the prior period.
Those figures matter because the whole Lazard 2030 story rests on higher advisory productivity, a richer private capital mix and better operating leverage. Weaker profit today makes that execution test sharper. For investors, the key question is whether current spending on senior bankers and technology can translate into the revenue mix and margin profile that management has laid out.
Lazard's current analyst narrative points to forecast revenue of US$4.6b and earnings of US$501.8 million by 2029, with this implying a 12.6% yearly revenue growth rate and an earnings increase of about US$282.8 million from US$219.0 million today.
Uncover how Lazard's fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
You can also weigh a very different angle on Lazard. The most bearish analysts focus on the risk that high compensation stays sticky. Before this earnings miss, they were already modeling about US$4.4b of 2029 revenue and roughly US$528.3 million of earnings. That more pessimistic story may shift again once this quarter is fully digested, so consider exploring both paths.
Explore 4 other Lazard fair value estimates, including one that suggests as much as 20% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Lazard research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Lazard. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lazard's overall financial health at a glance.
Looking for more investment ideas beyond Lazard?
Once you have a view on Lazard, it can help to compare that thesis with other opportunities that share traits you care about, whether that is income resilience, balance sheet strength or room for re rating.
- If you want income potential paired with an attempt at durability, scan our curated group of 5 dividend fortresses and see how their payout profiles line up with your goals.
- For readers who care most about financial robustness, start with the list of solid balance sheet and fundamentals (24 results) and compare how these businesses handle leverage and liquidity.
- If you prefer situations that the market may not be focusing on yet, work through the 21 high quality undiscovered gems and see which stories deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com