


How Investors May Respond To Bilia (OM:BILI A) Mixed Earnings Report
- Bilia reported third quarter 2026 sales of SEK 9,961 million and net income of SEK 185 million, with earnings per share from continuing operations at SEK 2.02.
- Across the first nine months of 2026, Bilia recorded SEK 30,482 million in sales and SEK 609 million in net income, indicating stronger year to date profitability than the previous year despite a softer third quarter bottom line.
- We will now examine how Bilia's softer third quarter earnings per share shapes the broader investment narrative around the business.
Compare Bilia's mixed quarterly earnings profile with other financially resilient auto and consumer companies by scanning our hand picked list of solid balance sheet and fundamentals (207 results).
Bilia Investment Narrative Recap
Bilia appeals to shareholders who think a mixed but resilient earnings profile can support the shift toward higher Service contribution, efficiency savings and an electric heavy car park. The latest quarter showed slightly softer earnings per share than a year ago, while the nine month figures point to firmer profitability, so the short term story looks unchanged.
The near term swing factor remains how quickly order backlog converts to deliveries without eroding used electric margins. Pressure on fully electric pricing and a still muted new car market in Sweden continues to be the main operational risk. This quarter’s figures do not materially change that risk balance.
The fresh earnings release for the third quarter and first nine months of 2026 is the key update to watch here. Bilia reported SEK 9,961 million in quarterly sales and SEK 185 million in net income, with basic EPS from continuing operations of SEK 2.02, while year to date EPS reached SEK 6.64 from continuing operations.
Those numbers provide a current read on how well the efficiency program, Service focus and used car stock management are feeding through to the income statement. Slightly softer quarterly EPS, set against stronger year to date profit, keeps attention on execution around electric vehicle inventory, workshop utilisation and the timing of the targeted SEK 150 million annual cost savings.
Bilia Earnings Assumptions and Valuation Setup
Bilia's consensus scenario points to SEK 47.0 billion in revenue and SEK 1.4 billion in earnings by 2029. That profile lines up with forecast revenue growth of 5.1% per year and an earnings increase of about SEK 557 million from current earnings of SEK 843 million.
Uncover why Bilia's fair value indicates a 21% potential upside to its current price that may not last much longer.
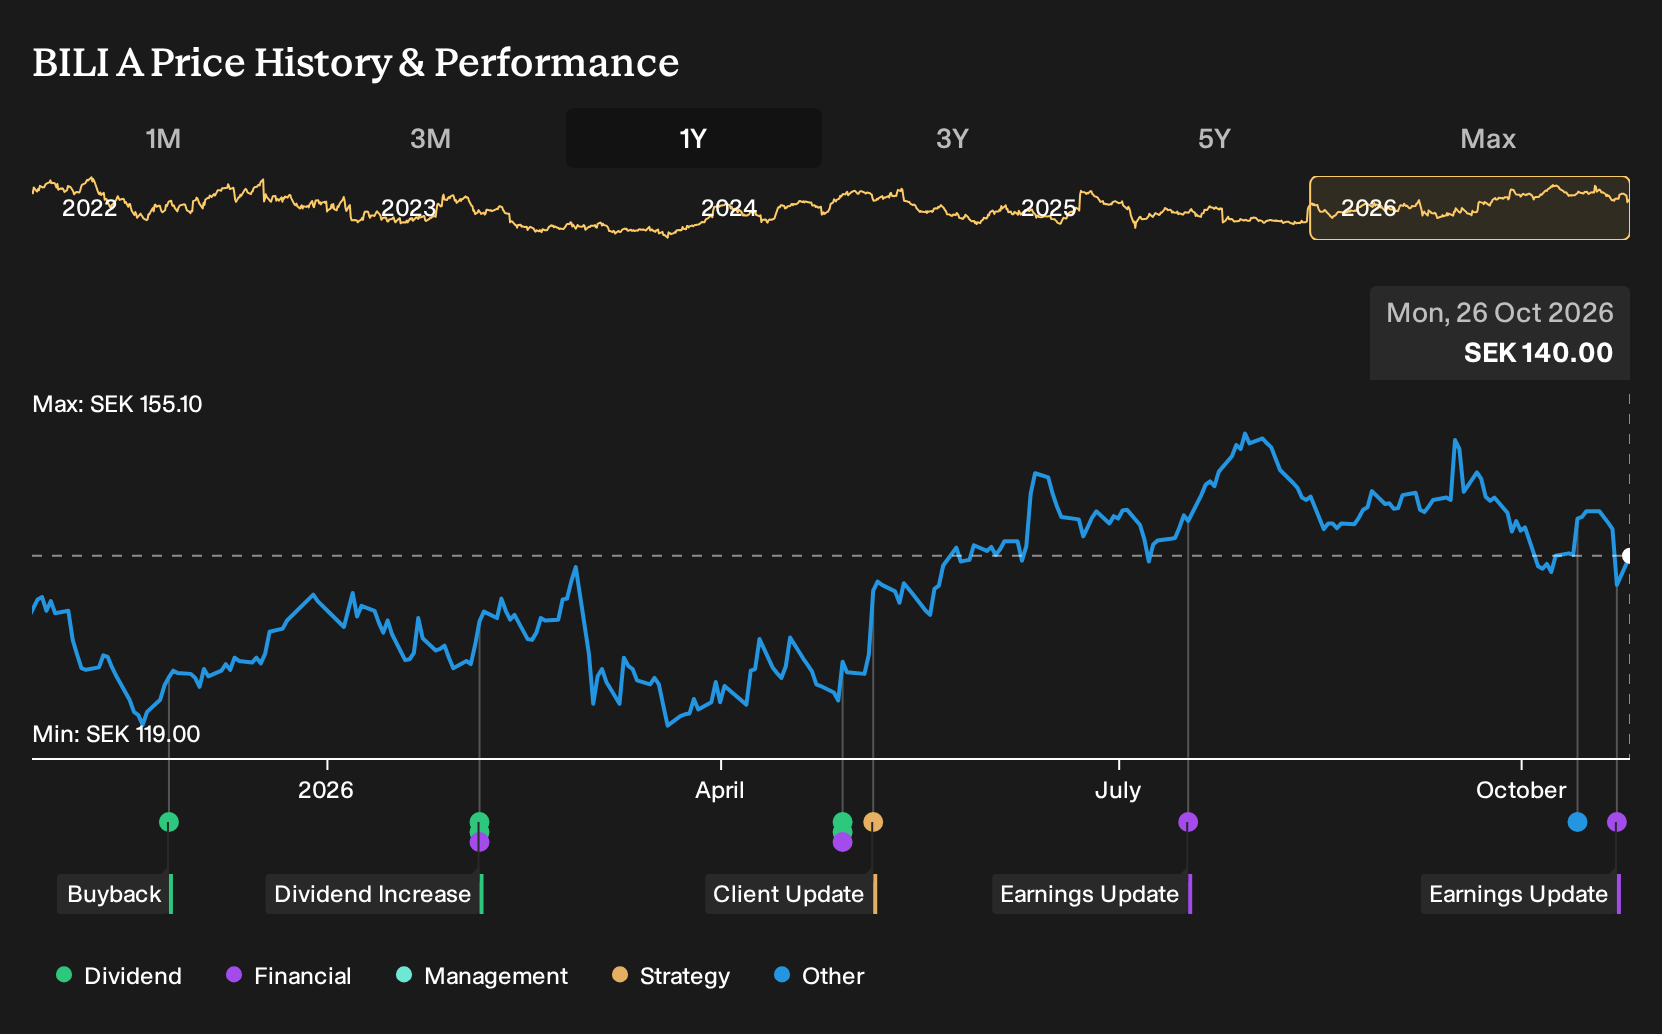
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from SEK 169 up to about SEK 228 per share, which shows how far opinions on Bilia can stretch. You also need to weigh those views against risks around Swedish electric vehicle demand, physical dealerships and new car volumes, and then explore several alternative viewpoints.
Explore another Bilia fair value estimate, including one that suggests it could be worth just SEK169.00!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bilia research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Bilia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bilia's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bilia?
If you want to stress test your view on Bilia against a wider set of opportunities, the Simply Wall St Screener can help you line up other potential candidates with clear financial traits and compare them side by side.
- For income focused investors who want stability as well as yield, scan a curated group of 224 dividend fortresses that combine higher payouts with resilient business profiles.
- If capital preservation is your first filter, sort the market by resilience and balance sheet strength using a tailored set of 223 resilient stocks with low risk scores designed to limit downside risk.
- When you want something off the beaten path with solid fundamentals, cast a wider net across 610 high quality undiscovered gems that may sit outside the usual watchlists but still meet strict quality criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com