


Could Higher Earnings Estimates Alter The Investment Case For Assurant (AIZ)?
- Assurant has outperformed the broader Finance sector so far this year, with a roughly 18.2% year to date return versus about 4.3% for its sector peers, alongside a 6.5% uplift in the Zacks consensus estimate for full year earnings over the past quarter.
- The jump in Assurant's earnings forecast points to stronger expectations for how its fee based protection and services model might translate into future profitability. This could influence how investors weigh its capital light businesses against peers.
- We will now look at how Assurant's stronger full year earnings estimates might reshape the investment narrative that analysts have built.
Scan for other potential outperformers built on resilient earnings stories by checking the 29 high quality undervalued stocks, which share some of the same quality and value traits investors are watching in Assurant.
Assurant Investment Narrative Recap
To own Assurant, you need to believe its fee based protection model in Global Lifestyle and Global Housing can keep converting connected devices, auto and housing programs into durable earnings, even as headline growth is moderate. The recent outperformance and higher full year earnings estimate reinforce that story in the near term without radically changing it.
The key short term swing factor is execution on capital light, service heavy contracts that support margins while catastrophe costs and reinsurance terms remain manageable. The biggest risk still sits in lender placed housing exposure, where any renewed regulatory or legal pressure on pricing would matter more than this latest guidance lift.
The earnings upgrade that underpins the recent Assurant news ties back to the same operational levers analysts have been watching. Fee income from connected devices and housing solutions, supported by millions of protected devices and serviced claims, remains the core earnings engine that analysts expect to grow in the mid single digits.
That backdrop intersects directly with the catalysts around AI, automation and digital platforms in Connected Living, Automotive and Housing. Better claims handling and cost control support margins if these investments keep working, while slower forecast growth than the broader US market and regulatory scrutiny in lender placed products remain firmly on the risk side of the ledger.
Assurant's narrative projects US$15.8b revenue and US$1.2b earnings by 2029. This assumes 5.6% yearly revenue growth and about a US$0.1b earnings increase from US$1.1b today.
Uncover why Assurant's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
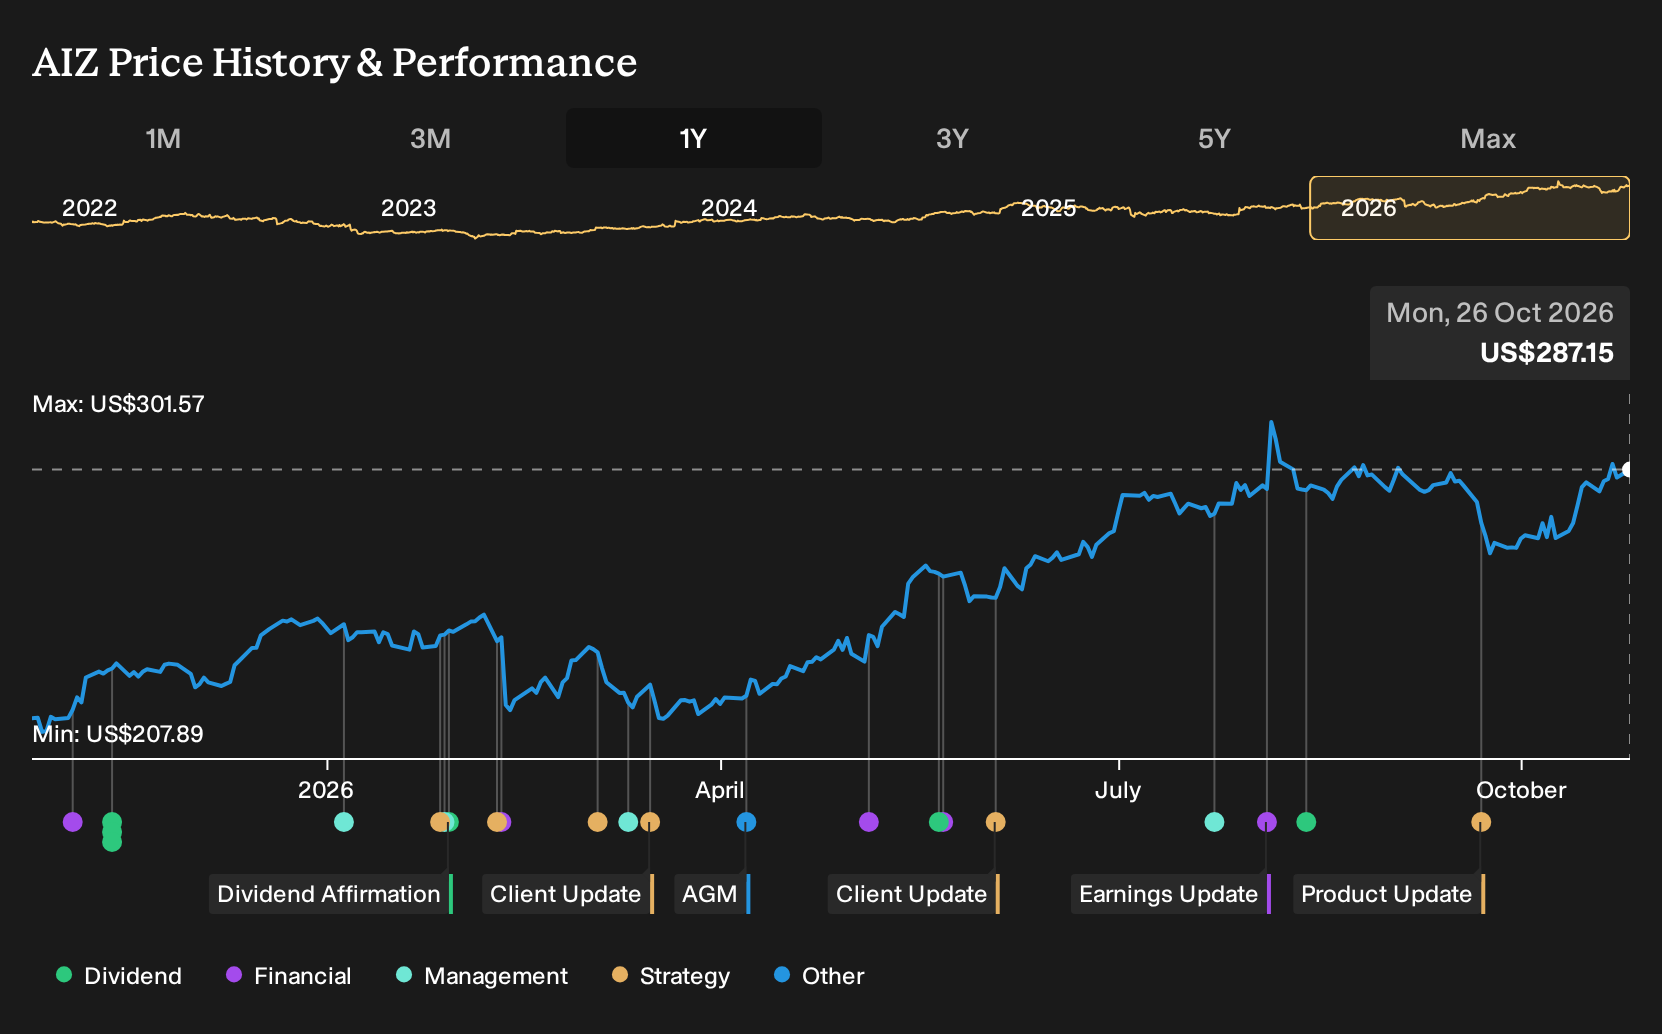
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$330 to about US$529 per share for Assurant, a wide band for just a pair of retail models. Your own stance may shift once you weigh that spread against lender placed regulatory risk, institutional ownership trends, and the AI driven cost work underway.
Explore another Assurant fair value estimate, including one that suggests it could be worth just $330.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Assurant research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Assurant. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Assurant's overall financial health at a glance.
Looking For More Investment Ideas Beyond Assurant?
If the Assurant story has sharpened your views on quality, risk and earnings resilience, broaden that process by scanning other opportunities that fit those preferences using the Simply Wall St Screener.
- For investors who want income that does more of the heavy lifting, start with resilient payers by reviewing 5 dividend fortresses that already yield above 5%.
- If capital preservation ranks high on your list, narrow the field to steadier operators through a 30 resilient stocks with low risk scores that filters for businesses with more durable profiles.
- When the aim is to uncover tomorrow's potential leaders before they are widely followed, work through a 21 high quality undiscovered gems that already pair strong fundamentals with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com