


Aeon (TSE:8267) Resets Its Dividend Story On Half Year Results While Valuation Debate Builds
Aeon (TSE:8267) has put its capital return approach in the spotlight after half year results, pairing detailed dividend guidance and a commemorative payout with clarification of how its prior 3 for 1 stock split affects comparisons.
Against that backdrop, Aeon’s 1-day share price return of 1.65% and 7-day gain of 3.80% sit in sharp contrast with a 30-day decline of 7.65% and a 90-day drop of 15.46%. The year-to-date share price return is down 51.69%, even though the 3-year and 5-year total shareholder returns of 20.19% and 42.05% point to a much stronger longer run story.
Scan how Aeon’s dividend reset compares with other companies that pair shareholder payouts with earnings momentum by reviewing our hand picked 29 dividend fortresses in one place.
Aeon now trades after a sharp year-to-date fall but with fresh earnings and a reworked dividend roadmap on the table. Does that reset skew the risk reward toward patient buyers, or keep caution in charge?
Most Popular Narrative: 13% Undervalued
Aeon closed at ¥1,200.5, while the most followed narrative pegs fair value closer to ¥1,384, which frames the recent share price pullback very differently for long term holders.
The main requirement is successful execution on private brand expansion, joint procurement, and structural cost reform so that the targeted gross profit uplift and productivity gains are reflected in operating profit and ROE.
The current valuation implies the market is pricing Aeon as if its planned shift toward higher-margin segments, Vietnam growth focus, and asset revitalization will not fully translate into the FY2030 revenue, profit, and capital efficiency targets that management has set, which underpins the view that the stock is undervalued and the narrative is bullish.
See why 6 investors see Aeon as 13% undervalued.
Result: Fair Value of ¥1,384 (UNDERVALUED)
Still, the Aeon narrative hinges on digital and cost projects cutting expenses, and on private brands plus joint procurement lifting profitability, both of which could disappoint.
Find out about the key risks to this Aeon narrative.
Another View: Aeon Through The P/E Lens
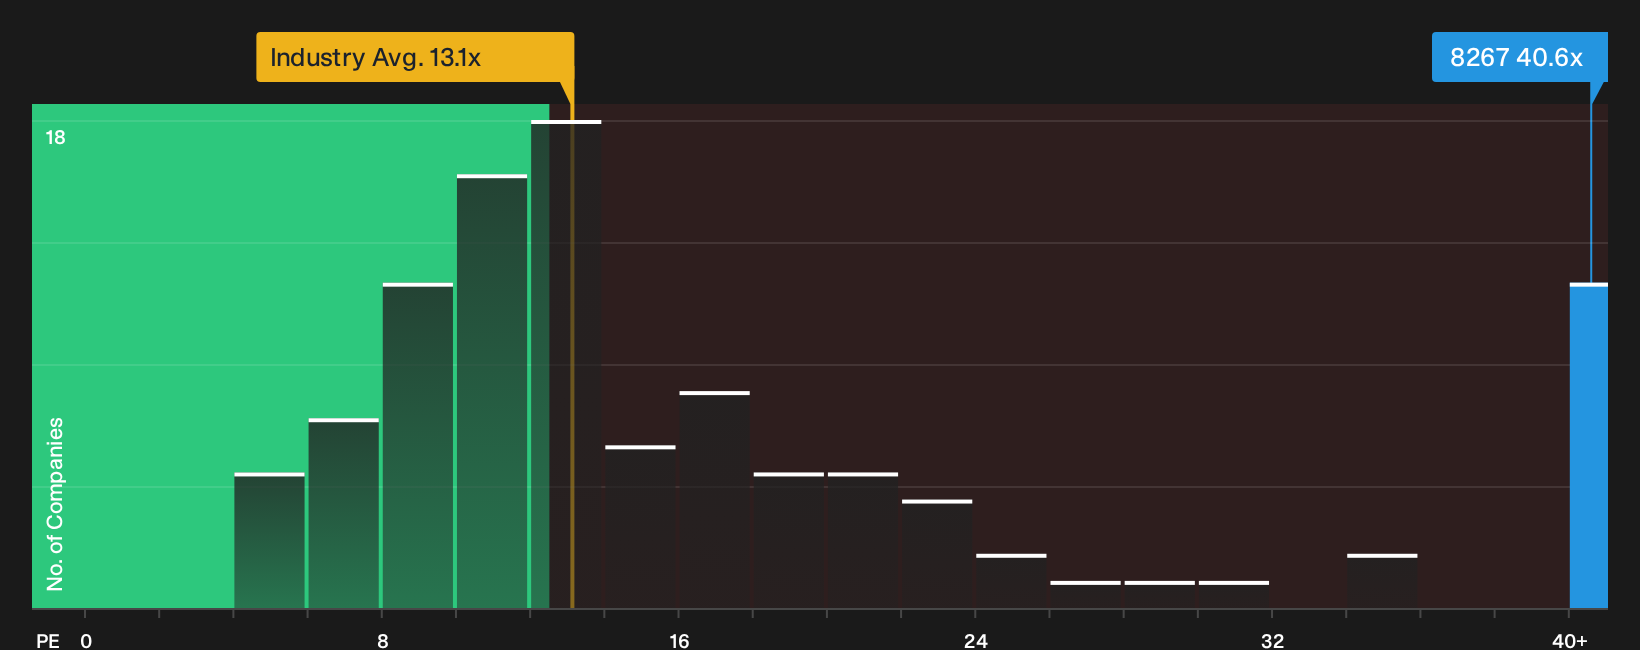
The story looks different when Aeon is viewed through its current P/E of 40.6x. That is much higher than the JP Consumer Retailing average of 13.1x and above the fair ratio estimate of 20.6x, which points to valuation risk if sentiment on earnings softens.
For investors weighing that gap against the bullish narrative, it helps to see how the numbers stack up in detail, then decide which earnings path feels more realistic for you. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Aeon can be confusing, so act promptly and review the full picture of both pressure points and bright spots. You can start by weighing the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Aeon?
If Aeon is on the watchlist, it can be useful to compare it with other opportunities that share similar qualities or offer a very different profile.
- Look for potential opportunities with higher return potential by scanning 16 high quality undervalued stocks, which highlights companies that combine solid fundamentals with prices that may lag their underlying business quality.
- Prioritise resilience and see how your portfolio could benefit from 22 resilient stocks with low risk scores, which focuses on companies with stronger balance sheets and lower risk scores.
- Search for tomorrow’s potential leaders early by checking 72 high quality undiscovered gems, which flags companies that already show strong financial traits before they attract wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com