


What to Expect From DuPont de Nemours’ Next Quarterly Earnings Report
DuPont de Nemours, Inc. (DD) is a global technology company developing advanced materials and solutions for healthcare, water treatment, construction, and industrial applications. Valued at around $18.4 billion, the Wilmington, Delaware-based company serves markets worldwide with a diverse portfolio spanning protective materials, filtration systems, insulation, adhesives, specialty lubricants, and engineered components.
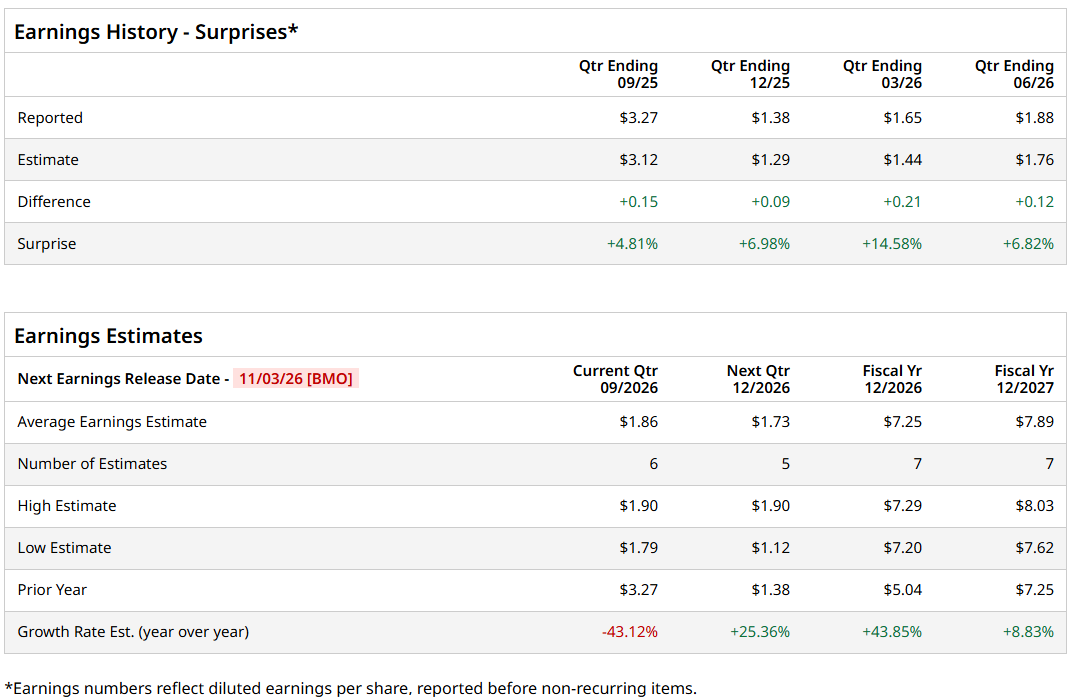
With its next earnings announcement approaching, DuPont is scheduled to release its Q3 FY2026 results before the market opens on Tuesday, Nov. 3. Analysts expect diluted EPS of $1.86, down 43.1% from the year-ago quarter. The forecast contrasts with the company’s recent track record, as DuPont has beaten EPS estimates in each of the past four quarters.
Despite the anticipated quarterly decline, the broader earnings outlook remains encouraging. Wall Street projects diluted EPS of $7.25 for full-year FY2026, representing year-over-year (YOY) growth of 43.9%. For FY2027, analysts expect the bottom line to reach $7.89, marking a rise of 8.8% from the previous year.
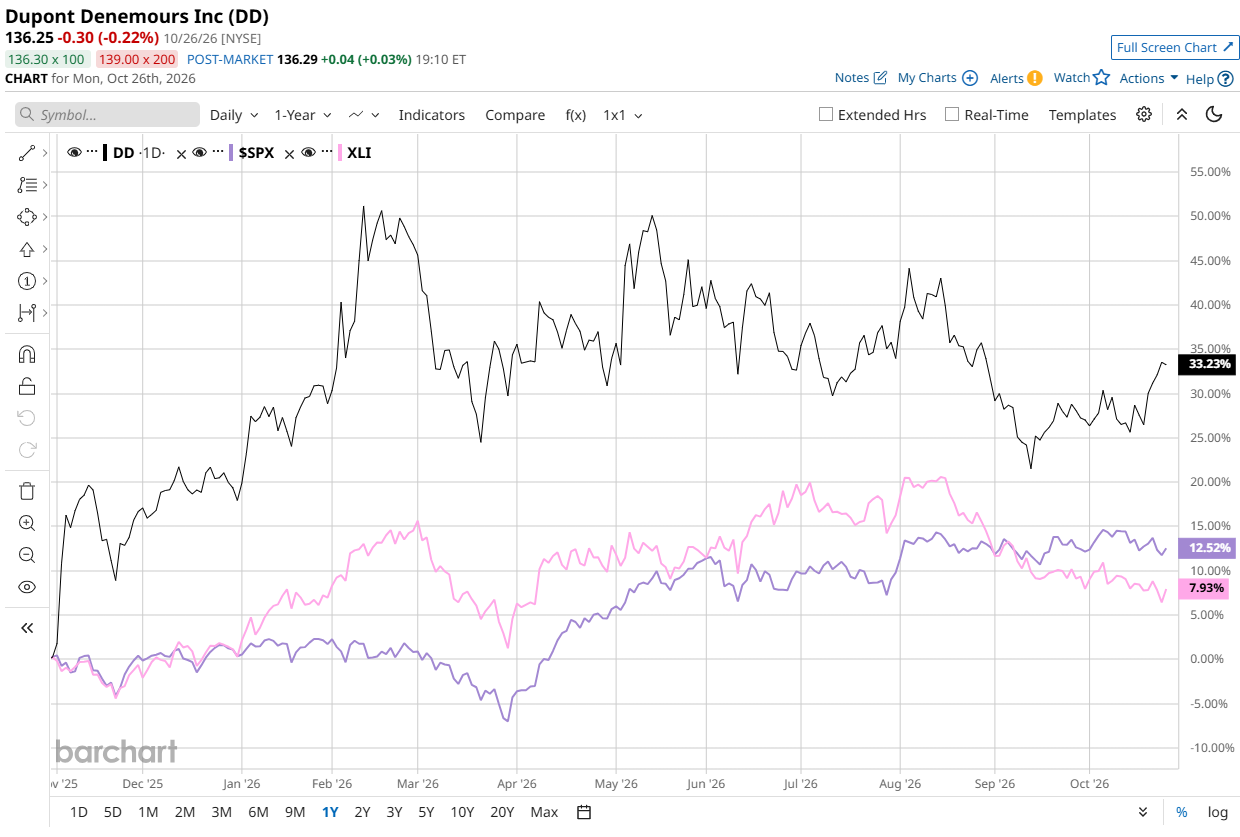
Investors have already rewarded DuPont with strong share-price gains. Over the past 52 weeks, DD stock surged 34%, outpacing the S&P 500 Index ($SPX), which gained 13%. The momentum has carried into 2026, with shares climbing 13% year-to-date (YTD), compared with a 12.1% rise for the broader market.
DuPont’s outperformance extends beyond the broad-market benchmark to its industrial peers. Over the past 52 weeks, the State Street Industrial Select Sector SPDR ETF (XLI) has gained 7.8%, while its YTD advance stands at 7.6%. Both figures trail DuPont’s returns, highlighting the stock’s relative strength across the two comparison periods.
Behind these gains are firmer demand across healthcare, industrial water, and aerospace markets, alongside productivity improvements. DuPont’s latest reported quarterly performance offered support for the momentum, with Q2 FY2026 results exceeding the company’s guidance.
Sales rose 4% YOY to $1.82 billion, while operating EBITDA increased 5.9% to $448 million. Adjusted EPS also improved 48% from the year-ago quarter to $1.88, reflecting stronger profitability and operating performance.
Building on these results, DuPont has raised its full-year 2026 outlook, increasing the midpoint of its adjusted EPS guidance by $0.15 to $7.24 and forecasting organic sales growth slightly above 4%. Management expects mid-single-digit organic growth in the second half, with free cash flow conversion remaining above its 90% target.
The operating outlook is broadly consistent with Wall Street’s favorable assessment of the stock. Among 17 analysts covering DD stock, the overall rating is “Moderate Buy.” Of those analysts, 11 recommend a “Strong Buy,” one assigns a “Moderate Buy,” and five rate the stock “Hold.”
To that end, the average price target of $162.65 represents potential upside of 19.4%. Meanwhile, the Street-High target of $186 points to a gain of 36.5% from current levels.
On the date of publication, Aanchal Sugandh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.