


Vaisala Oyj (HLSE:VAIAS) Unveiled New AI Weather Tools, Is The Stock Above Fair Value?
Vaisala Oyj (HLSE:VAIAS) has drawn fresh attention after unveiling its Viewlinc Cloud Suite environmental monitoring platform alongside new lifecycle services, and through Xweather's collaboration with NVIDIA on longer lead time AI-based lightning forecasts.
Set against these product launches and the NVIDIA partnership, Vaisala Oyj’s share price has climbed 16.79% over 90 days and 47.13% year to date. Its 1 year total shareholder return of 51.71% highlights momentum that has extended beyond recent headlines.
Capitalize on the momentum around Vaisala Oyj and AI-driven weather tech by scanning a curated set of 55 AI infrastructure stocks that could benefit from similar demand for critical data infrastructure.After that kind of run, Vaisala Oyj now trades fractionally above the €63.20 analyst target while still screening at a 5.5% intrinsic discount. Which reference point does fair value really lean toward?
Most Popular Narrative: 5.3% Overvalued
On the most followed view, Vaisala Oyj carries a fair value of €60.8 per share, which sits below the latest €64.0 close, so the recent surge now leans ahead of that central estimate.
Broad based growth in Industrial Measurements, with orders rising 21% in constant currencies in 2025 and a further 28% in Q2 2026 while exposure spans life sciences, data centers, power, semiconductors and batteries, supports the view that Vaisala can keep shifting its sales mix toward less cyclical end markets and potentially support both revenue and earnings resilience.
See why 11 investors see Vaisala Oyj as 5% overvalued.
Result: Fair Value of €60.8 (OVERVALUED)
Still, weakness in renewable energy demand and uneven public sector weather project spending could pressure Vaisala Oyj if expected contracts or high margin sales slip.
Find out about the key risks to this Vaisala Oyj narrative.
Another View: Cash Flows Paint Vaisala Oyj As Undervalued
The first narrative leans on analyst targets and earnings multiples and lands on Vaisala Oyj as 5.3% overvalued. A second lens tells a different story. On Simply Wall St’s DCF model, the shares at €64 sit around 5.5% below an estimated future cash flow value of €67.75, which frames recent enthusiasm as slightly cheap rather than stretched. Which lens do you trust more when real money is on the line?
If you want to see how those cash flow assumptions are built line by line, it is worth spending time with the SWS DCF model itself, rather than just the headline fair value number. Look into how the SWS DCF model arrives at its fair value.
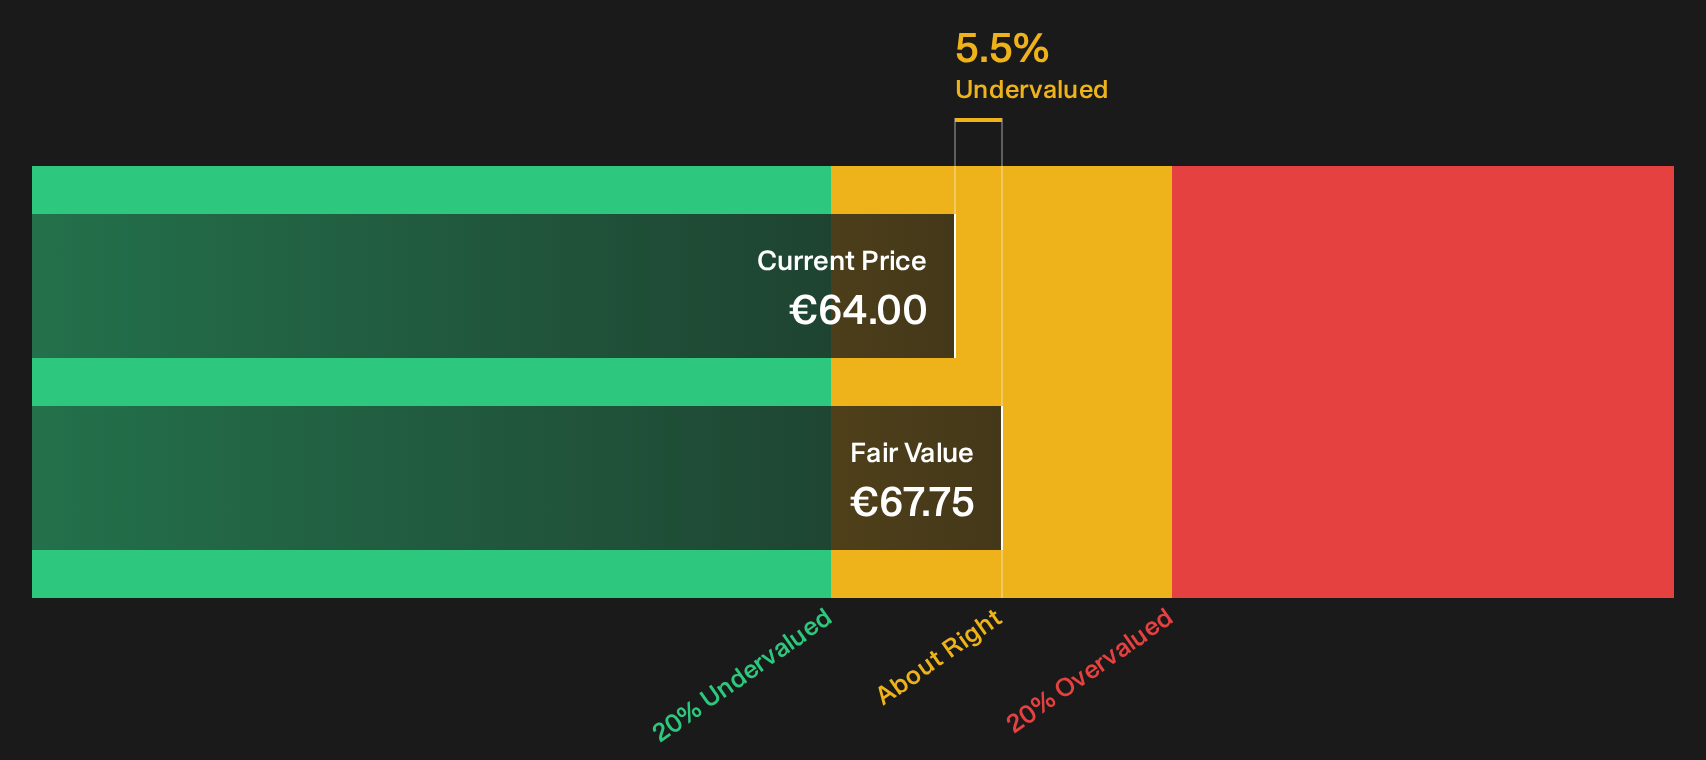
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Vaisala Oyj for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Strong opinions are already forming around Vaisala Oyj, so it makes sense to review the numbers yourself and decide quickly where you land. To see what optimism is built on, start with the 3 key rewards.
Looking for more investment ideas beyond Vaisala Oyj?
If you are serious about building a stronger portfolio, broaden your search with a few focused screeners that surface opportunities you might otherwise overlook.
- Target resilient cash generative businesses by scanning a 195 high quality undervalued stocks that combines constructive pricing with fundamentals the market may not be fully pricing in.
- Prioritize capital preservation and steadier compounding by working through a 223 resilient stocks with low risk scores designed to highlight companies with more measured risk profiles.
- Add potential income pillars to your watchlist by reviewing a 224 dividend fortresses that points to stocks offering higher yield alongside ongoing shareholder returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com