


Undervalued European Small Caps With Insider Action To Explore In October 2026
In October 2026, the European markets have been navigating a complex landscape characterized by heightened inflationary pressures and geopolitical tensions, leading to a decline in major indices such as the STOXX Europe 600. Amidst this backdrop, small-cap stocks have shown resilience and potential for growth, particularly those with insider activity that may signal confidence in their future prospects.
Top 10 Undervalued Small Caps With Insider Buying In Europe
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| LSL Property Services | 14.7x | 1.4x | 44.04% | ★★★★★☆ |
| Vp | NA | 0.6x | 34.85% | ★★★★★☆ |
| Hanza | 29.4x | 1.2x | 43.15% | ★★★★☆☆ |
| Franchise Brands | 27.0x | 2.0x | 48.03% | ★★★★☆☆ |
| Saniona | 8.4x | 3.6x | 22.75% | ★★★★☆☆ |
| W.A.G payment solutions | NA | 0.4x | 19.39% | ★★★★☆☆ |
| Nyab | 19.5x | 0.9x | 31.57% | ★★★☆☆☆ |
| Cibus Real Estate | 11.2x | 4.7x | -2826.32% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.7x | 22.50% | ★★★☆☆☆ |
| Travis Perkins | NA | 0.3x | -242.43% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
Tamburi Investment Partners (BIT:TIP)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Tamburi Investment Partners is an Italian investment company focused on investment banking and merchant banking activities, with a market capitalization of approximately €1.41 billion.
Operations: The company generates revenue primarily from its investment banking and merchant banking activities, with recent figures showing €5.03 million in revenue. The cost of goods sold (COGS) was reported at €2.90 million, leading to a gross profit margin of 42.32%. Operating expenses amounted to €26.84 million, significantly impacting net income, which stood at just €0.41 million for the latest period analyzed.
PE: 3442.5x
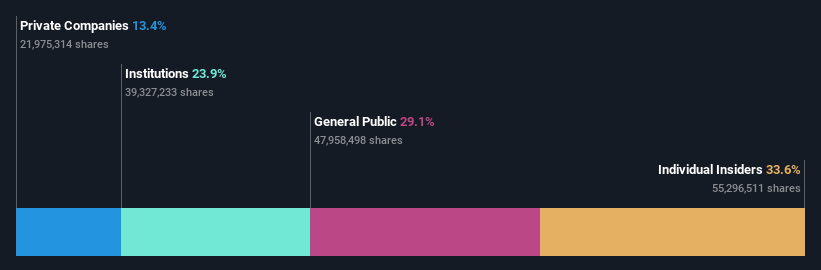
Tamburi Investment Partners, a European small cap, has seen insider confidence with share purchases throughout 2026. Despite reporting a net loss of €15.4 million for the first half of 2026, compared to a net income of €57.32 million last year, their revenue grew significantly from €0.73 million to €3.01 million year-over-year. The company is poised for potential growth with earnings forecasted to increase by 24% annually, suggesting room for future value realization amidst current challenges.
Target Healthcare REIT (LSE:THRL)
Simply Wall St Value Rating: ★★★★★☆
Overview: Target Healthcare REIT is a UK-based real estate investment trust specializing in the acquisition and management of care home properties, with a market capitalization of approximately £0.57 billion.
Operations: Target Healthcare REIT generates revenue primarily from property investment, with a recent figure of £72.07 million. The company has shown a consistent gross profit margin around 88.66% as of the latest period, indicating efficient management of its cost structure relative to revenue generation. Operating expenses and non-operating expenses have fluctuated over time, impacting net income margins which have varied significantly across periods.
PE: 8.7x
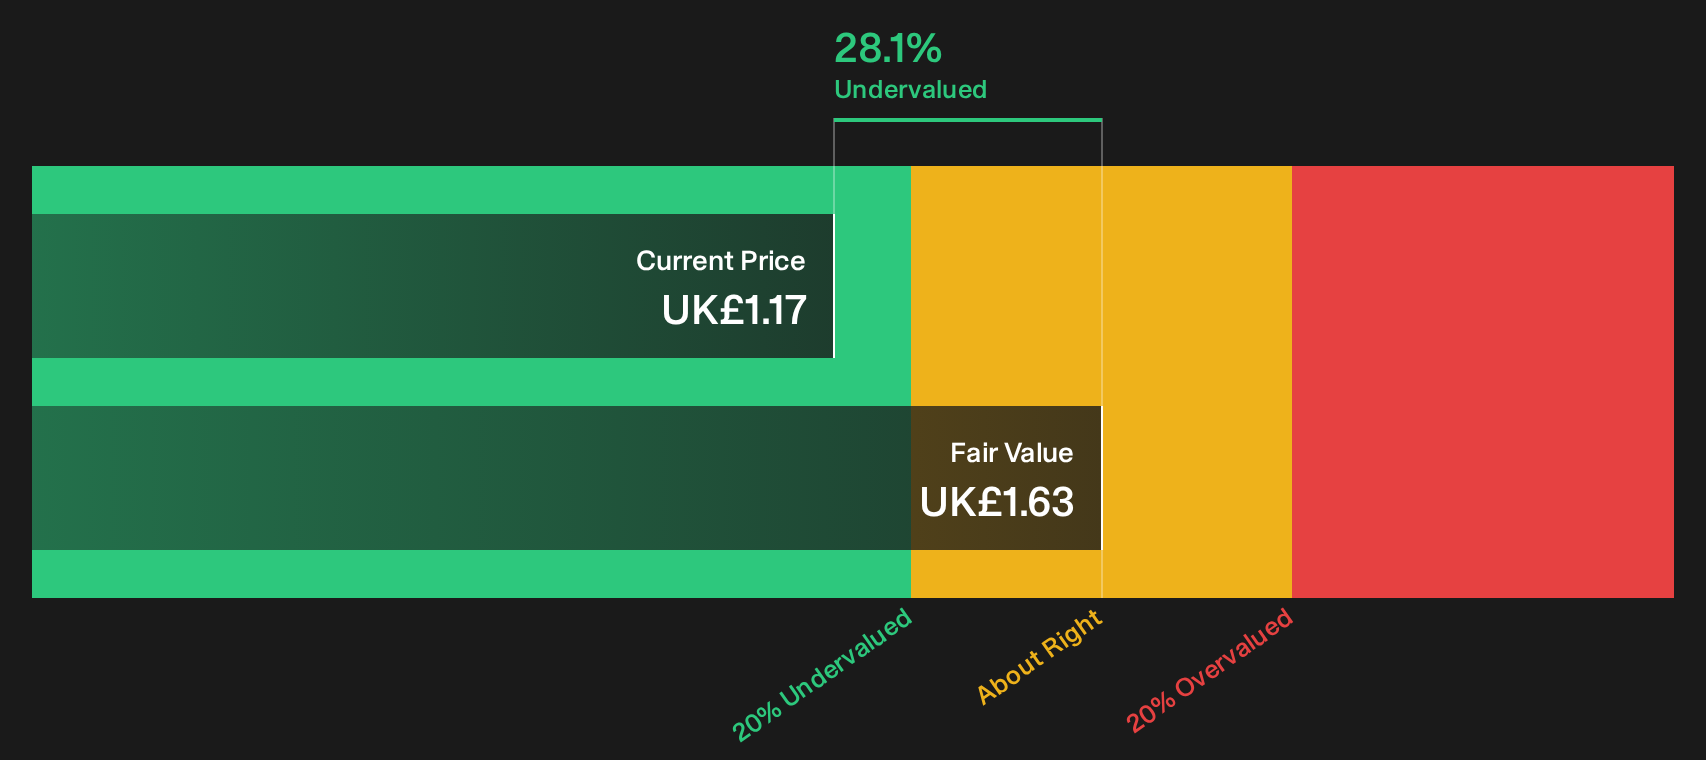
Target Healthcare REIT, a player in the healthcare real estate sector, has seen insider confidence with Kenneth MacKenzie acquiring 275,000 shares valued at £312,400. Despite earnings expected to decline by 2.6% annually over three years and reliance on external borrowing for funding, the company reported strong revenue growth to £102.65 million for the year ending June 2026. Additionally, they plan a modest dividend increase of 3%, reflecting their strategic focus on sustainable returns amidst market challenges.
- Navigate through the intricacies of Target Healthcare REIT with our comprehensive valuation report here.
Gain insights into Target Healthcare REIT's past trends and performance with our Past report.
Hanza (OM:HANZA)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Hanza is a manufacturing solutions provider that focuses on delivering comprehensive services across various markets, with a market capitalization of approximately SEK 2.4 billion.
Operations: The company generates significant revenue from its Main Markets and Other Markets, with a notable gross profit margin of 44.98% at the end of 2025. Operating expenses are substantial, primarily driven by General & Administrative Expenses, which reached SEK 2.91 billion in mid-2026. The net income margin has shown variability over time but was recorded at 4.55% in early 2026.
PE: 29.4x
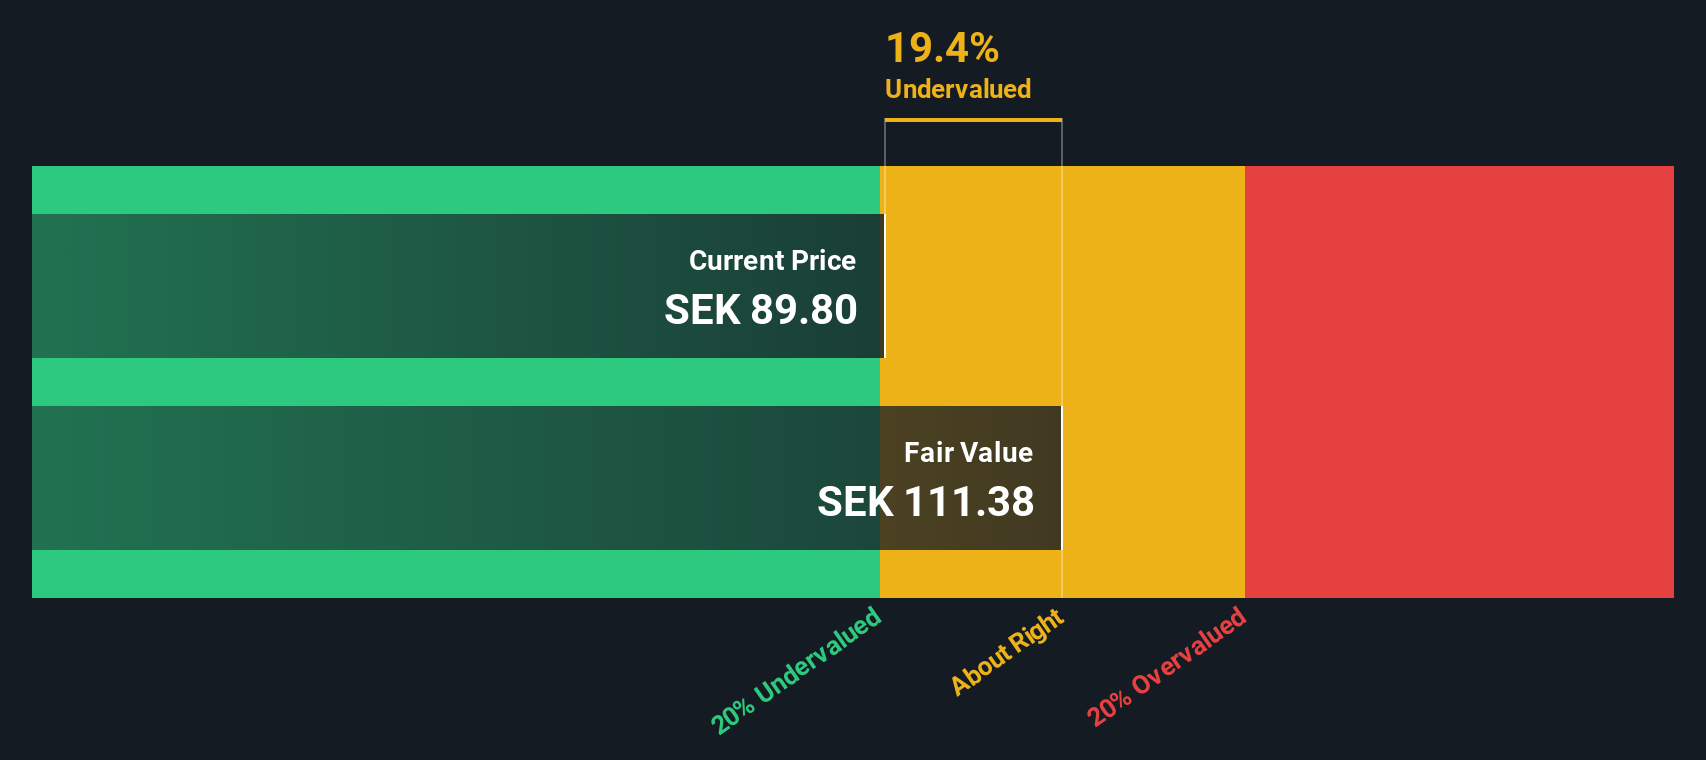
Hanza, a European company with a market cap under €1 billion, is catching attention for its growth potential. Despite relying on external borrowing, the company has seen insider confidence through share purchases this year. Recently, it launched a share repurchase program in July 2026 to optimize capital structure and support acquisitions. With earnings projected to grow at 32.68% annually, Hanza presents an intriguing opportunity for investors seeking growth in smaller market players.
- Click here to discover the nuances of Hanza with our detailed analytical valuation report.
Examine Hanza's past performance report to understand how it has performed in the past.
Summing It All Up
- Access the full spectrum of 29 Undervalued European Small Caps With Insider Buying by clicking on this link.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com