


3 UK Consumer Staples Stocks With Pricing Power As Inflation Squeezes Shoppers
UK shoppers are being squeezed by steeper shelf prices, rising energy bills and higher interest rates, yet some large consumer staples stocks may quietly benefit from these pressures while others face harder choices on pricing and volumes. If you care about protecting your capital when confidence is fragile, this is where attention often shifts first. This article walks through three UK Large-Cap Defensive Consumer Staples stocks exposed to these inflation and rate moves, and explains how the same backdrop can create both potential shelter and fresh risks for your portfolio.
The three stocks covered next are just a sample from this idea. The full screen on Simply Wall St surfaced 11 more large-cap UK consumer staples companies with equally interesting stories that are not included below.
To go deeper on this theme, head straight into the UK Large-Cap Defensive Consumer Staples screener to identify, filter, and analyze the highest-conviction defensive consumer staples opportunities that fit your own criteria.
Reckitt Benckiser Group (LSE:RKT)
Overview: Reckitt Benckiser Group sells everyday health, hygiene and nutrition products like Dettol, Lysol, Durex and Enfamil across global consumer markets.
Operations: Reckitt Benckiser Group generates revenue mainly from Core Reckitt Emerging Markets (£4.4b), Europe (£3.4b), North America (£2.5b) and Mead Johnson Nutrition (£2.1b).
Market Cap: £34.8b
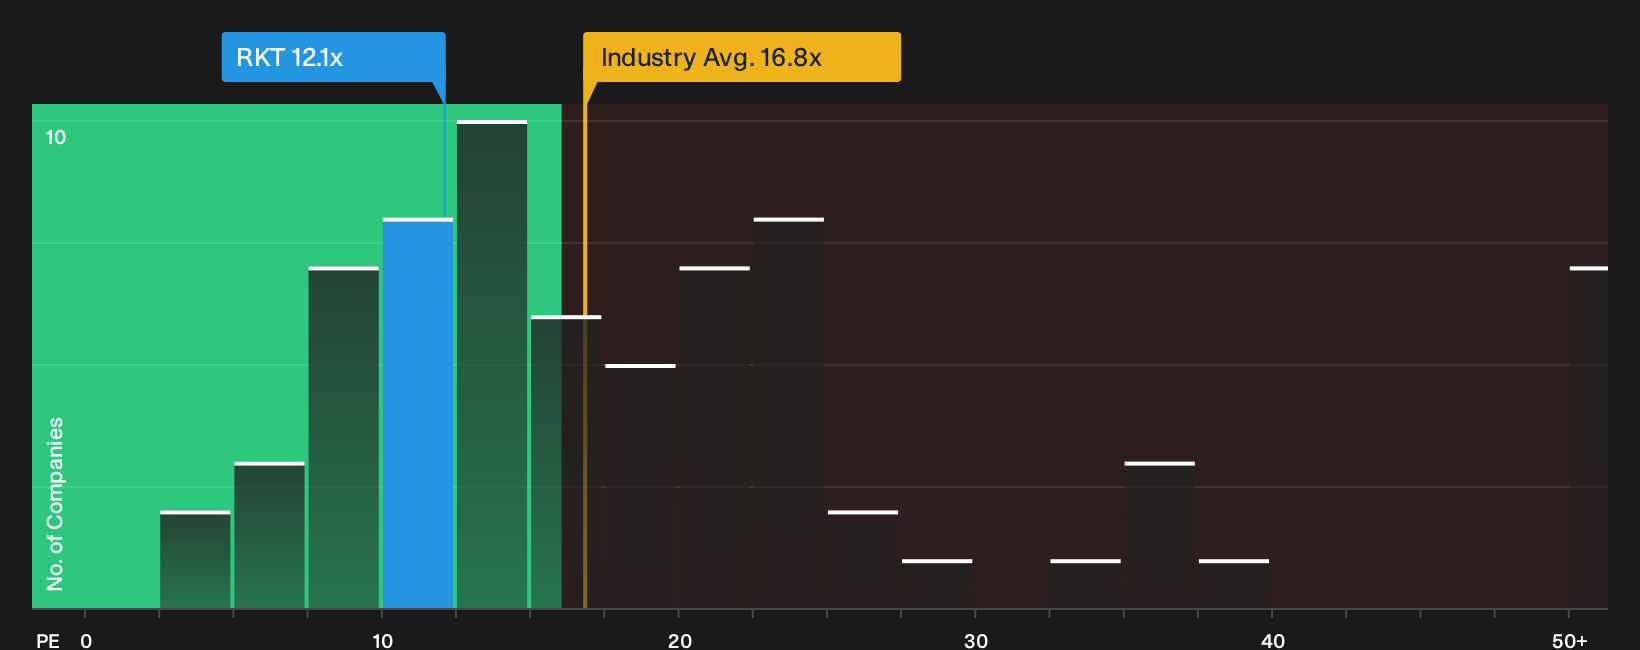
Reckitt Benckiser Group gives you classic defensive staples exposure, with essential hygiene, health and baby nutrition brands that shoppers tend to prioritise even as UK inflation, energy costs and interest rates climb. The stock offers a 3.87% dividend yield and trades on 12.1x P/E, which puts extra focus on how one unseen pressure shapes future pricing power and margins.
That quiet pressure on pricing power makes it worth reviewing the 4 key rewards and 3 important warning signs (1 is major!) to see what might be masking future resilience or strain.
Unilever (LSE:ULVR)
Overview: Unilever is a large UK-based consumer goods group that sells everyday food, home cleaning, beauty and personal care brands worldwide.
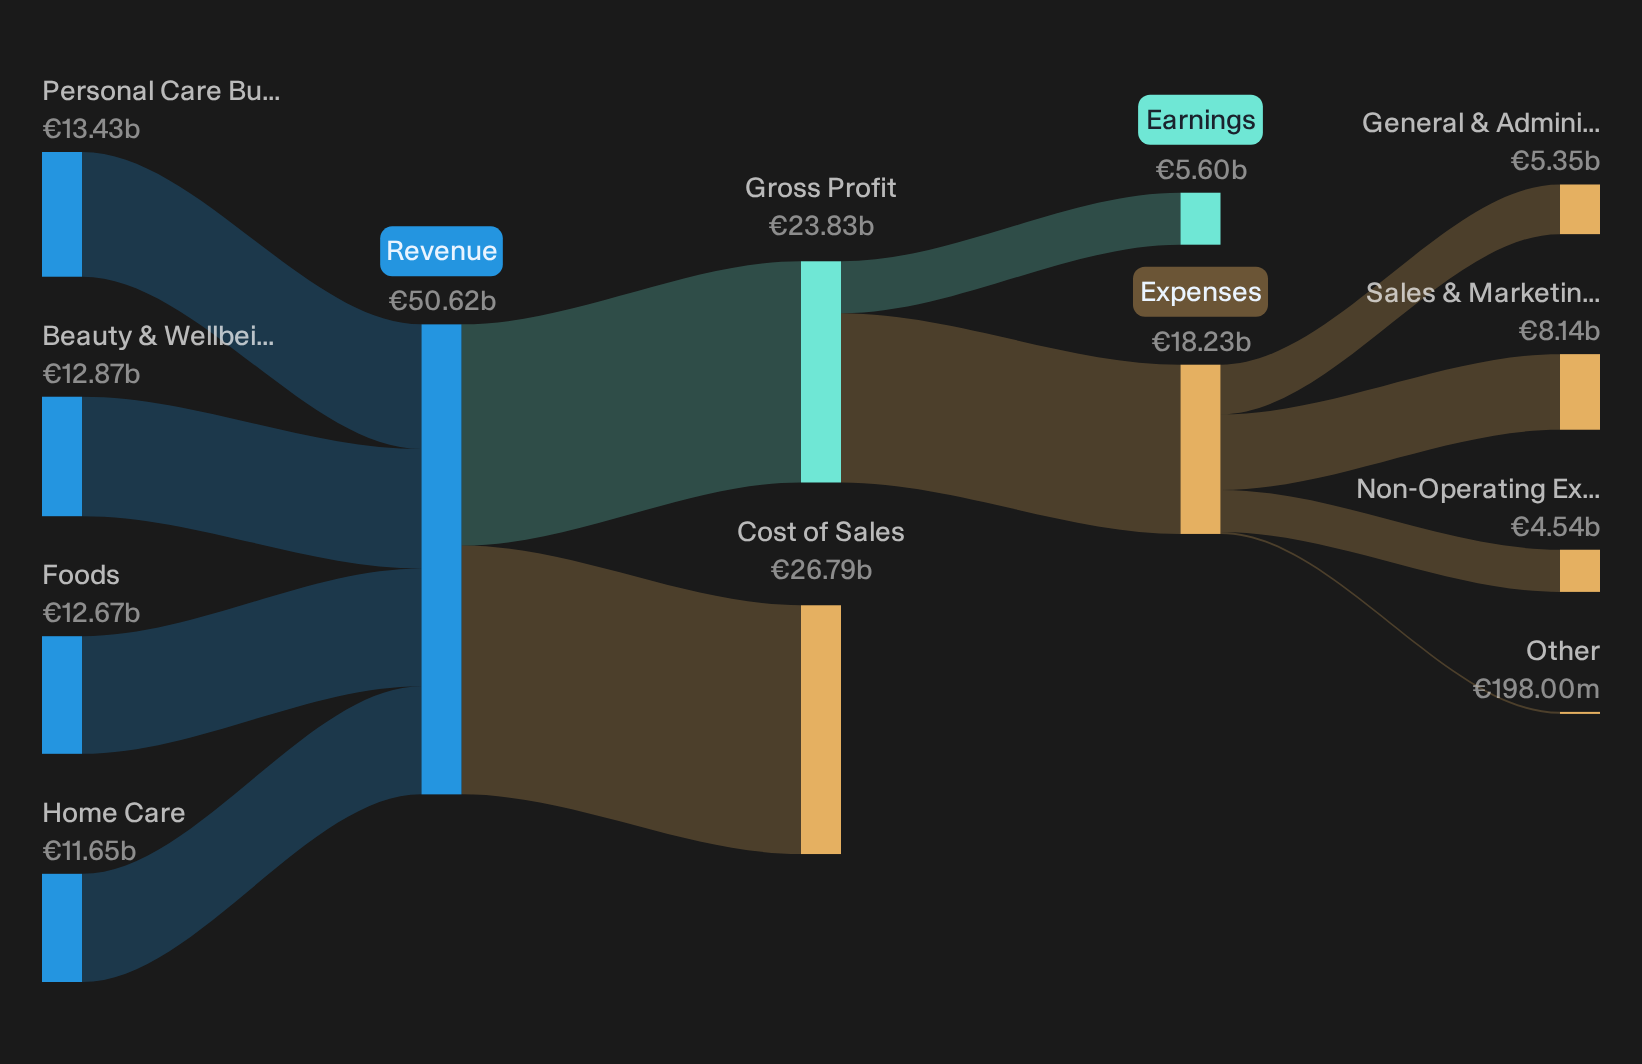
Operations: Unilever earns €12.7b from Foods, €11.7b from Home Care, €12.9b from Beauty & Wellbeing and €13.4b from Personal Care.
Market Cap: £106.0b
Unilever sits in the sweet spot of this defensive staples screen, giving you broad exposure to food cupboards, bathroom shelves and cleaning cupboards at a time when UK inflation and higher rates are putting steady, repeat-purchase brands in focus.
"Acceleration of volume growth in key emerging markets, with Unilever now deriving about 62% of revenue from these regions and reporting 8.3% underlying sales growth with 7.4% from volume led by India, can continue to support top line revenue expansion and scale benefits for earnings."
What really matters next is how one unresolved pressure on its cost base and pricing power shapes that earnings story from here.
That pressure point makes the full narrative for Unilever the place to see whether pricing power, mix and costs are quietly accelerating or masking bigger risks ahead.
PZ Cussons (LSE:PZC)
Overview: PZ Cussons sells baby, beauty and hygiene brands across the UK, Europe, Africa and Asia Pacific, focused on everyday household essentials.
Operations: PZ Cussons generates revenue mainly from Europe & The Americas (£202 million), Asia Pacific (£176 million) and Africa (£168 million).
Market Cap: £403 million
PZ Cussons fits this defensive consumer staples theme through its everyday baby, beauty and hygiene labels. Investors are watching how that essentials focus converts into pricing power as household budgets tighten and costs rise.
"Accelerating e-commerce and digital engagement in Indonesia and other core markets, including live streaming and platform partnerships, is expected to support sustained volume growth and premiumisation in baby and personal care, which in turn may lift group revenue and gross margin over time."
Everything now hinges on how one pressure on profitability interacts with that growth push to shape margins and cash generation.
That hinge point is exactly where the full narrative for PZ Cussons digs in, separating accelerating digital upside from the risks that could quietly cap PZ Cussons' next phase.

Seeking Alternatives Before The Crowd?
Fresh breakouts, momentum shifts and dropping valuations rarely stay under the radar for long. Scan these curated ideas early to review them before they become more widely followed.
- Identify resilient cash generators and evaluate potential downside by running the list of solid balance sheet and fundamentals (10 results) so you can consider balance sheets and fundamentals while there is still time to act decisively.
- Review potential income opportunities by checking the 5 dividend fortresses while payout strength, coverage and price entry points may still be attractive for income focused portfolios.
- Explore fast moving AI developments by scanning the 39 profitable AI stocks that aren't just burning cash while these cash producing growth stories may still be gaining momentum outside the market spotlight.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com