


Gildan Activewear (TSX:GIL) Stock Looks About Right As Debt Paydown Begins
Gildan Activewear has seen its share price fall sharply this year, even though holders over the past three years are still sitting on a strong gain. That mix of recent weakness and longer term strength puts a spotlight on one question for investors who follow Gildan Activewear: whether the current share price around earnings is still sensible.
- The stock has gained 54.1% over the past three years, which puts real weight on whether that move is properly supported by the profit the business is generating.
- The completed sale of HanesBrands Australia for about A$700 million, with proceeds earmarked to repay debt, can reshape the balance sheet and may support flexibility in how future earnings are used.
- Your read on Gildan Activewear is one view; the desks covering it have another. See what analysts think Gildan Activewear's shares could be worth.
The issue now is whether Gildan Activewear's current price is justified by its earnings when you set it against the Fair Ratio benchmark.
If you are weighing whether Gildan Activewear's current valuation makes sense in light of its recent share price swings and the HanesBrands Australia sale, it can help to compare that story with companies filtered through 3 high quality undervalued stocks.
Where Does Gildan Activewear Sit on Earnings?
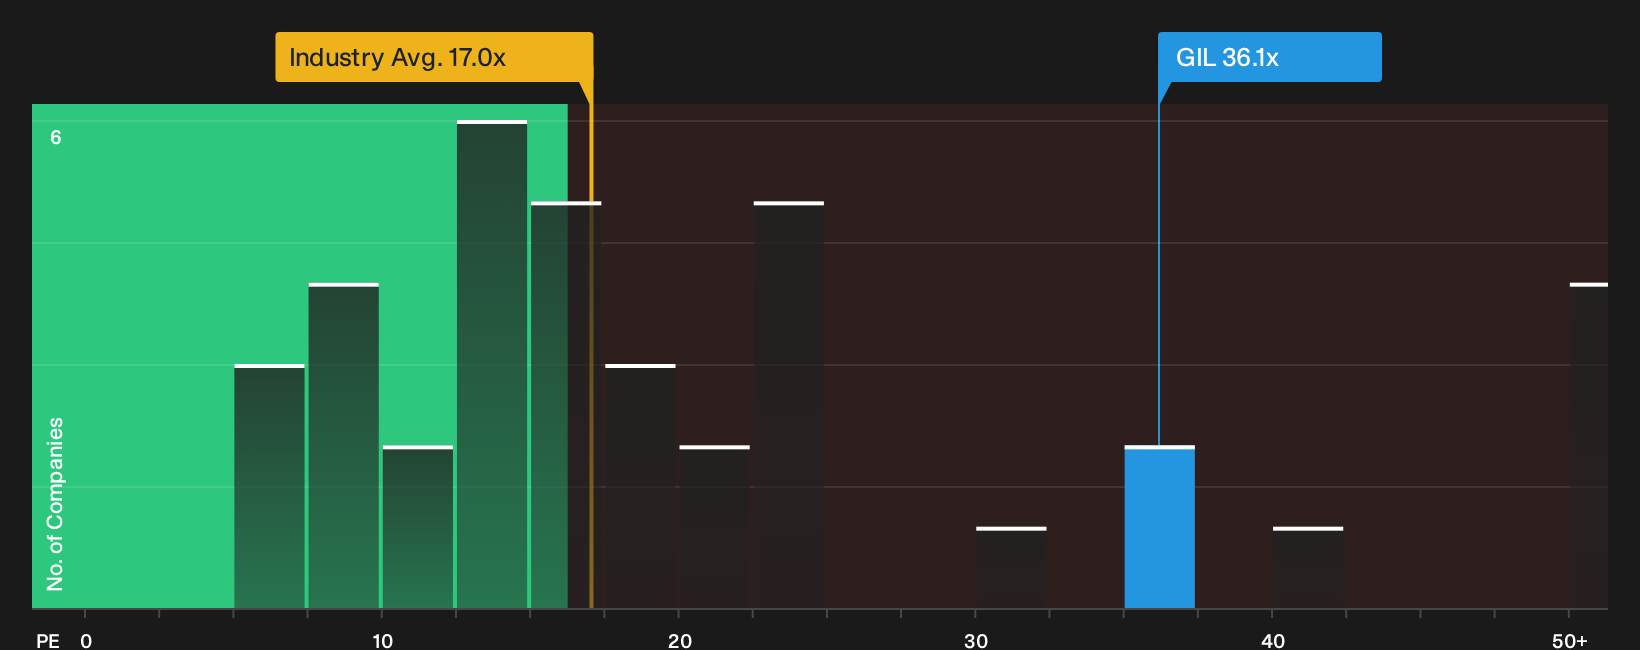
The P/E ratio suits Gildan Activewear because earnings remain a core reference point for how investors judge a branded apparel group. On that metric, the stock trades on about 36.1x earnings, which is higher than the Luxury industry average of roughly 15.3x but slightly above peers around 30.1x. The Fair Ratio model, which blends the company’s growth outlook, margins, size and risk profile into a tailored valuation yardstick, points to a level that is broadly similar to where the shares trade.
Because the HanesBrands Australia sale directed roughly A$700 million toward debt repayment, the balance sheet picture that underpins Gildan Activewear’s earnings stream has shifted. Yet the current multiple still prices the business in line with what this framework suggests investors might expect to pay for those profits. For anyone following TSX:GIL, the key question is whether the quality, durability and potential of future earnings justify paying a P/E that sits above the sector but not far from the modelled benchmark. Explore the numbers behind Gildan Activewear's P/E valuation.
The Gildan Activewear Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Gildan Activewear leaves off. They spell out which future paths for growth, margins and earnings would need to unfold for the stock to look meaningfully cheaper or more expensive than today’s price on the Community page. Each scenario links its number to a clear view on how Gildan Activewear's growth prospects, profitability and risk profile might evolve, which you can revisit as fresh information comes through.
One of the top community narratives on Gildan Activewear: 48% undervalued
"Gildan's cost-efficient, ethically focused manufacturing and value-oriented products provide strong competitive advantages and support growth amid shifting consumer and regulatory trends..."
Discover why this Narrative puts Gildan Activewear at 48% undervalued.
One More Piece Of The Gildan Activewear Puzzle
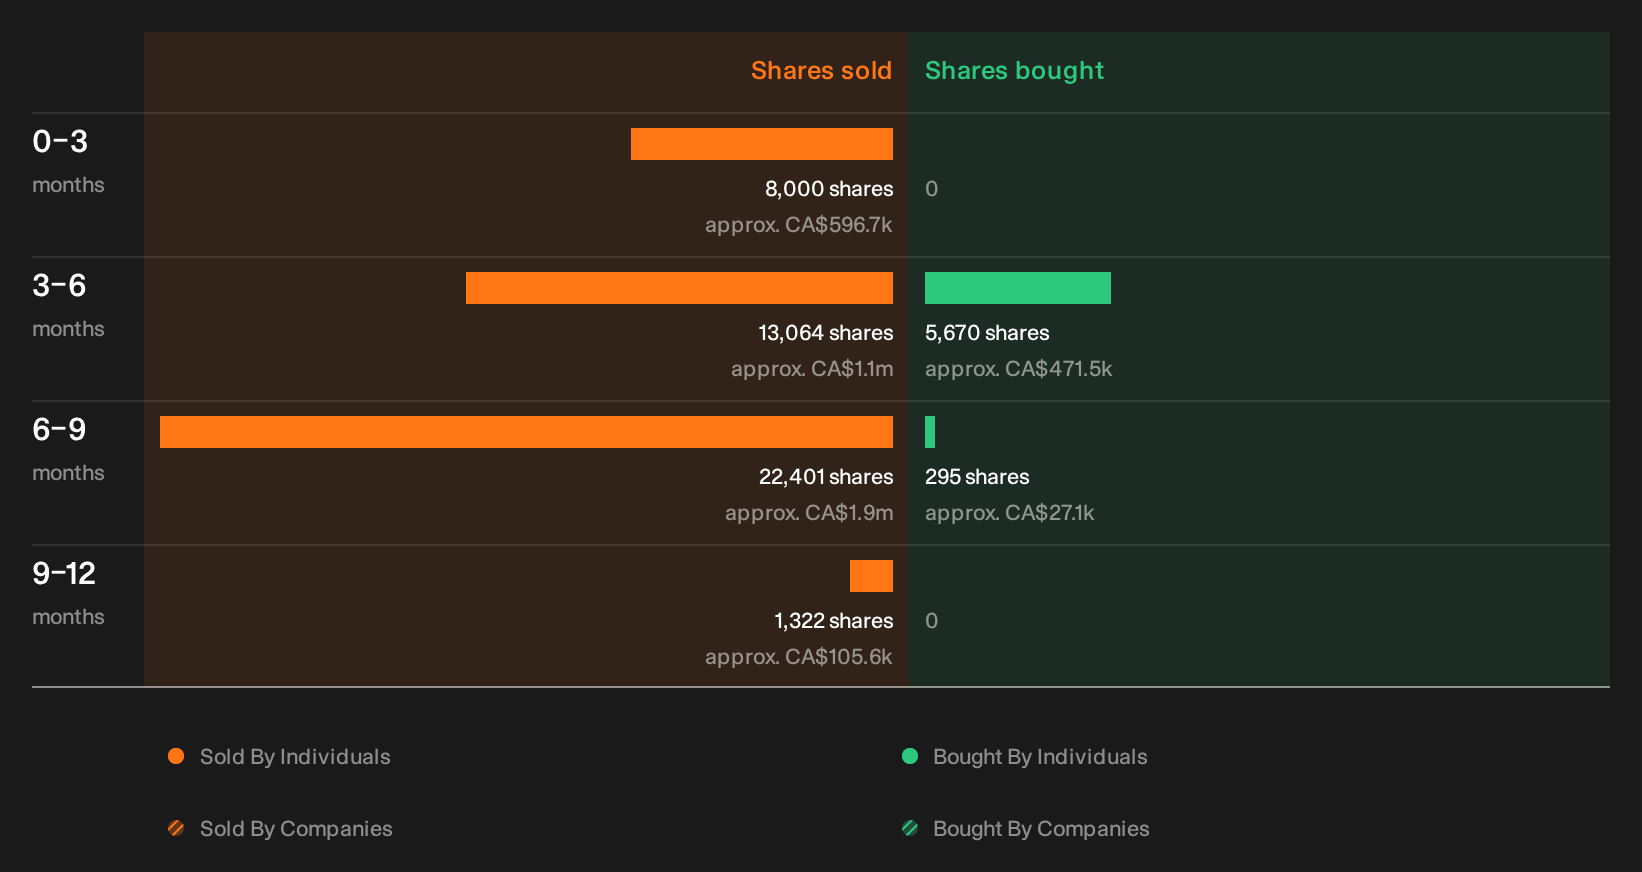
There is one other angle on Gildan Activewear that deserves a closer look, because recent trading by people inside the business has been flagged by our checks and the identities, sizes and possible read throughs are still for you to explore. See the recent insider selling flagged for Gildan Activewear.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com