


How Revenue Declines Will Impact Travis Perkins Stock Investors
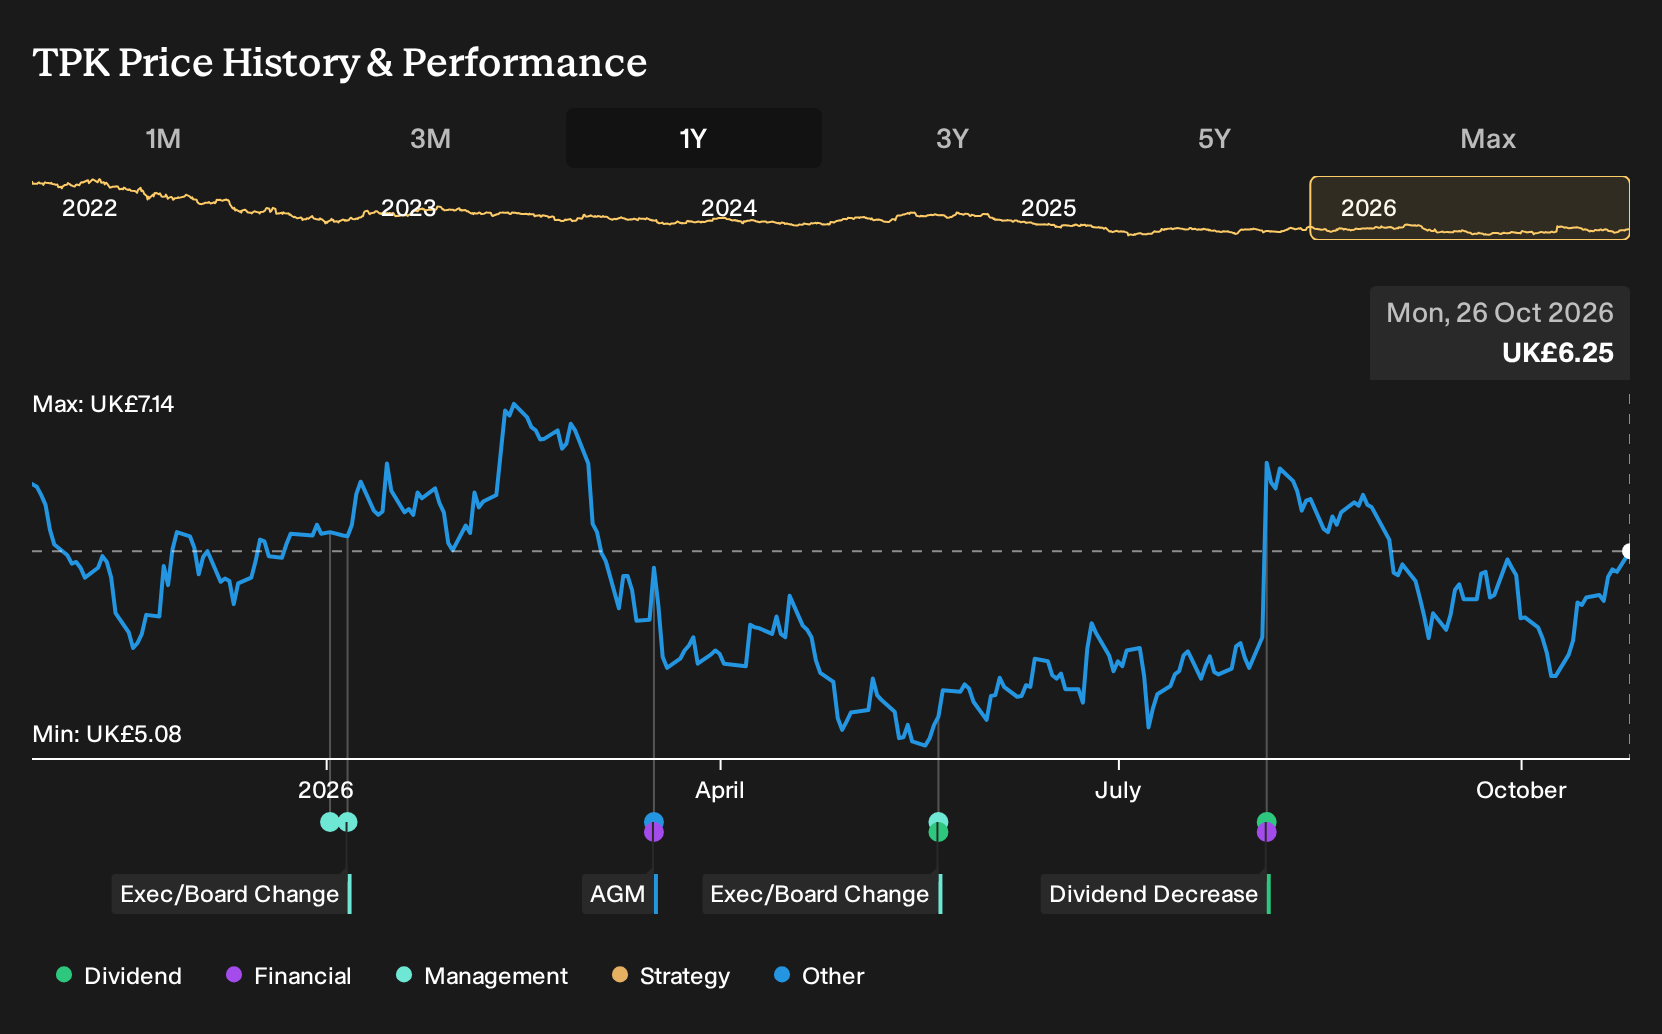
- Travis Perkins reported a 1.6% decline in group revenue for the third quarter and a 1.8% decline for the year to date to 30 September 2026.
- The parallel drop in quarterly and year to date turnover points to broader demand pressure across Travis Perkins' core markets rather than a one off issue.
- This article examines how Travis Perkins' investment narrative is being tested by the recent 1.8% year to date revenue decline outlined in its trading update.
Pressure test how Travis Perkins compares by scanning other construction exposed stocks with resilient balance sheets and steady fundamentals using our curated list of solid balance sheet and fundamentals (10 results).
Travis Perkins Investment Narrative Recap
To own Travis Perkins, you need to be comfortable with a merchant that is still working through weak UK construction volumes, pressure on pricing, and recent operational disruption. The 1.8% year to date revenue decline suggests demand is not helping much. For now, the key near term catalyst remains evidence that volumes stabilise without deeper discounting eroding margins further.
The biggest risk sits in a mix of thin pricing power, credit stress among trade customers, and any setbacks in fixing digital and ERP issues. This latest trading update does not radically change that picture. It simply reinforces that the recovery case still depends on execution in a flat market.
The most relevant recent development is the trading statement itself. It gives you a clear view of how Travis Perkins is tracking against its own reset expectations, with both the quarter and year to date showing low single digit revenue declines. That keeps the focus squarely on whether the merchanting turnaround and ERP clean up can offset softer volumes.
For catalysts, you are essentially watching for quarterly updates that show steadier turnover, better service levels and fewer operational hiccups flowing from the Oracle system. If those operational fixes take hold while bad debts and credit provisions remain contained, the business case looks more robust. If not, the revenue pressure seen in this update could start to feed more obviously into profit risk.
Travis Perkins' narrative projects £5.0b revenue and £98.7 million earnings by 2029. This is based on an assumed 2.8% yearly revenue growth and an earnings swing of about £275 million from a loss of £176.3 million today.
Uncover why Travis Perkins' fair value indicates a 5% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on Travis Perkins focuses on weak builders’ merchant volumes and nearly 4,000 UK construction insolvencies in the year to April 2026. The most bearish analysts were already pencilling in roughly £4.8b of 2029 revenue and £132.6 million of earnings. That is a much tougher story. These views came before this trading statement, so opinions and models may change as fresh data is published.
Explore another Travis Perkins fair value estimate, including one that suggests as much as 71% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Travis Perkins research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Travis Perkins. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Travis Perkins' overall financial health at a glance.
Looking for more investment ideas beyond Travis Perkins?
Once you have formed a view on Travis Perkins, it can help to compare that thesis with other opportunities using the Simply Wall St Screener.
- If you want potential upside anchored in both quality and value, take a look at 10 high quality undervalued stocks that already combine stronger fundamentals with more appealing pricing.
- For readers who care most about resilience through cycles, scan a 4 resilient stocks with low risk scores that aim to keep downside risk in tighter check.
- If you prefer to focus on income, sort through a 5 dividend fortresses that offer higher yields while still passing core financial health checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com