


Ero Copper (TSX:ERO) Reached Commercial Production, Is The Valuation Gap Still Real?
Ero Copper (TSX:ERO) just hit commercial production at its Tucumã Operation, while cutting net debt leverage and reporting a 70% revenue jump. Investors now have fresh numbers to assess this miner’s growth projects.
Ero Copper’s share price has pulled back recently, with a 7 day share price return of down 10.0% and a 30 day share price return of down 18.3%. However, the 90 day share price return is up 20.9% and the 1 year total shareholder return is 52.2%, which points to longer term momentum while near term sentiment resets after the Tucumã and Furnas updates.
Spot similar copper and materials stories that may be setting up the next leg of this move by scanning our hand picked 16 top copper producer stocks.Bulls view Ero Copper as a cash generative copper producer with fresh projects online, while bears focus on the recent pullback and execution risk. Which narrative does the current valuation actually support?
Most Popular Narrative: 20% Undervalued
Ero Copper last closed at CA$43.72, while the most followed narrative pegs fair value at CA$54.52, implying a wide valuation gap that hinges on execution at its Brazilian assets and future free cash flow.
The ramp-up of higher-grade and lower-cost sources (notably Surubim's open-pit and Xavantina's newly mechanized stopes), combined with ongoing modernization at Pilar and strong balance sheet deleveraging, create a foundation for both near
and medium-term earnings accretion and free cash flow growth.
See why 34 investors see Ero Copper as 20% undervalued.
Analysts behind this narrative use an 8.22% discount rate and assume revenue growth of 8.4% a year, with profit margins moving from 29.8% to 32.5%. They also factor in earnings rising from US$311.3 million to US$433.6 million by around 2029, and a future P/E of 11.8x that sits below the 15.4x level cited for the wider Canadian metals and mining group.
To line up with that view, you would need to be comfortable that Ero Copper can keep lifting free cash flow from projects like Tucumã, Caraíba and Xavantina, while managing Brazil specific risks and potential cost pressure. You would also need to accept the possibility that the stock might move closer to the narrative fair value of CA$54.52 if those operational and earnings assumptions hold.
Result: Fair Value of CA$54.52 (UNDERVALUED)
Still, if Ero Copper again falls short on production guidance or Brazil specific risks flare up around taxes or regulation, this upbeat narrative could unwind quickly.
Find out about the key risks to this Ero Copper narrative.
Another View: DCF Flags Ero Copper As Overvalued
Ero Copper screens as inexpensive on analyst targets and P/E work, yet the SWS DCF model points in the opposite direction. At CA$43.72, the share price sits well above an estimated future cash flow value of CA$22.28, which frames the stock as overvalued on this approach.
This gap reflects a simple trade off. Analysts and earnings based models lean on profit strength and return on equity. The DCF view, by contrast, asks whether the current price already bakes in generous long term cash generation. Which lens feels closer to how you think about risk and reward?
Look into how the SWS DCF model arrives at its fair value.
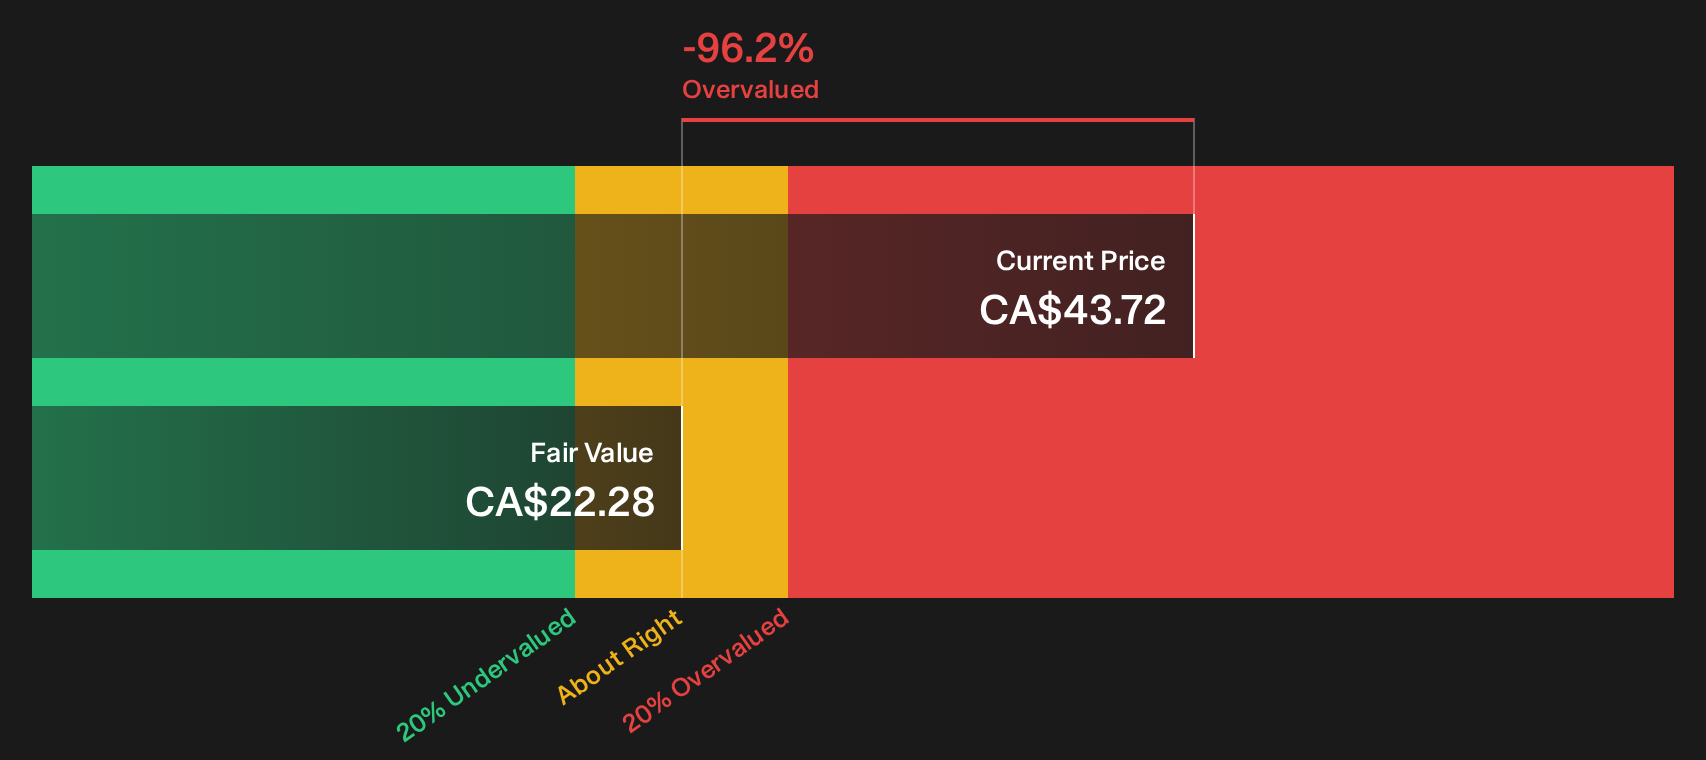
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ero Copper for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages or early opportunity? If the crosscurrents around Ero Copper interest you, move fast, review the underlying numbers and weigh up the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Ero Copper?
If Ero Copper has your attention, do not stop there. Broader idea hunting can help you refine your risk and return trade offs across a full portfolio.
- Target potential bargains with strong fundamentals by scanning our hand picked 3 high quality undervalued stocks.
- Build a steadier income stream by reviewing companies in the 3 dividend fortresses.
- Protect your downside first by focusing on resilient candidates screened through the 8 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com