


Vossloh (XTRA:VOS) Reaffirms 2026 Guidance After Margin Pressure But Still Looks Undervalued
Vossloh (XTRA:VOS) is back in focus after confirming its 2026 guidance, pairing a mid-range sales outlook with EBIT expected near the lower end and softer nine-month profitability.
The reaffirmed outlook comes amid a weak trading pattern. Vossloh’s share price has fallen 36.83% year to date and is down 16.31% over 90 days. However, the 3 year total shareholder return of 39.83% hints at longer term resilience despite the recent loss of momentum.
Scan how rail-linked cyclicals like Vossloh compare with other infrastructure plays facing similar margin pressure through our curated list of 42 power grid technology and infrastructure stocks today.
Vossloh’s slump now sits against reaffirmed guidance and softer margins. Is the share price reacting to a weaker earnings quality story, or has sentiment swung harder than the underlying business justifies as you weigh the current valuation?
DCF Value Gap On Vossloh: What The Market Is Pricing In
On Simply Wall St’s SWS DCF model, Vossloh’s estimated future cash flow value sits at €101.76 per share, compared with a last close of €49.46. That implies the current market price is sitting well below this internal fair value estimate.
The discounted cash flow approach projects the company’s expected cash generation into future years, then discounts those streams back into today’s money using a required rate of return. It aims to translate the long-term cash profile of the rail infrastructure specialist into a single present-day figure, rather than relying on short term earnings snapshots.
For a business like Vossloh, with rail infrastructure exposure, mixed recent profitability and a forecast earnings profile that analysts expect to shift, a DCF framework can highlight how much of the long-term cash story is already embedded in the quote. The gap between the €101.76 model value and the €49.46 share price indicates how much of that potential cash generation the current market is choosing not to reflect today.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of €101.76 (UNDERVALUED)
Still, the weak 1 year shareholder return and softer recent profitability leave Vossloh exposed if rail project timing or margin pressure worsen from this point.
Find out about the key risks to this Vossloh narrative.
Another View On Vossloh’s Valuation: Earnings Multiple Sends A Different Signal
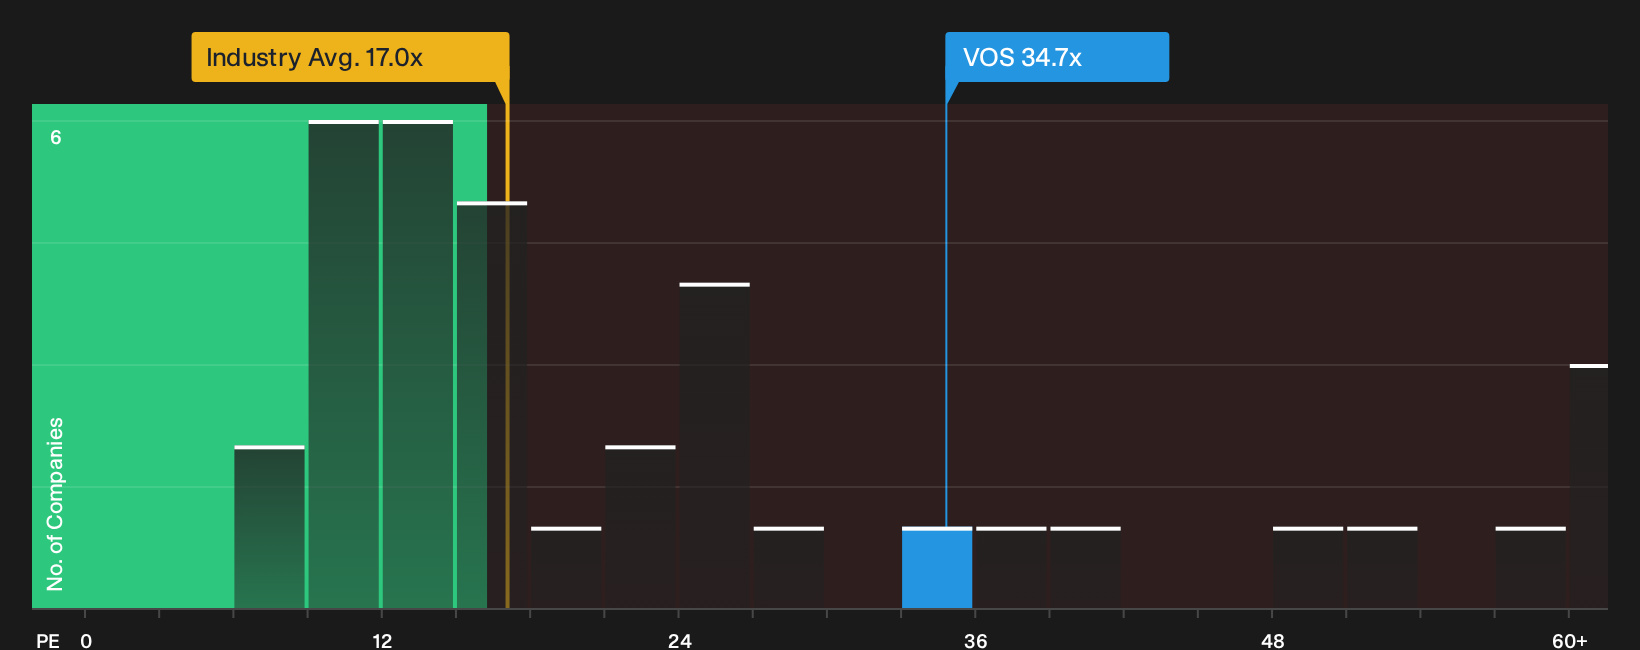
DCF paints Vossloh as attractively priced, yet the earnings multiple tells a more demanding story. The stock trades on a P/E of 34.7x, which is roughly double the German Machinery sector at 17x and in line with a fair ratio of 34.7x. That combination points to limited margin for error if profitability stumbles again. How comfortable are you paying a full earnings price while the share price and margins are both under pressure?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Vossloh for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Vossloh is clearly split, with weaker recent returns facing off against a richer valuation and long-term potential. Act while the facts are fresh and weigh the balance of 2 key rewards and 3 important warning signs
Looking For More Investment Ideas Beyond Vossloh?
If Vossloh has you rethinking where the best risk and reward mix sits, do not stop here. Use the Simply Wall St screener to compare other ideas side by side and avoid missing opportunities hiding in plain sight.
- Target robust value opportunities by scanning a curated 195 high quality undervalued stocks that pair quality fundamentals with prices that lag behind their implied worth.
- Prioritise resilience and sleep-better-at-night potential by checking a 223 resilient stocks with low risk scores filtered for steadier balance sheets and lower risk profiles.
- Hunt for tomorrow's potential standouts before they gain wider attention through a 610 high quality undiscovered gems focused on under-followed businesses with solid financial underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com