


DXP Enterprises Stock Looks Undervalued As Water Expansion Reaches Canada
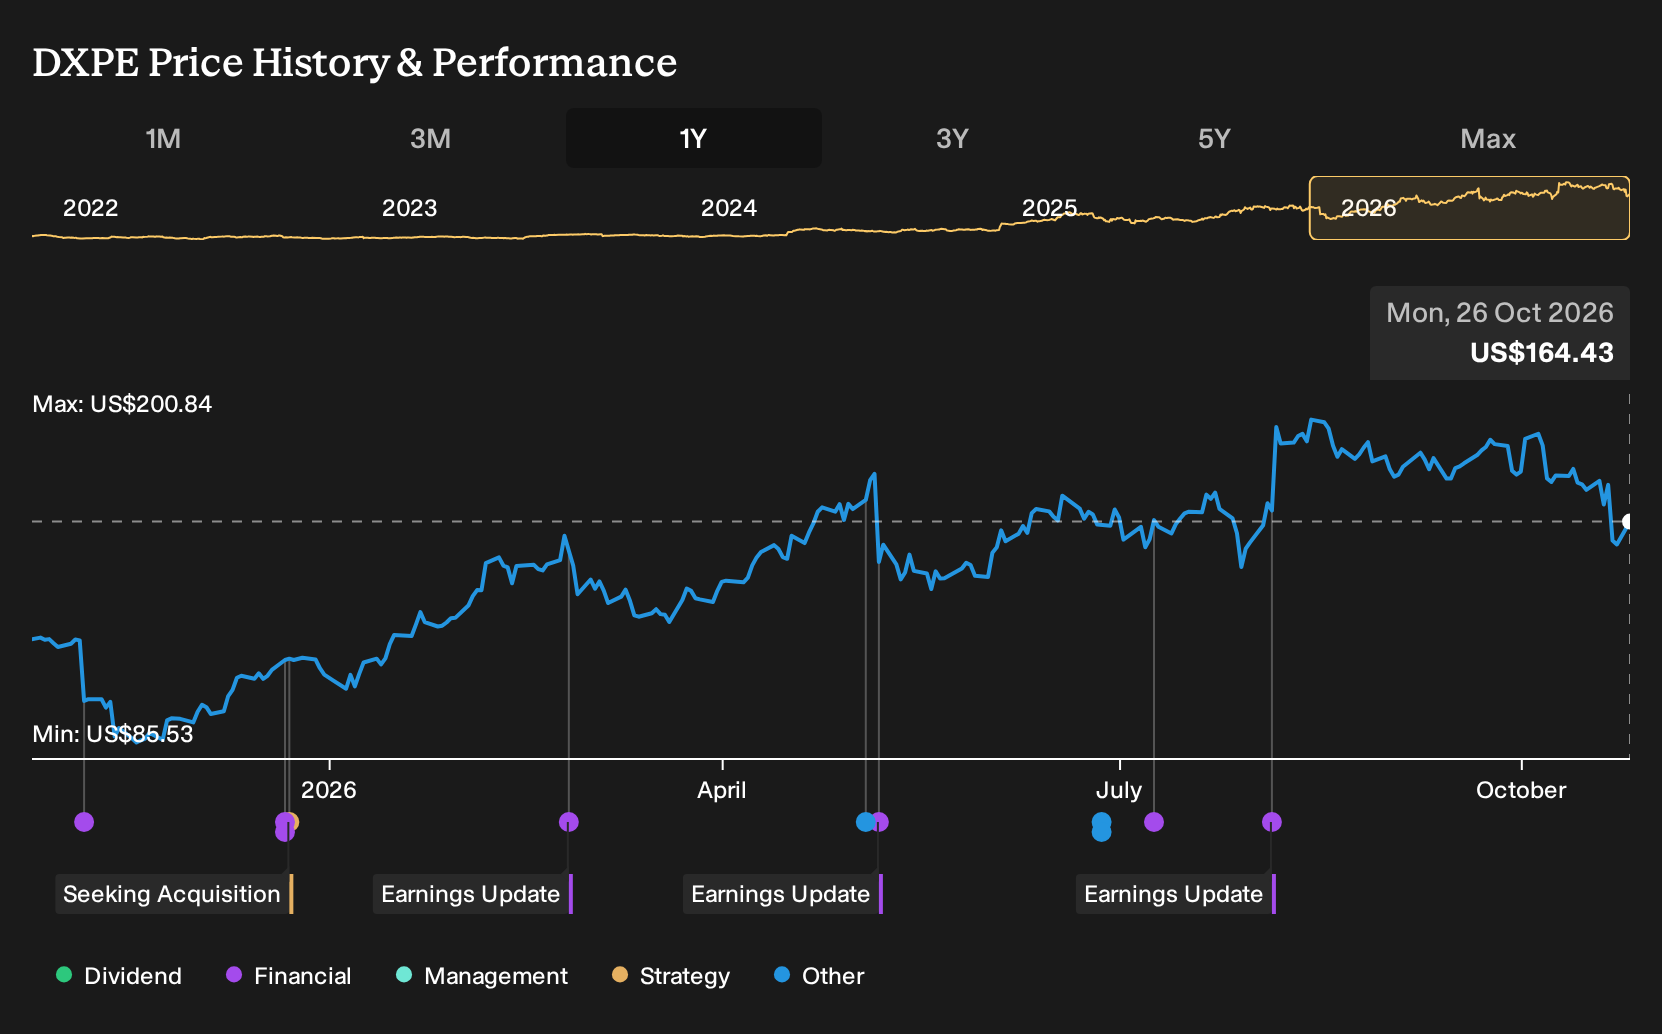
- DXP Enterprises has delivered a very large 3 year return of 391.1%, while a recent DCF review suggests its cash generation could support a valuation roughly 20% above the current market level, against a backdrop of expansion in its water and wastewater operations into Canada.
- The push into higher-value water and wastewater projects through acquisitions, including entry into the Canadian market, points to a growing role for regulated, long-cycle infrastructure work in DXP Enterprises' mix. This could matter for how resilient its cash flows appear to investors weighing that DCF view.
- We will now see how DXP Enterprises' push into water and wastewater, including Canadian acquisitions, could shape its broader investment narrative.
Scan for other infrastructure heavyweights with resilient cash flows by comparing the profile of DXP Enterprises to our hand picked list of solid balance sheet and fundamentals (24 results)
DXP Enterprises Investment Narrative Recap
To own DXP Enterprises, you need to believe the shift toward higher value engineered solutions and water and wastewater work can sustain its earnings power while the balance sheet remains manageable. The recent DCF work, which points to a valuation gap, mainly sharpens focus on execution rather than changing the core story.
For the near term, the key catalyst is whether operations continue to support consistent free cash flow that can cover US$842.5m of debt and fund acquisitions without stretching leverage. The biggest risk is a softer patch in cash generation or earnings that would make that debt load feel heavier and limit flexibility.
One of the most relevant developments for this narrative is the expansion of DXP Enterprises’ water and wastewater platform into Canada through acquisitions. That move increases exposure to regulated, long duration infrastructure projects, which can influence how stable investors perceive future cash flows to be.
This Canadian push also ties directly into the catalyst investors are watching. If these acquired operations integrate cleanly and contribute to DXP Water, already a large part of IPS, they could support the higher margin mix that underpins the recent DCF work. If integration stumbles or projects underperform, it would add execution risk on top of the existing leverage.
DXP Enterprises' current analyst narrative points to revenues of US$2.7b and earnings of US$174.7m by 2029, based on a forecast 8.7% yearly increase in revenue and a move from US$93.1m of earnings today to that 2029 consensus, which represents roughly an 88% uplift in profit.
Uncover why DXP Enterprises' fair value indicates a 22% potential upside to its current price before the window for that discount closes.
Exploring Other Perspectives
The Simply Wall St Community currently includes only 2 fair value estimates for DXP Enterprises, clustered tightly between about US$196.47 and US$200. That narrow band contrasts with earlier commentary pointing to premium pricing risks and debt sensitivity. You can use these different angles to stress test your own view.
Explore another DXP Enterprises fair value estimate, including one that suggests it could be worth just $196.47.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your DXP Enterprises research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DXP Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DXP Enterprises' overall financial health at a glance.
Looking for more DXP Enterprises style ideas?
If the DXP Enterprises story has sharpened your thinking about cash flow, balance sheets, and valuation gaps, you can apply the same lens to a wider watchlist using the Simply Wall St Screener.
- For investors who want quality at a discount, scan a focused set of opportunities through our 29 high quality undervalued stocks and see which businesses line up with your return and risk expectations.
- If preserving capital matters just as much as growing it, filter for companies with steadier profiles using a 30 resilient stocks with low risk scores that surfaces businesses with lower overall risk scores.
- When you are hunting for potential future leaders before they become widely followed, sort through a 21 high quality undiscovered gems that highlights under-the-radar stocks with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com