


ComfortDelGro (SGX:C52) Is Getting Fresh Attention, What Is Behind It?
Fresh board line up reshapes ComfortDelGro’s governance story
ComfortDelGro (SGX:C52) has drawn fresh attention after announcing Deputy Chairman Choi Shing Kwok’s planned retirement and the upcoming appointments of transport veteran Chew Hock Yong and audit specialist Ang Fung Fung.
ComfortDelGro’s share price has softened recently, with the 90 day share price return down 4.51% and the year to date share price return down 14.19%. However, the 3 year total shareholder return of 13.63% points to a more resilient longer term record, so the latest governance refresh is landing against a period of fading momentum and a market reassessing both its risks and potential.
Compare ComfortDelGro’s governance refresh with other businesses that score well on balance sheet strength and fundamentals by scanning our curated list of solid balance sheet and fundamentals (207 results).
ComfortDelGro’s share price has slipped while its board is being rebuilt in real time, so the tension now is simple: step in at today’s level or wait and see if the valuation offers a clearer entry point.
Price-to-Earnings of 13.1x: Is it justified for ComfortDelGro?
On simple valuation terms, ComfortDelGro trades on a P/E of 13.1x, which puts the share price at SGD1.27 in territory that looks cheaper than close peers but slightly richer than the wider Asian transportation group.
P/E compares what investors pay today with the earnings each share currently generates. For a transport operator like ComfortDelGro, this ratio is often used as a shorthand for what the market is willing to pay for its mix of mature cash generating routes, regulated contracts and ancillary inspection and testing income.
The stock changes hands at a discount to a peer average P/E of 16.7x, which suggests investors are currently assigning a lower price tag to ComfortDelGro’s earnings than to similar sized rivals. At the same time, the same 13.1x multiple sits above the Asian transportation industry average of 12.3x, so the market is still accepting a small premium compared to the broader sector. The estimated fair P/E of 14.2x is higher than where the shares currently trade, which signals room for the valuation multiple to move closer to that level if sentiment and fundamentals stay aligned.
Explore the SWS fair ratio for ComfortDelGro.
Result: Price-to-Earnings of 13.1x (UNDERVALUED)
Still, the ComfortDelGro story can change quickly if public transport contracts are repriced on tougher terms or if taxi and PHV demand weakens further.
Find out about the key risks to this ComfortDelGro narrative.
Another view on ComfortDelGro’s value
The SWS DCF model points to a different angle on ComfortDelGro. At SGD1.27, the share price sits below an estimated future cash flow value of SGD1.45, which frames the stock as undervalued on this lens and raises a simple question: Which signal will investors trust more?
Look into how the SWS DCF model arrives at its fair value.
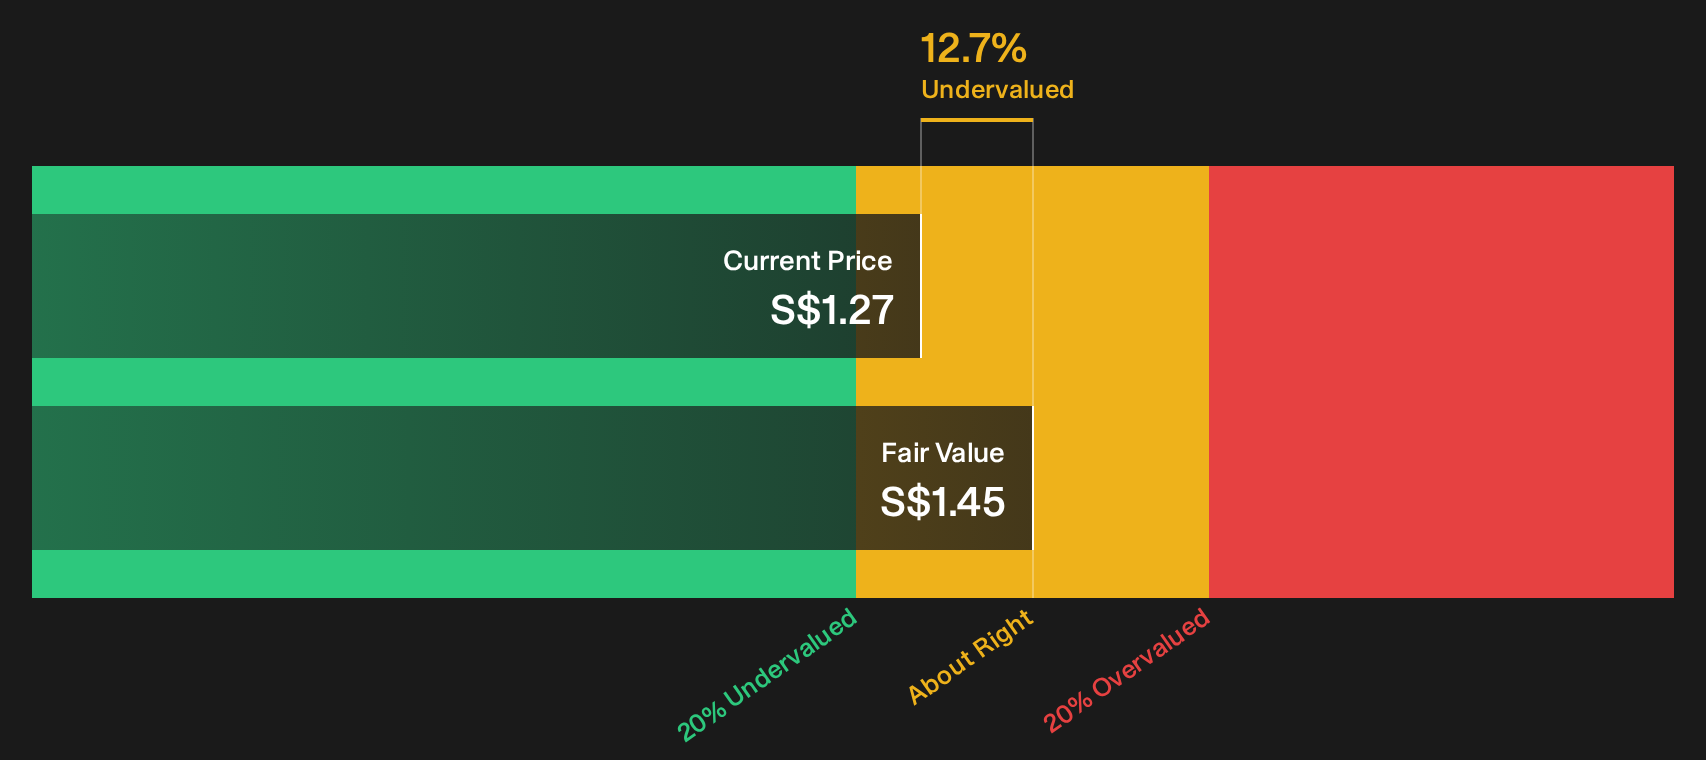
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ComfortDelGro for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the ComfortDelGro story so far. If you want to move quickly and decide for yourself, start by weighing the 2 key rewards and 1 important warning sign
Looking for more ComfortDelGro investment ideas?
Do not stop your research with ComfortDelGro alone. Cast the net wider with a few focused stock lists that can surface opportunities you might otherwise miss.
- Target resilient balance sheets and steady fundamentals by reviewing our curated list of solid balance sheet and fundamentals (207 results).
- Hunt for potential value opportunities that combine quality and pricing appeal through the 194 high quality undervalued stocks.
- Prioritise dependable income streams and assess payout strength using the 224 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com