


European Gas Prices Put Grupa Azoty Stock And Industrial Peers In Focus
European natural gas prices are back in the spotlight, and this time the move is hitting some of the continent’s most energy-hungry manufacturers right where it hurts. When fuel costs jump, a few businesses quietly gain an edge while others see their economics squeezed. This article walks through three European stocks exposed to the latest gas shock, showing where the pressure is building and where potential opportunity may be emerging for your watchlist.
The three stocks covered below are just a sample pulled from this theme, while the full screen surfaced 11 more European industrials with gas exposure that bring similarly detailed stories that are not unpacked in this article. To see the wider opportunity set, head straight into the European Energy-Intensive Industrials Exposed to Natural Gas Costs screener to identify, filter and analyze the energy intensive manufacturers that best fit your own conviction levels.
Grupa Azoty (WSE:ATT)
Grupa Azoty is one of the purest plays on this gas exposed theme, since its fertilizer and chemical complexes rely heavily on natural gas and feed into food and industrial supply chains across Poland and wider export markets.
Grupa Azoty generates most of its PLN 15.0b operating revenue from Agro at roughly PLN 12.3b, with Chemistry contributing about PLN 4.0b, Power Industry PLN 4.7b and Plastics around PLN 1.5b, and the stock carries a market value of roughly PLN 1.8b.
"Although Grupa Azoty has recently reported positive EBITDA supported by EU recognition of fertilizer production as important for food security, persistent volatility in gas and sulfur linked to conflict driven supply disruptions could still squeeze product pricing and raise input costs in a way that weakens future margins and EBITDA."
What happens to future profitability hinges on how one still unresolved pressure on this gas hungry production system ultimately plays out.
That unresolved pressure is exactly why reading the full narrative for Grupa Azoty can help you see how Grupa Azoty’s gas risk could eventually translate into accelerating upside potential.

thyssenkrupp (XTRA:TKA)
Thyssenkrupp plugs straight into the gas exposed theme because its steel and heavy manufacturing footprint leans on energy intensive processes. Yet the real interest for investors is how that legacy profile now intersects with a reshaped portfolio in higher quality areas.
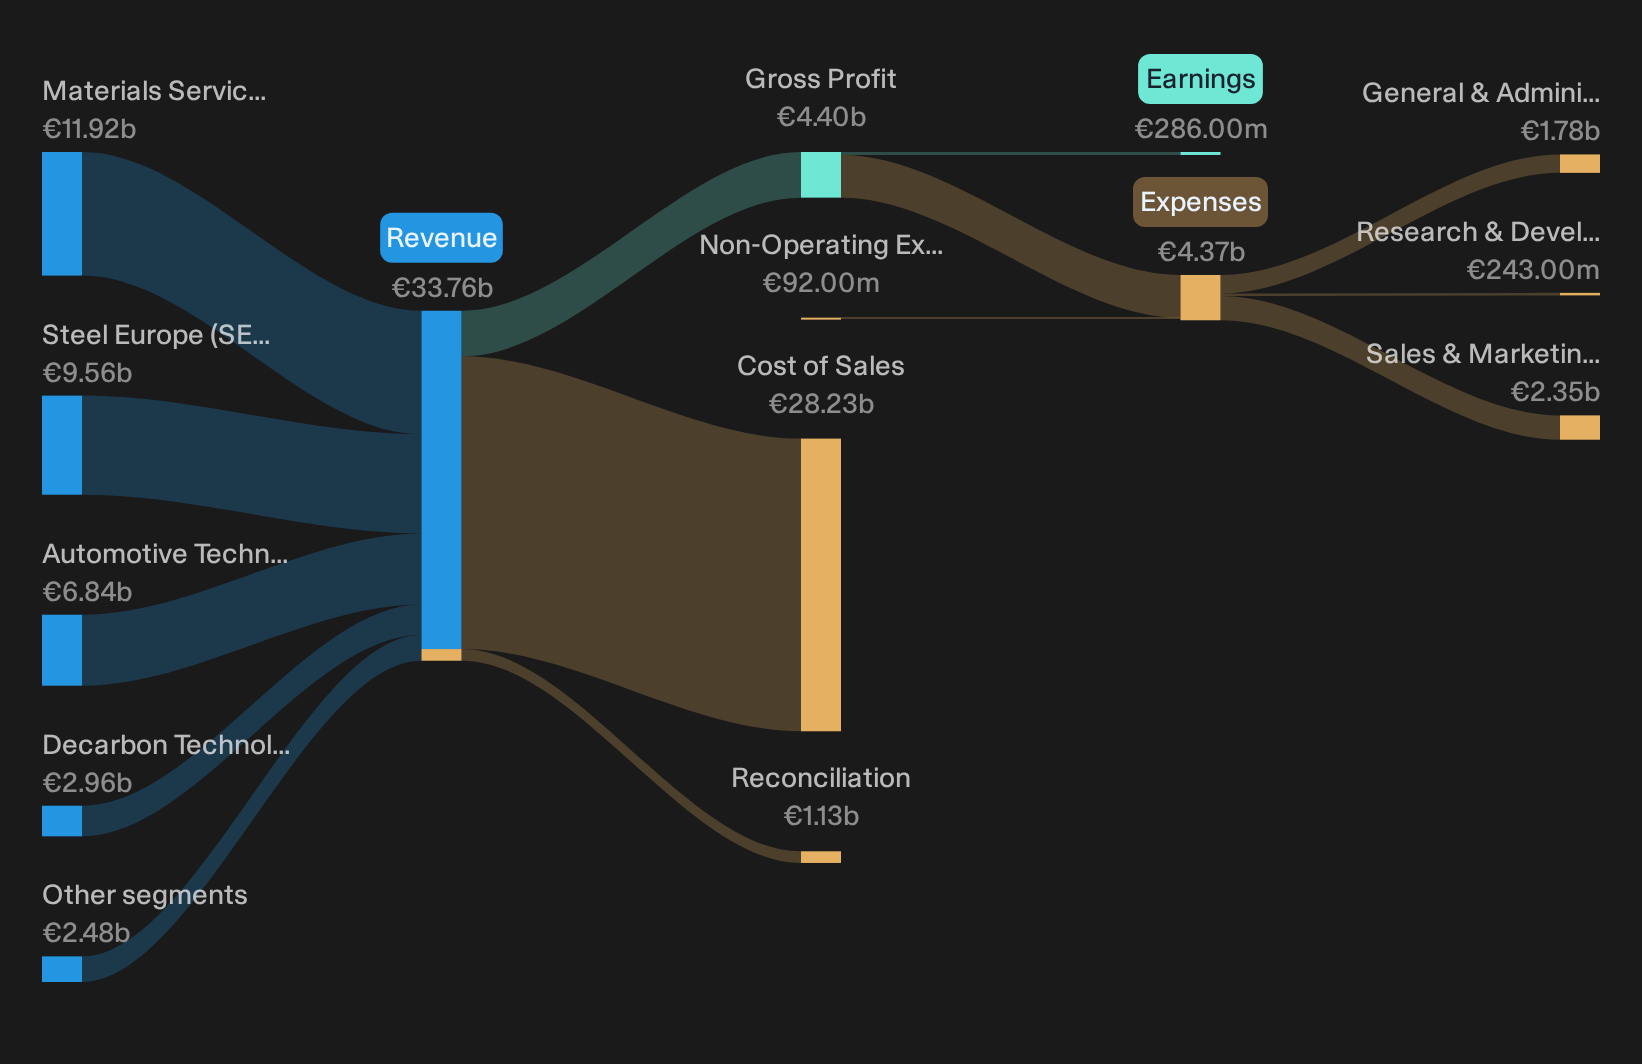
Thyssenkrupp is a €8.5b industrial group that earns about €11.9b from Materials Services, €9.6b from Steel Europe, €6.8b from Automotive Technology, €3.0b from Decarbon Technologies and €2.5b from Marine Systems, after group level reconciliation items.
"The record order backlog above €20b at Marine Systems, together with the preferred builder role in Canada’s Patrol Submarine Project for up to 12 submarines, positions thyssenkrupp to negotiate follow on service and upgrade work that could add a second wave of higher margin revenue beyond the shipbuilding itself."
What happens if a single shift in where earnings come from quietly resets how investors think about thyssenkrupp’s gas heavy steel exposure versus its cash generation?
That potential reset in where the value really sits is exactly what the full narrative for thyssenkrupp unpacks, including how gas exposure could be overshadowed by accelerating cash engines elsewhere.
K+S (XTRA:SDF)
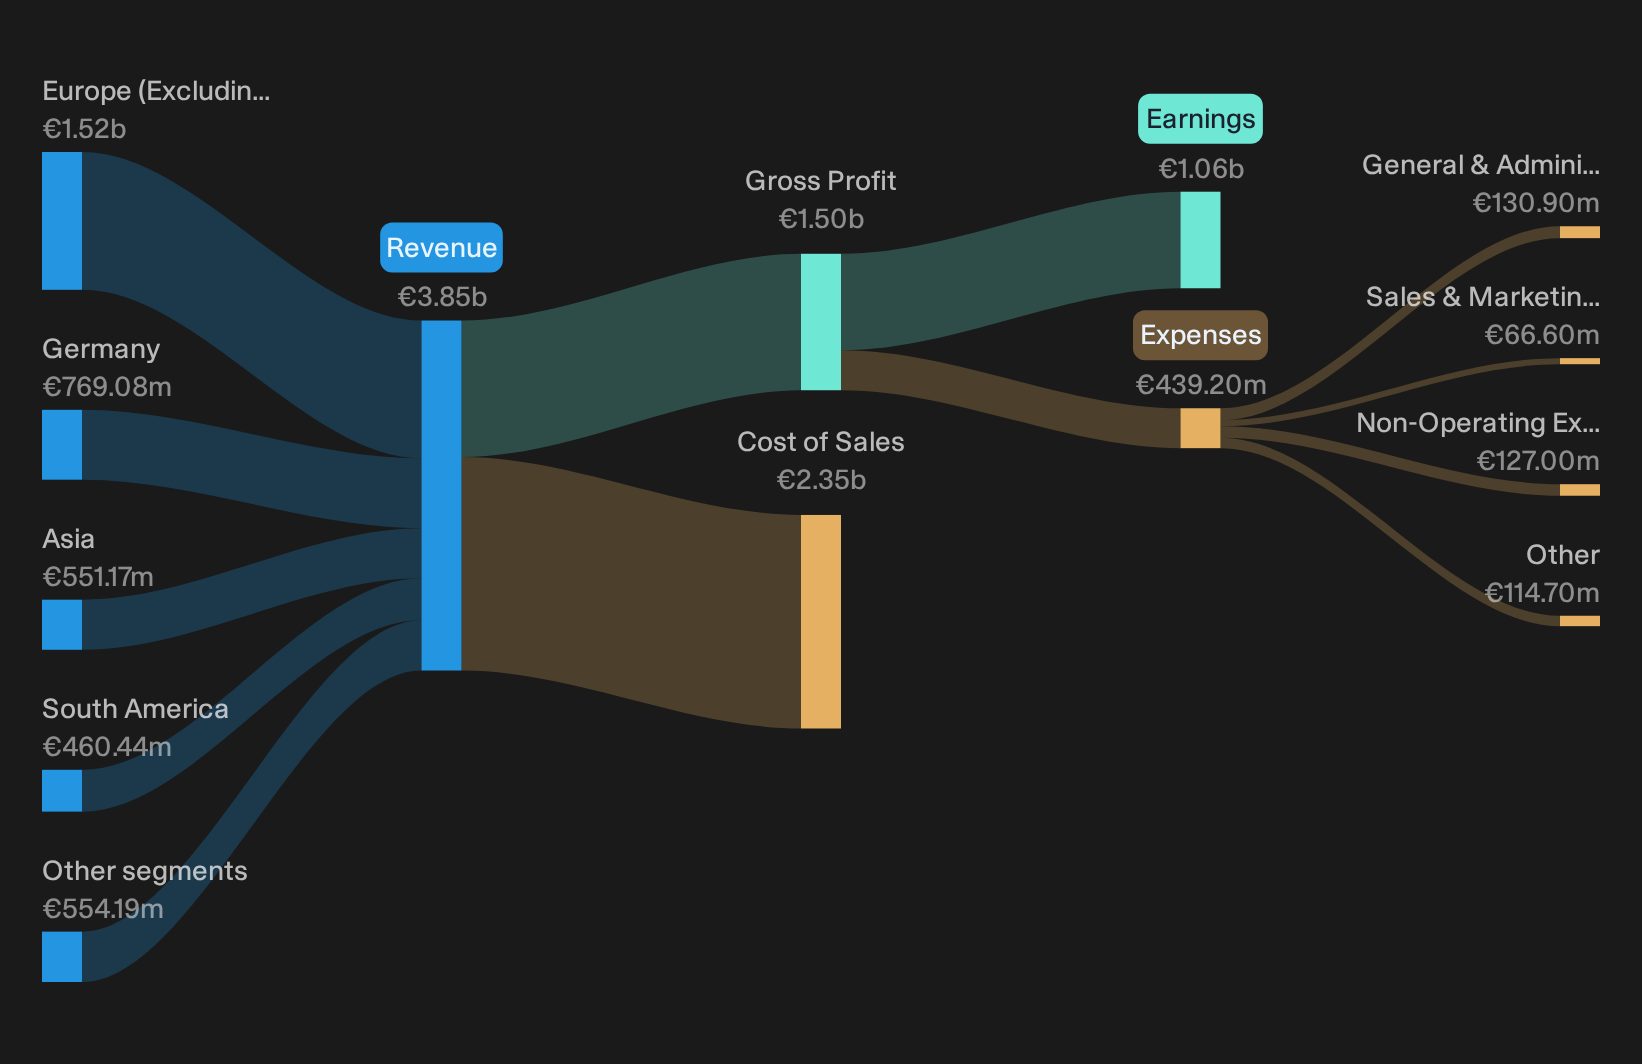
K+S fits neatly into the gas-exposed theme because it runs energy-heavy fertilizer and salt assets, while selling essential minerals into agriculture and industry. The Europe+ operating unit generates about €3.9b in revenue, and the business carries a roughly €2.3b market value.
"The company faces substantial capital expenditure requirements and significant German mining and environmental-remediation obligations."
One potential risk is that a single unseen pressure related to future energy and potash pricing could affect the balance for K+S margins and cash flow.
That energy and pricing pressure is the starting point for the full narrative for K+S, which maps how K+S risk could be masking a stronger long term earnings profile.
Seeking Fresh Alternatives Before Everyone Else
Some of the most interesting ideas start moving quietly, then momentum builds and prices rise once broader attention follows. Review these fresh picks while it matters and consider them early in your research process.
- Explore income potential from mature businesses by running through the 225 dividend fortresses before yields change and the window for higher cash payouts narrows.
- Look for early AI-related momentum by reviewing the curated 39 profitable AI stocks that aren't just burning cash that already pair revenue generation with controlled cash burn.
- Research opportunities connected to the grid upgrade cycle by checking the hand picked 42 power grid technology and infrastructure stocks that could be relevant as electrical infrastructure spending evolves.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com