


Missed Teck Resources' Run? What Holders Had To Believe
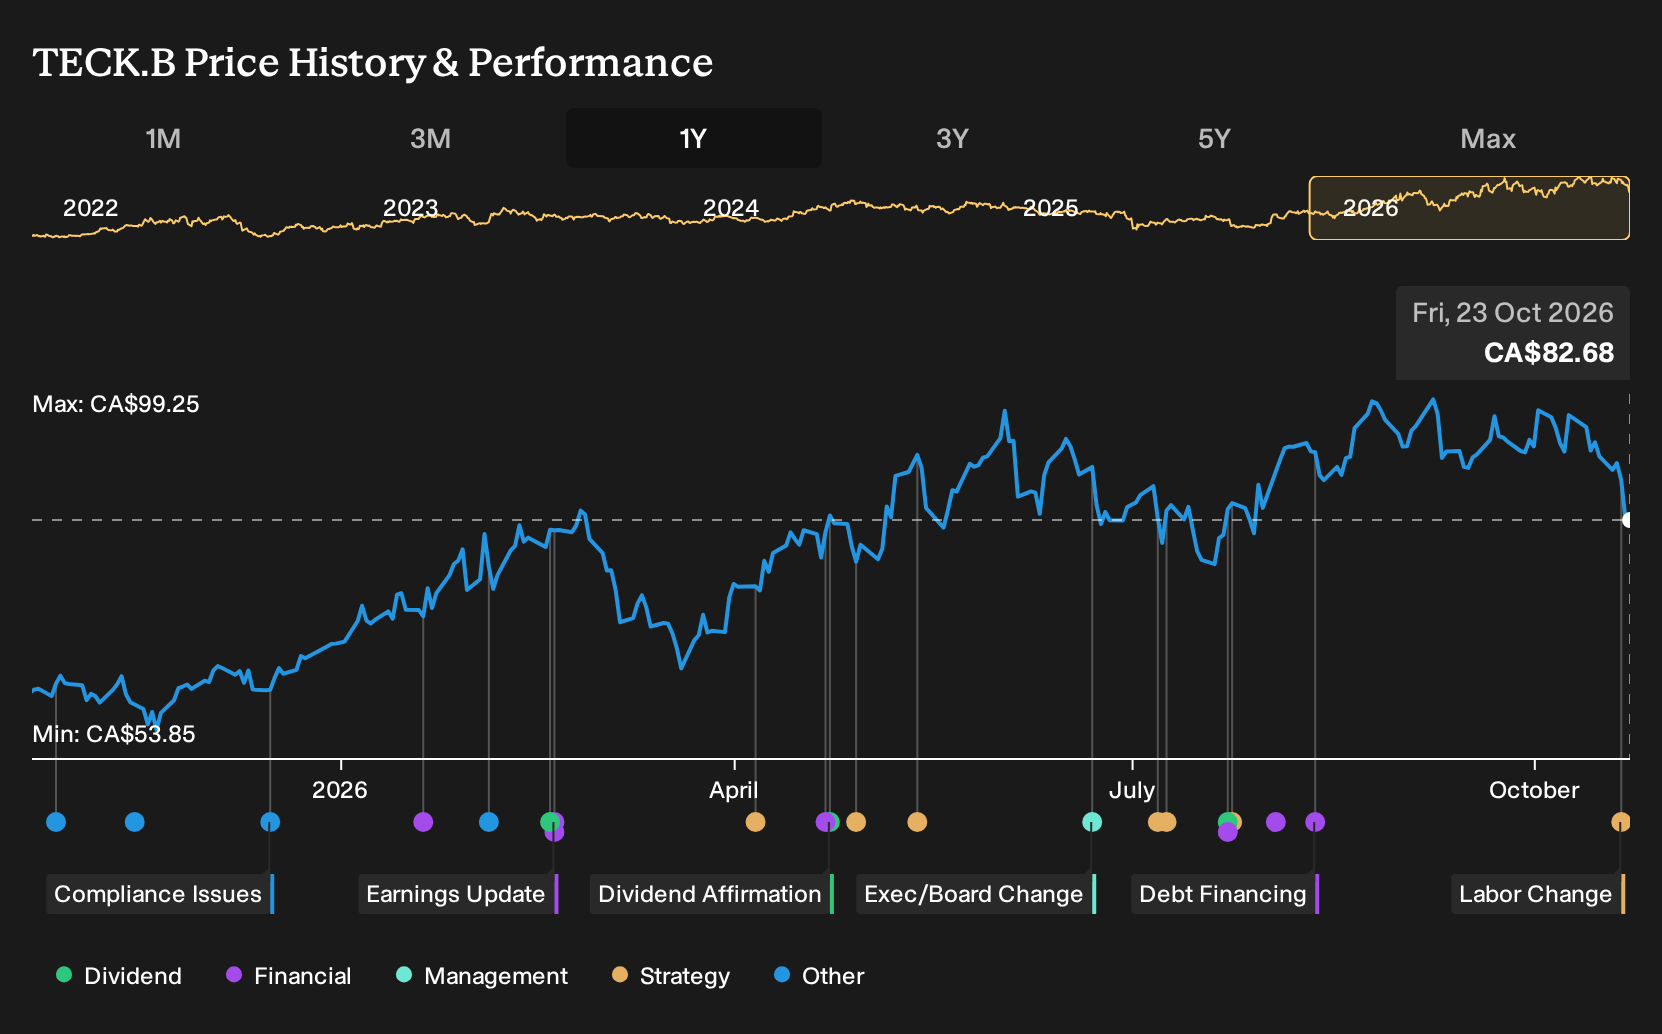
Teck Resources has packed a lot into the past year, from record copper-heavy quarters to a government-backed C$400 million commitment to expand critical minerals output at Trail. Holding Teck Resources over the past year would have returned 42.3%, including dividends. If you were deciding on 23 October 2025 whether to buy, what beliefs would you have needed to hold about copper growth, mergers, and project execution before any of this information was available?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
This theme extends beyond Teck Resources. See which of 16 top copper producer stocks may still merit a closer look.
The Argument You Would Have Been Weighing Up On Teck Resources
The shares cost CA$59.39 at the start, and the core question was whether Teck Resources was a copper growth story or a project risk story in disguise.
On the optimistic side, the bullish narrative saw fair value at CA$68.09, assuming accelerated copper expansion, successful QB debottlenecking, and earnings reaching CA$2.0b by 2028 on a 20.5x P/E.
The pessimistic view put fair value at CA$50, built on revenue growth of only 0.8%, a 7.2% profit margin, and concern that Highland Valley delays and broader permitting hurdles would drag on results.
What The Results Changed In The Teck Resources Debate
Teck Resources then reported Q2 2026 revenue of C$3,605m and net income of C$854m, with net margin rising from 10.2% to 23.7% versus Q2 2025. That strength in both sales and profitability leaned toward the optimistic copper expansion story. However, the still pending Anglo American merger meant the consolidation and integration part of the bull case remained untested.
The takeaway is simple. When you see a thesis built on higher future margins, go back to the quarterly net margin line and check whether it is actually moving toward the percentage embedded in the original narrative.
What Teck Resources' 42% Run Up Now Asks You To Believe
Teck Resources now trades at CA$82.68, and this Narrative’s Fair Value sits below that level. This frames the recent one year 42.3% gain as front loaded optimism rather than idle drift.
The selected Narrative questions whether copper heavy projects and the Anglo Teck merger can offset weaker zinc and high capital spending over time. A buyer today is effectively assuming those assets deliver reliable volumes and margins. How do the highlighted cost and execution risks weigh on that belief?
"Key Takeaways Bearish analysts expect Teck Resources to face sustained pressure on long term growth and profitability, as high capital spending on copper projects coincides with declining zinc output and higher unit costs at mature assets. The main factor that has to go right is that the copper heavy portfolio, including QB, Highland Valley and the Anglo Teck merger, delivers stable volumes and attractive margins once the current peak investment phase passes."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking One Step Beyond Teck Resources
Teck Resources puts copper and zinc in focus for you. Yet the same energy transition also leans heavily on rare earth magnets in critical hardware.
Those magnets keep electric motors compact and efficient, from vehicles to turbines. A different miner and manufacturer is working quietly to secure that supply.
This business combines rare earth extraction with processing and magnet production. Government contracts and long term deals with major tech and auto groups support that plan.
Recycling projects and domestic supply chain policies could reshape how it earns money. The open question is how reliably that magnet heavy model scales from here.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 85% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com