


AT&T Stock In Focus After Earnings And Copper Network Phaseout Push
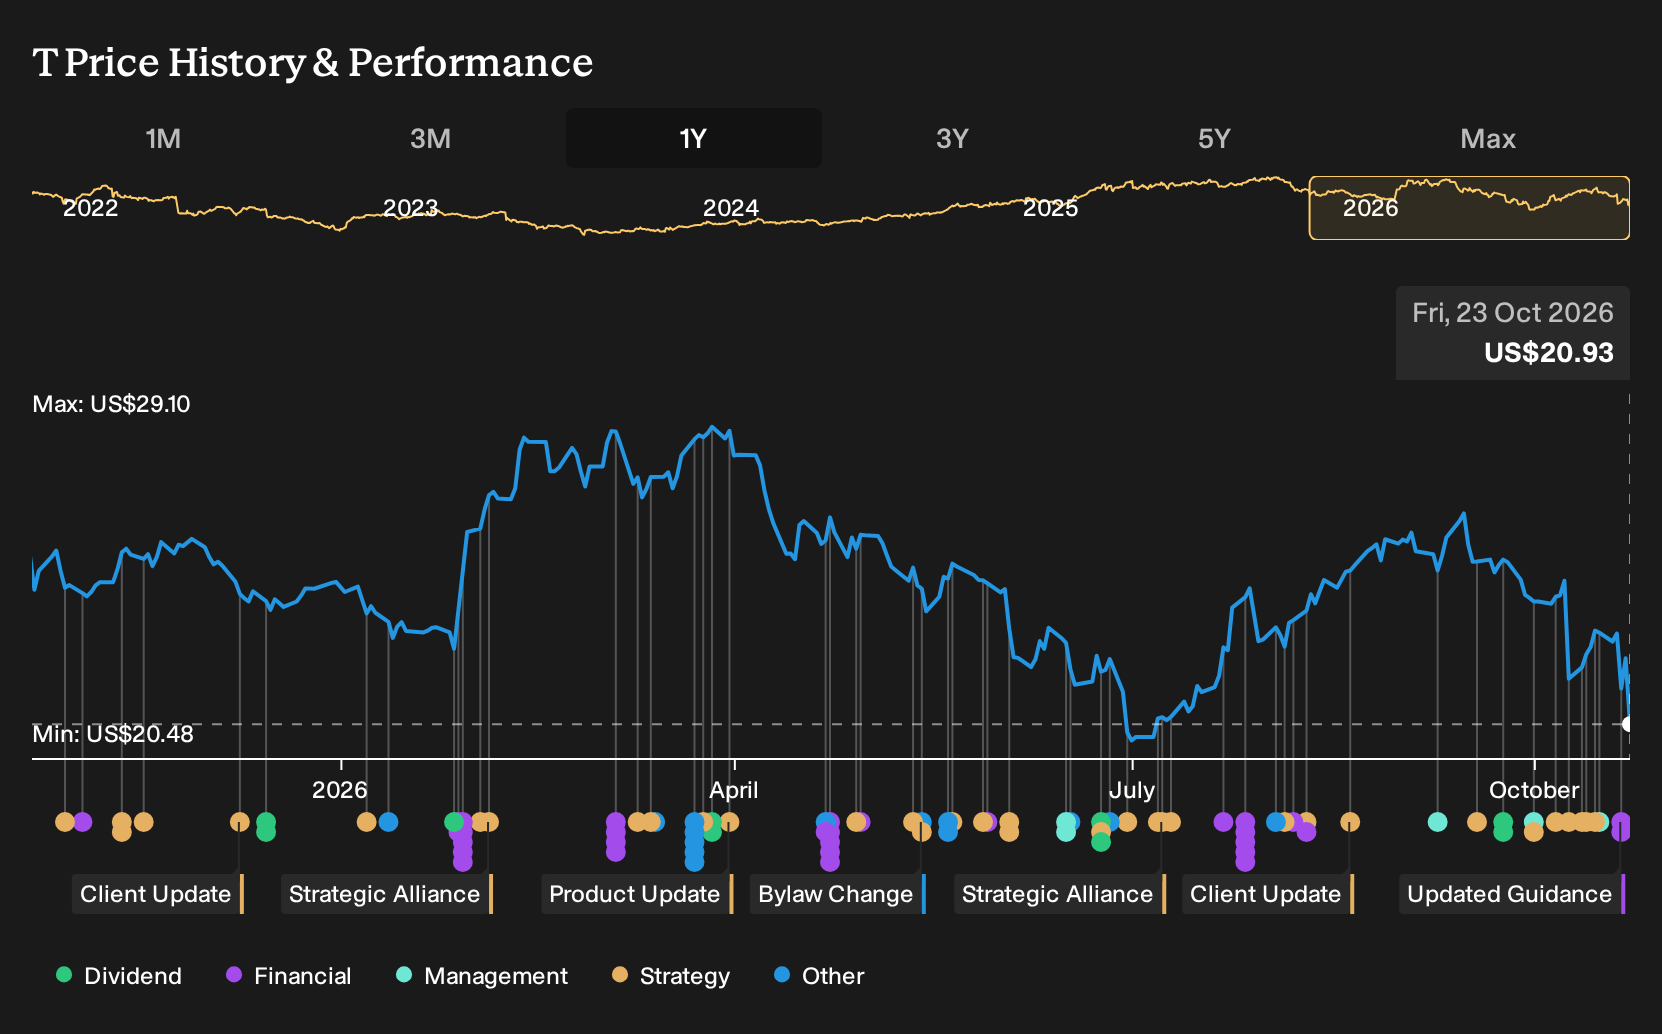
- AT&T reported third quarter 2026 revenue of US$32,322 million and net income of US$891 million, reaffirming guidance for low single digit consolidated service revenue growth for the full year while continuing to retire legacy copper in favor of fiber and wireless networks.
- The combination of lower earnings per share compared with a year ago and faster copper phase out highlights how AT&T is absorbing near term profit pressure while pushing harder on long term network modernization and customer experience initiatives such as AT&T Phone Advanced.
- We will now look at how AT&T’s earnings mix and copper retirement push reshape the broader investment narrative for the telecom company.
AT&T Investment Narrative Recap
To own AT&T, you need to be comfortable with a telecom giant in the middle of a long, expensive shift from copper to fiber and wireless while near term profitability stays under pressure. The third quarter numbers underline that tension. Revenue was US$32,322 million, yet net income for the period was US$891 million with diluted EPS of US$0.12.
Management still expects consolidated service revenue to grow at a low single digit rate for 2026, so the core top line message is unchanged. The near term swing factor remains how quickly AT&T can pull copper related costs out of the system. The biggest risk is that weaker margins linger while debt stays elevated.
The most relevant update for this story is AT&T’s expansion of America’s Best Guarantee, which leans on its fiber, Internet Air and wireless footprint. Short hold times, automatic outage credits, internet backup and single agent support are all about making converged connectivity stickier and easier to manage for households.
For you as an investor, that initiative connects directly to the main catalyst. AT&T needs higher value, lower churn relationships to justify heavy network spend and the copper shutdown. If the Guarantee leads to better retention and more customers pairing fiber with wireless, it could support the service revenue mix that management’s guidance points toward.
AT&T’s current analyst narrative points to revenues of US$137.5b and earnings of US$19.9b by 2029, based on assumed 2.2% yearly revenue growth and an earnings increase of about US$6.8b from US$13.1b today.
Discover why AT&T's fair value indicates a 36% potential upside to its current price, which some investors believe could be realized more quickly than expected.
Exploring Other Perspectives
One alternate view leans hard into AT&T’s capital return plans. The most optimistic analysts were working off forecasts of about US$141.8b in 2029 revenue and US$21.4b in earnings, with a higher price target tied to richer P/E assumptions. Those projections pre date this guidance and copper pivot, so you may see opinions shift as the story evolves.
Explore 7 other AT&T fair value estimates, including one that suggests potential upside of up to 236% from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AT&T research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AT&T. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AT&T's overall financial health at a glance.
Looking for more AT&T style investment ideas?
If AT&T has you thinking about income, resilience and balance sheets, it can help to line it up against a broader field of potential opportunities using the Simply Wall St Screener.
- For investors who want income with some defense built in, take a look at 5 dividend fortresses that could complement a telecom position.
- If you prefer to keep risk in check while still staying in equities, scan through 30 resilient stocks with low risk scores that score well on resilience metrics.
- For those hunting for quality businesses that the market may be overlooking, browse 21 high quality undiscovered gems that combine solid fundamentals with lower visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com