


Grocery Outlet Holding (GO) Rebounds Sharply, Is It Still Above Fair Value?
Argus recently lifted its target price for Grocery Outlet Holding (GO) to US$11, putting fresh attention on how this discount grocer’s independently operated stores model lines up with its current market valuation.
Grocery Outlet Holding’s recent share price swing tells a mixed story. The stock has climbed strongly in the short term, with a 30-day share price return of 20.14% and a 90-day gain of 45.83%. However, the 1-year total shareholder return is still down 7.32% and the 3-year total shareholder return has fallen 52.07%, which suggests current momentum is building off a much weaker longer-term base.
Spot similar discount-driven setups by scanning our hand picked 28 high quality undervalued stocks that, like Grocery Outlet Holding, pair consumer demand with compressed expectations.The rebound in Grocery Outlet Holding is sharp, but the three-year track record remains weak. Does it make more sense to lean into this move now, or to wait for a cheaper reset before the valuation work begins?
Most Popular Narrative: 21.8% Overvalued
Grocery Outlet Holding last closed at $13.30, while the most followed narrative pegs fair value near $10.92. The current rebound therefore sits above what that framework supports and leans heavily on a successful turnaround in store returns and earnings quality.
The main thing that has to go right is that Grocery Outlet Holding converts its store optimization, system and data investments, and independent operator support into better comparable sales, healthier margins and sustained traffic, despite a more promotional grocery market and legal overhang.
See why 4 investors see Grocery Outlet Holding as 22% overvalued.
Result: Fair Value of $10.92 (OVERVALUED)
Still, the thesis around Grocery Outlet Holding can crack if comparable sales stay weak or if the legal and governance overhang keeps a lid on the valuation multiple.
Find out about the key risks to this Grocery Outlet Holding narrative.
Another View: Cash Flows Point To A Different Story
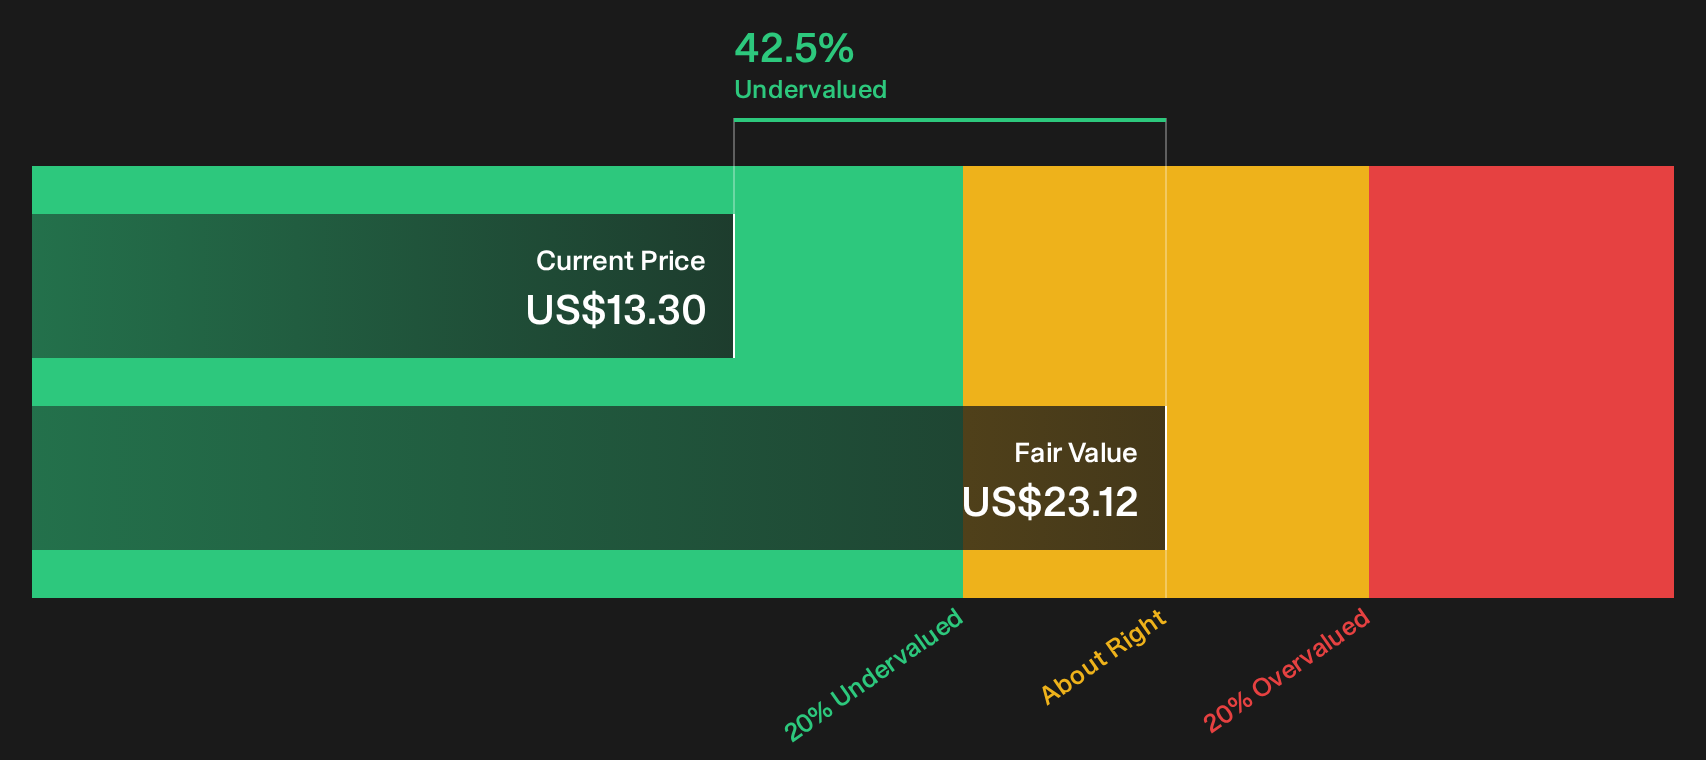
The first narrative around Grocery Outlet Holding leans on analyst targets that suggest the stock is about 21.8% overvalued at $13.30 versus a $10.92 fair value. The SWS DCF model comes to almost the opposite conclusion and points to upside instead.
On that framework, Grocery Outlet Holding at $13.30 is trading below an estimated future cash flow value of $23.12 per share. That gap implies the market is discounting execution, balance sheet and governance risks more heavily than the cash flow model, which raises a simple question for investors: Is the cash flow path too optimistic, or are sentiment driven concerns doing most of the work here?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages in the recent price action and valuation frameworks for Grocery Outlet Holding make this a live question for anyone watching the stock. If you want to move past headlines and sentiment, consider weighing the upside against the concerns in the data and see the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Grocery Outlet Holding?
If you stop with Grocery Outlet Holding, you ignore dozens of other setups where price, quality and expectations look out of sync in compelling ways.
- Target income stability and let a shortlist of reliable payers do the heavy lifting through the 5 dividend fortresses.
- Spot resilient businesses with room to breathe by scanning a list of solid balance sheet and fundamentals (24 results) that can better withstand choppy conditions.
- Hunt for mispriced opportunities early and sort through 21 high quality undiscovered gems before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com