


Did Jollibee Foods Fall Catch You Out? What Investors Missed
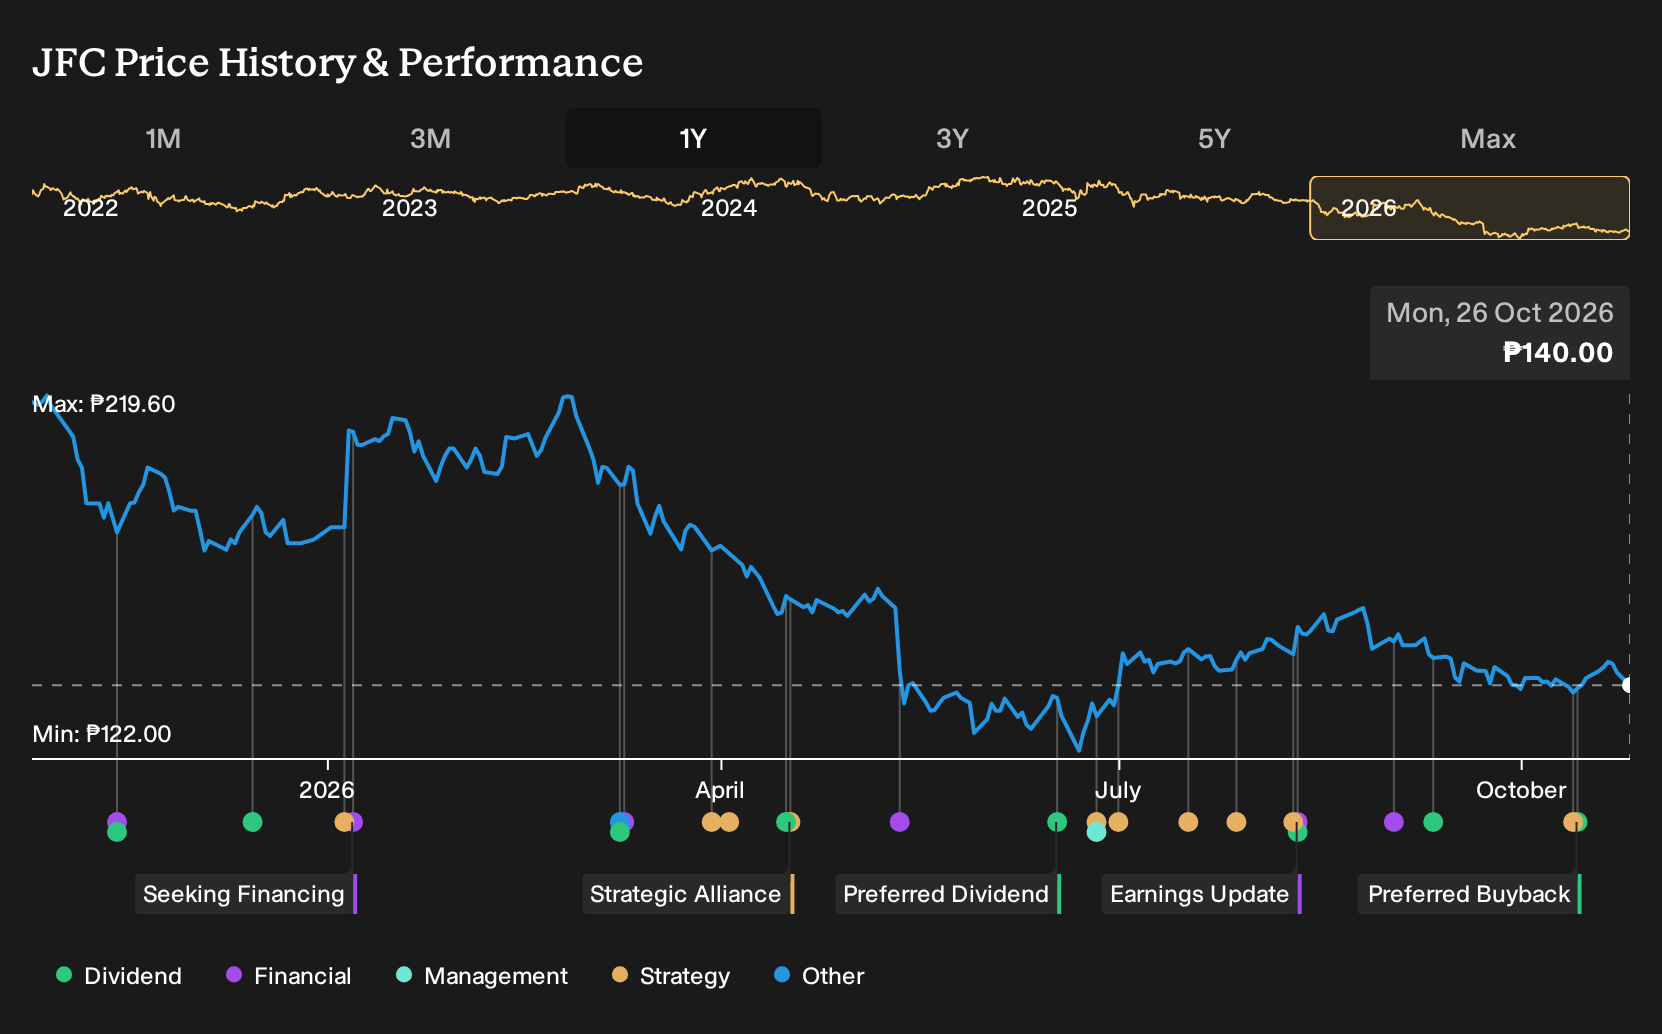
If you had read the upbeat and cautious Jollibee Foods narratives in late October 2025 and decided to sit it out, that choice now looks different. Holding Jollibee Foods over the past year would have meant a 34.2% loss, including dividends. Both bullish and bearish analyst groups were expecting higher earnings and margins, yet the result still hurt. If that drop had been on your account, which published warning or assumption would you wish you had scrutinized more closely?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Jollibee Foods harder to judge, start where the gap is still open and scan 198 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Jollibee Foods
The shares cost ₱219 at the start, and Jollibee Foods sat between two very different stories that both sounded reasonable on their own terms.
The bullish narrative put Fair Value at ₱288 and leaned on North America and Southeast Asia. It treated double digit system-wide and same store sales growth and rising digital usage as foundations for stronger revenue per store and higher net margins.
The bearish case pointed to a Fair Value of ₱192. It focused on Smashburger and other global brands as potential drags, and on higher labor, sustainability and regulatory costs that could lift expenses and pressure profitability over time.
What The Results Changed For The Jollibee Foods Argument
The key update for Jollibee Foods was Q2 2026 numbers. Revenue reached ₱85,908.229m and net income ₱3,304.947m compared with ₱77,626.069m and ₱3,121.092m in Q2 2025, which supported the focus on higher sales and earnings. The net margin shift from 4.0% to 3.8% pushed the profitability debate toward the cautious side. Overall, the evidence pointed in both directions.
The main variable in the discussion was the assumption that scale and digital reach would lift margins. When you review another restaurant stock, track whether rising revenue and profit actually come with a higher net margin, or whether extra volume is being generated with thinner economics.
What You Would Be Paying For In Jollibee Foods Today
Jollibee Foods now trades at ₱140, well below where investors started a year ago. The selected Narrative still places its Fair Value above the current price, anchored on a franchise led, cash flow heavy view of the group.
The fall only looks like an opening if you think Jollibee Foods can keep scaling higher margin franchise earnings while funding expansion mainly from internal cash generation. That is the bet you would be weighing.
"Some analysts expect Jollibee Foods to keep widening margins and earnings diversity as leadership leans into digital tools and an asset-light, franchise-led expansion model across key brands and regions. The main factor that has to go right is continued execution on franchising, digital adoption, and cost discipline so that margin gains seen in areas like Mang Inasal and recent group-level improvements are sustained while international growth is funded from internal cash flow and moderate leverage."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 37% below our estimate - helps clients solve complex technical, safety and litigation problems as products and regulations evolve.
- Company 2 - 18% below our estimate - scales supplement production capacity and logistics as everyday fitness habits increase demand.
- Company 3 - 24% below our estimate - embeds AI tools into cloud, productivity and developer workflows as customers refresh software stacks.
That is three of the list. See every one of the 207 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com