


Nippon Yusen Kabushiki Kaisha (TSE:9101) On Its Investment Plan And The Fair Value Debate
How Nippon Yusen Kabushiki Kaisha Stock Has Been Performing
Nippon Yusen Kabushiki Kaisha (TSE:9101) has drawn investor attention after its share price closed at ¥7,290 on 23 October 2026, with performance figures that highlight a mixed shorter term and stronger longer term picture.
Over the past day, the stock gained 2.26%, while the past week shows a decline of 0.96%. Across the past month the move is also lower, with the share price down 1.02%.
Looking at a wider window, the stock is up 21.10% over the past 3 months and has returned 42.38% year to date. Over the past year, total return is 42.63%.
For longer horizon investors, the total return over 3 years is about 119%, and over 5 years it is about 307%. These figures reflect both price change and any reinvested income over those periods.
The recent pattern for Nippon Yusen Kabushiki Kaisha is a brief pullback in the 1 month share price return, set against a much stronger 90 day move and a solid 1 year total shareholder return. Together, these factors point to cooling near term momentum after a strong run.
Compare Nippon Yusen Kabushiki Kaisha's run with a hand picked list of solid balance sheet and fundamentals (23 results) to see how other financially robust stocks have been moving this year.
The recent surge in Nippon Yusen Kabushiki Kaisha, set against a price that now sits above analyst targets and some intrinsic estimates, raises a sharper issue: Where does fair value really lie in that spread?
Most Popular Narrative: 10% Overvalued
The most followed valuation narrative puts Nippon Yusen Kabushiki Kaisha's fair value at ¥6,637, compared with a last close of ¥7,290. This points to a market price sitting above that intrinsic estimate and places more emphasis on how future execution plays out.
The main thing that has to go right is that management executes on the enlarged ¥1.6b midterm investment plan, including the NS United and Walden integrations, without letting higher leverage and weaker Logistics results drag on group returns.
See why 1 investors see Nippon Yusen Kabushiki Kaisha as 10% overvalued.
Result: Fair Value of ¥6,637 (OVERVALUED)
Still, higher fuel costs and prolonged rerouting around the Strait of Hormuz and Suez could squeeze Nippon Yusen Kabushiki Kaisha margins and challenge the current valuation story.
Find out about the key risks to this Nippon Yusen Kabushiki Kaisha narrative.
Another View On Nippon Yusen Kabushiki Kaisha’s Valuation
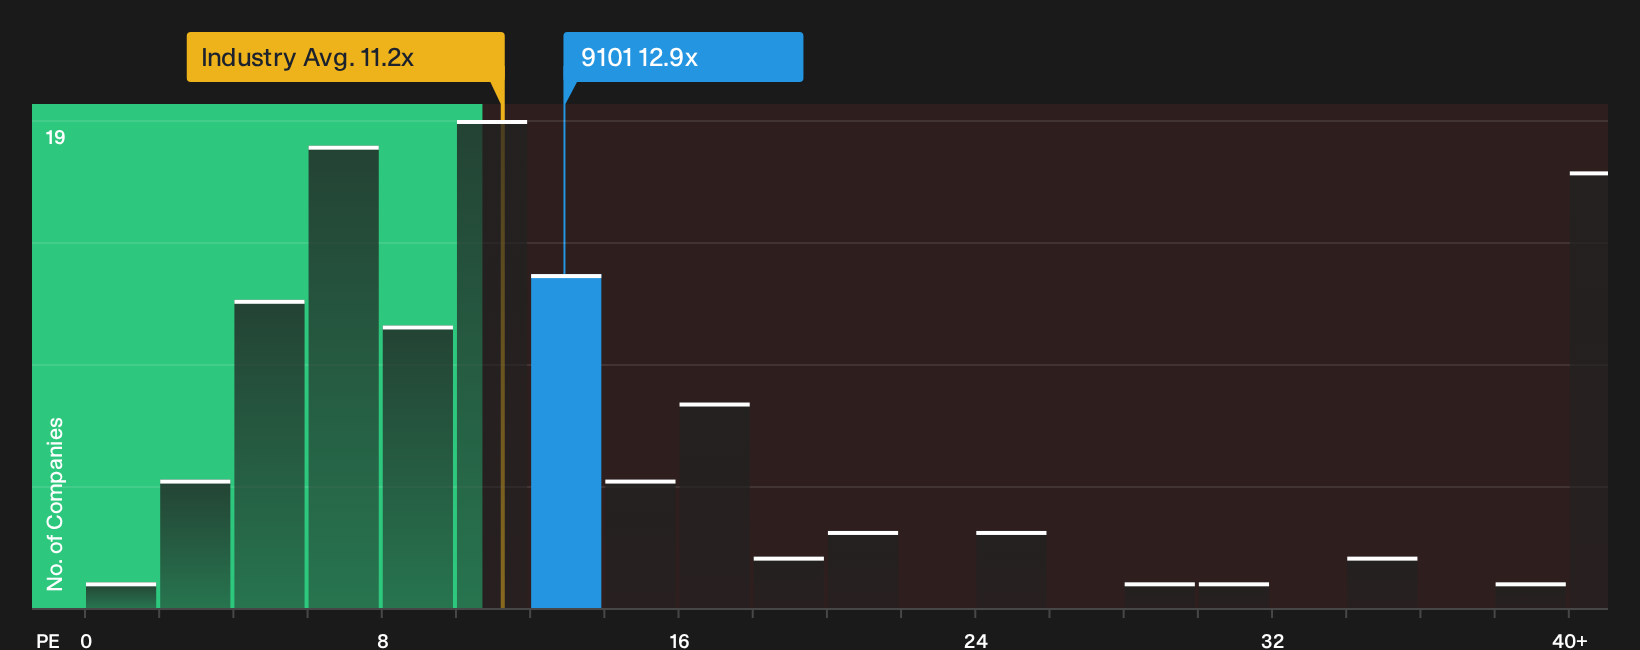
The market comparison tells a different story. Nippon Yusen Kabushiki Kaisha trades on a P/E of 12.9x, above the Asian Shipping group at 11.2x and the peer average at 11.4x, yet below its own fair ratio of 16.2x. Is that a premium worth paying or a cushion worth watching?
For a closer look at how this P/E gap stacks up against industry and peers, and what it could mean for future valuation swings, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or clear message? Either way, if you want to move quickly and ground your own view in the numbers that matter, start by weighing the 2 key rewards and 3 important warning signs.
Looking For More Nippon Yusen Kabushiki Kaisha Style Ideas?
If Nippon Yusen Kabushiki Kaisha has sharpened your focus on valuation and quality, do not stop here. Broaden your watchlist now and keep your edge.
- Target sturdier portfolios by screening for resilient balance sheets and consistent fundamentals through a focused list of solid balance sheet and fundamentals (23 results).
- Hunt for potential mispricings by scanning a curated 14 high quality undervalued stocks that filters for quality alongside attractive valuation markers.
- Prioritise stability and steady income by reviewing a hand picked 30 dividend fortresses that concentrates on higher yielding, durable payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com