


Why Suzano Stock Stands Out After Brazil’s Election Reset
Brazil’s election shock has yanked the market spotlight back onto local large caps, with traders bracing for sharp moves in stocks, bonds and the real as Lula’s win forces a rapid reset on fiscal expectations and interest rate bets. Violent repricing can punish indiscriminately, but it can also leave solid companies trading at value-style prices. This article walks through three Brazilian stocks exposed to that political story and explains why they may deserve a closer look now.
The stocks covered below are just a starting sample, and the full Brazil Large-Cap Value / High Beta Equities screen surfaced 11 more companies with equally compelling narratives that are not unpacked in this article.
If you want to identify potential high-conviction ideas quickly, head straight into the Brazil Large-Cap Value / High Beta Equities screener to filter and analyze the broader opportunity set.
Suzano (BOVESPA:SUZB3)
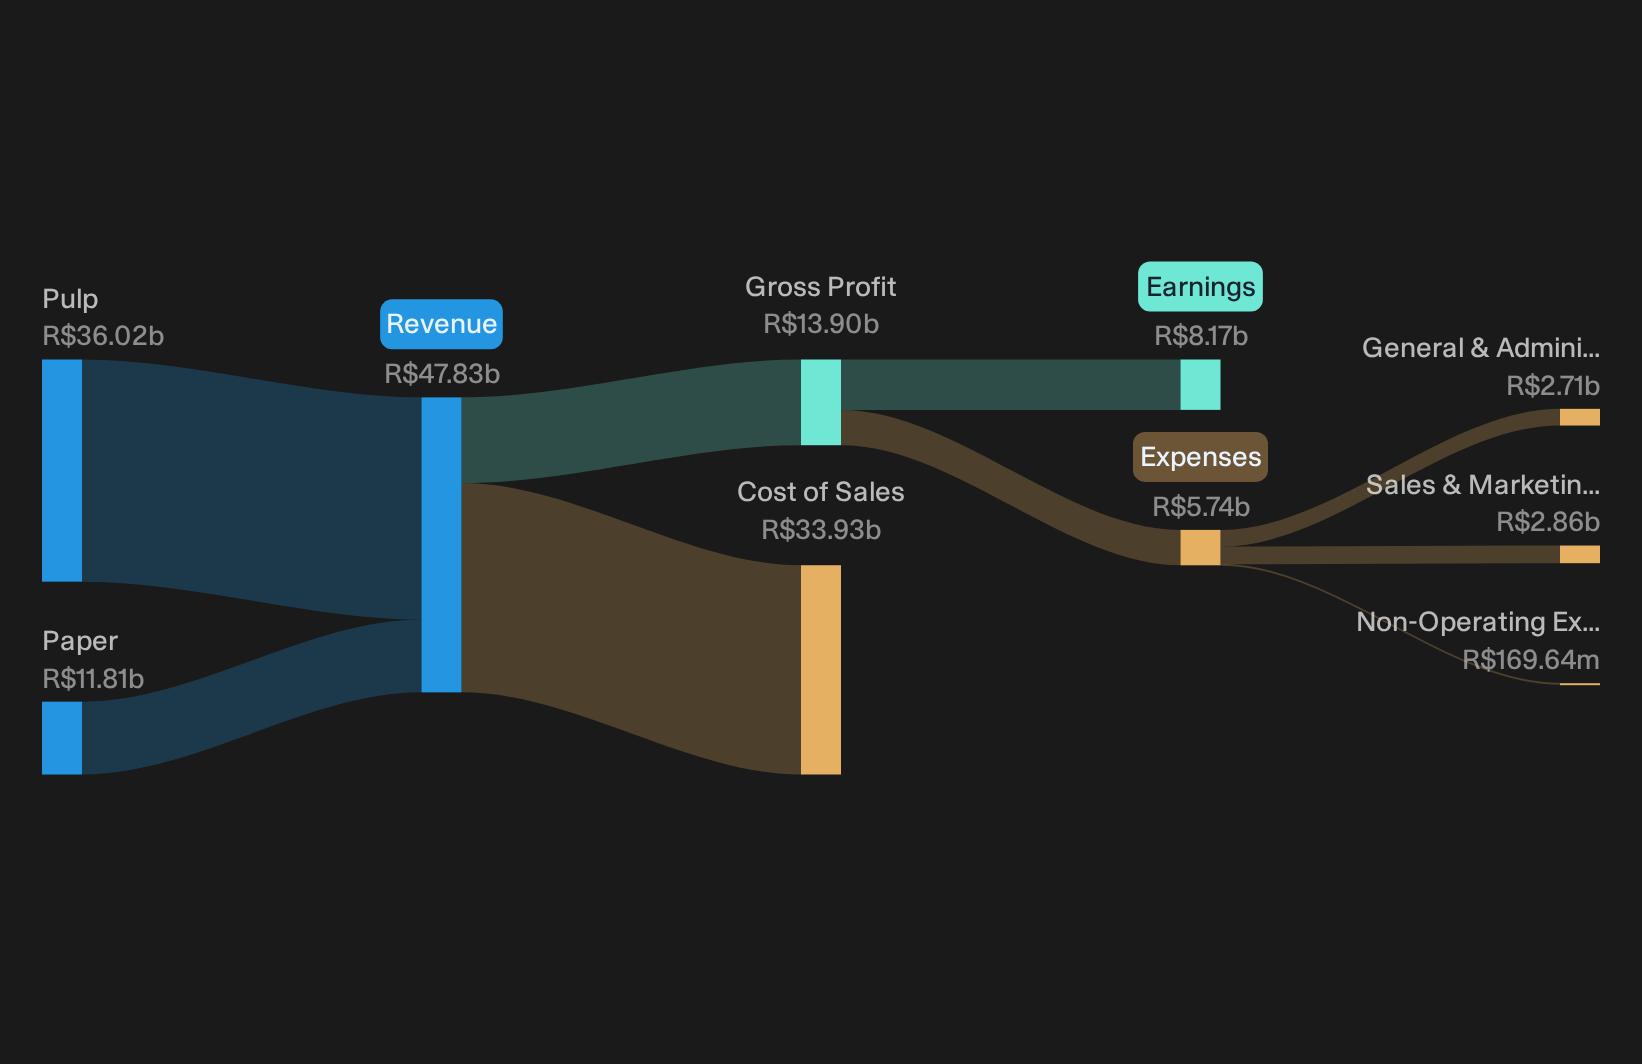
Overview: Suzano is a Brazilian pulp and paper producer that supplies hardwood pulp, printing paper, packaging, tissue and cellulose based materials worldwide.
Operations: Suzano generates about R$36.0b from pulp and R$11.8b from paper, with reported revenue primarily linked to operations in Brazil.
Market Cap: R$53.1b
For a value and high beta Brazil screen, Suzano brings the profile of a large exporter whose earnings and share price tend to move significantly when currency, rates and sentiment change.
"The Arbex joint venture with Kimberly Clark, which closed on July 1, 2026 with governance and management already in place, is expected to start delivering efficiency gains from the second half of 2026 and larger improvements from 2027 to 2028 that could support earnings and margins."
What matters now is how one pressure on Suzano’s cost base and balance sheet resolves, because that could reshape profit expectations.
How that pressure plays out is exactly what the full narrative for Suzano unpacks, separating short term noise from where Suzano’s earnings profile could be quietly resetting.
Cogna Educação (BOVESPA:COGN3)
Overview: Cogna Educação runs a broad education platform in Brazil, spanning higher education, basic schooling, distance learning, textbooks and education technology services.
Operations: Cogna Educação reports R$4.8b from University Education and R$3.0b in Segment Adjustment, with revenue currently concentrated in Brazil at R$7.8b.
Market Cap: R$6.2b
Cogna Educação plugs directly into the screener theme as a large, Brazil-first learning group. Its earnings and share price often swing with local employment, disposable income and access to credit, which can turn sharp selloffs into potential deep-value setups for patient investors.
"Consistent double digit revenue growth in both higher education and basic education, supported by improved commercial execution and process refinement, points to a larger paying student base and stronger pricing power."
The real test for Cogna Educação now sits in how one less visible funding and credit cost pressure shapes what those stronger tickets mean for margins.
That funding pressure is the hinge. Read the full narrative for Cogna Educação to see how Cogna Educação’s credit costs, pricing power and student mix could be quietly decoupling.

Vivara Participações (BOVESPA:VIVA3)
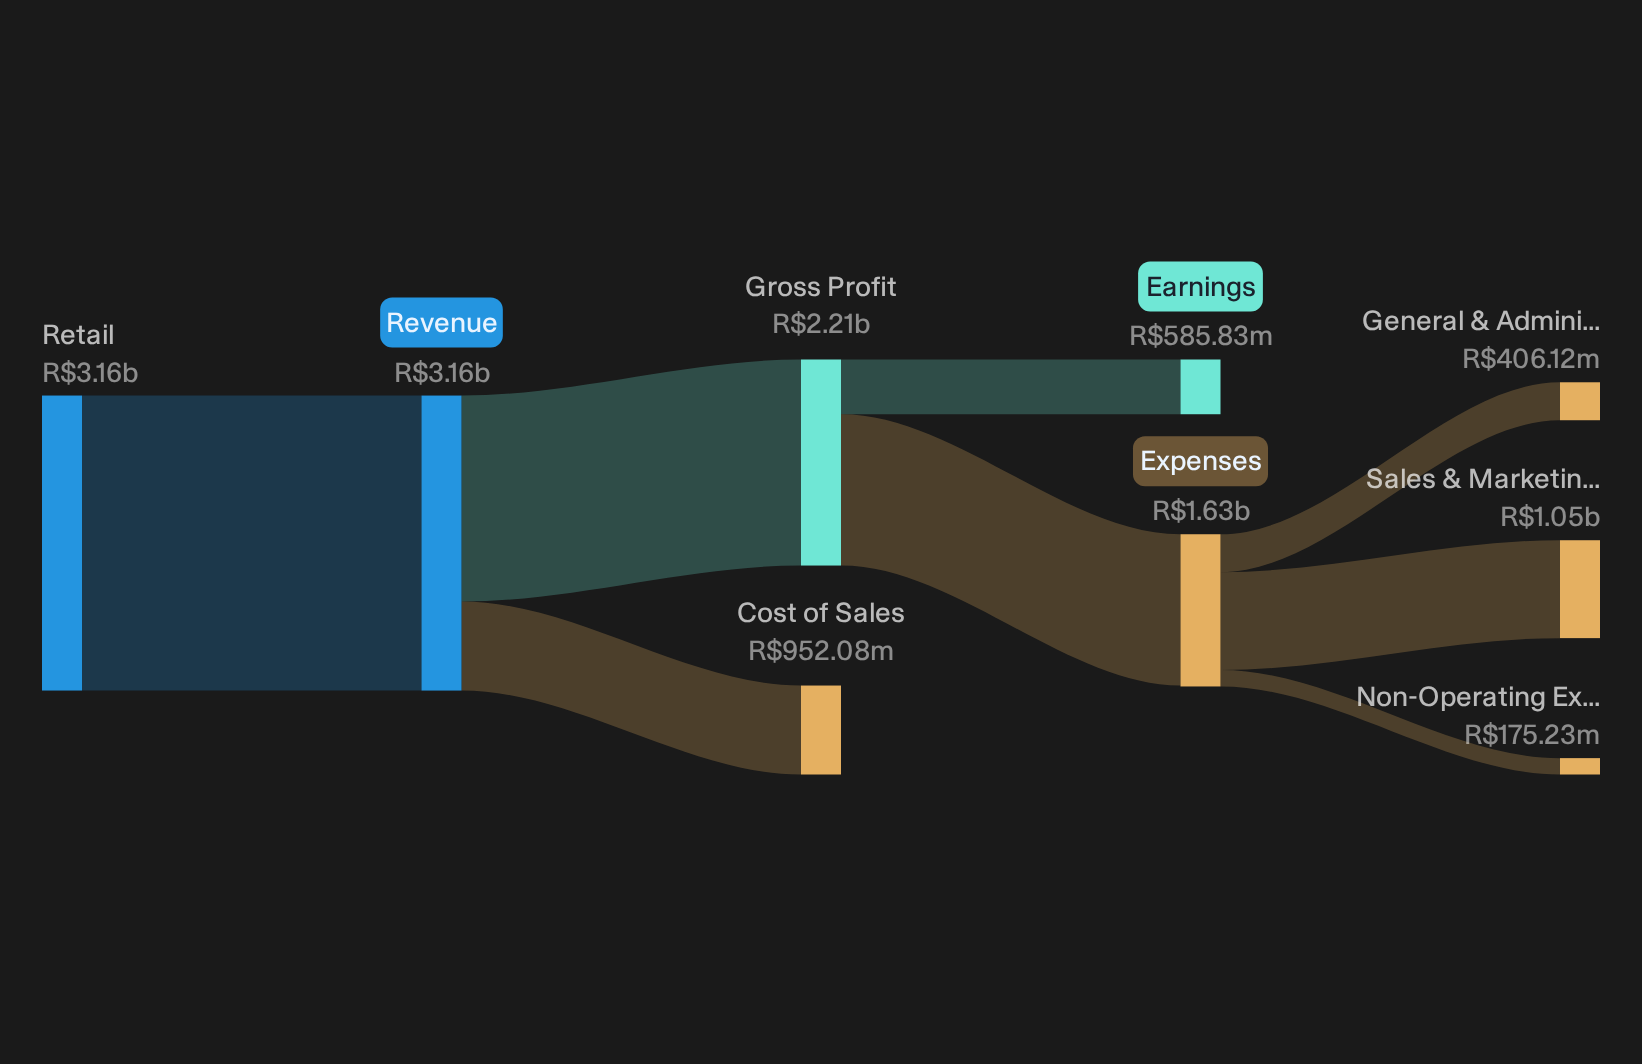
Overview: Vivara Participações runs a vertically integrated jewelry retailer in Brazil, tying branded rings, watches and gifts directly to domestic consumer cycles.
Operations: Vivara Participações generates about R$3.2b in retail sales, with essentially all revenue coming from Brazilian customers.
Market Cap: R$6.4b
Vivara Participações brings the screener theme right into Brazilian shopping malls, where earnings can swing quickly with confidence, credit and how willing consumers feel to trade up from basic purchases to jewelry and gift items.
"Planned reduction of total inventory coverage toward 400 to 450 days by 2027, following the 77 day cut already achieved, could keep releasing working capital and lift cash conversion relative to EBITDA."
What happens to Vivara Participações’ margins and growth now largely depends on how one cost and efficiency lever behaves under Lula era volatility.
That cost lever is the real tell, and the full narrative for Vivara Participações shows whether Vivara Participações has an underappreciated earnings engine quietly accelerating beneath Lula era volatility.
Seeking Fresh Alternatives Before They Fly
Breakout moves often start quietly while attention is elsewhere. Spot fresh ideas with real momentum under the radar for now, before prices move beyond your comfort zone. Consider acting while opportunities remain accessible.
- Target reliable income streams while others chase headlines by scanning the 228 dividend fortresses that prioritises payout strength alongside resilience under pressure.
- Track where AI cash flows already cover operating needs by reviewing the curated 39 profitable AI stocks that aren't just burning cash that filters out story-only plays burning through capital.
- Hunt for resilient balance sheets before the crowd by using the hand picked list of solid balance sheet and fundamentals (207 results) focused on robust cash generation and disciplined financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com