


Clorox (CLX) Stock Looks Reasonably Priced On Margin And Debt Pressure
Clorox has seen its share price fall a long way over the past few years, even as the business stays front and center in everyday cleaning cupboards. With the stock now trading near US$86, the real question for investors is whether that price still lines up with what its earnings can support.
- The share price has declined 37.4% over the past 5 years, which puts the focus squarely on whether the current valuation still reflects the earning power of the business.
- Recent commentary highlights pressure on gross margins, higher debt and the Gojo acquisition, all of which can affect how much of Clorox’s revenue ultimately shows up in earnings and how quickly that cash can be used to support shareholders.
- There is a second opinion on Clorox worth weighing. See what analysts think Clorox's shares could be worth.
The issue now is whether Clorox’s current share price is justified by the earnings it is generating today and is expected to produce over time.
To put Clorox’s earnings story in context, it can help to compare it with a wider set of dividend-focused consumer stocks using 5 dividend fortresses.
Is Clorox Fairly Priced on Earnings?
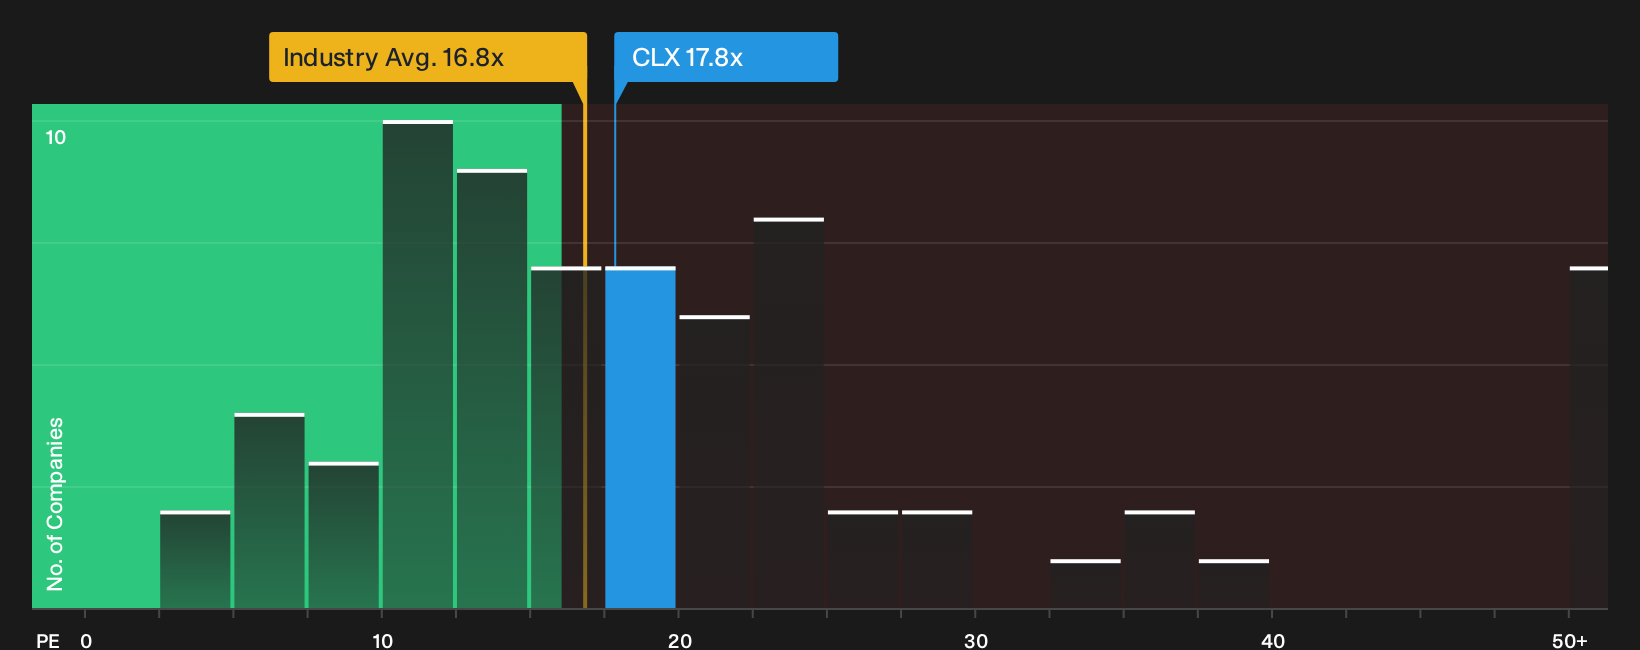
The P/E ratio fits Clorox because investors often look at it as a long term, earnings driven dividend payer. On this metric, the stock trades at about 17.8x earnings, which is lower than the peer group average of roughly 21.6x and only slightly above the Household Products sector at about 16.8x.
The tailored fair P/E implied by Simply Wall St’s model suggests that, given Clorox’s profile, a valuation moderately above the sector is reasonable, and the current 17.8x level sits close to that mark. Because the latest news flow has focused on weaker margins, higher debt and the Gojo purchase, a P/E around the modeled fair zone indicates the market is already weighing those pressures into the price rather than giving the stock a clear premium. Explore the numbers behind Clorox's P/E valuation.
The Clorox Narrative: What Would Justify Today's Price?
Clorox Narratives on Simply Wall St pick up where the P/E puzzle leaves off. They spell out which paths for future earnings, margins and growth would need to play out for the stock to be worth meaningfully more or less than today’s price, and they do this by laying out the assumptions behind each fair value view so you can watch how those hold up as fresh results and updates come through.
Community views on Clorox are now split between seeing a rebuilding story and worrying that execution risk is already priced in.
Bull case: 11% undervalued
"Expansion of health and hygiene as Clorox’s main focus, including the GOJO and Clorox Healthcare platforms, creates a larger base of contracted and repeat business…"
Discover why this Narrative puts Clorox at 11% undervalued.
Bear case: 17% overvalued
"The numbers on revenue trends, free cash flow margin compression, elevated dividend payout and guided earnings growth imply a share price that already reflects a smooth execution…"
Explore why this Narrative puts Clorox at 17% overvalued.
The Clorox price is only half the story
Before you stop at the P/E and fair value range for Clorox, it is worth asking who is actually steering the business and how their pay packets line up with your interests. See who runs Clorox and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com