


Learn Why The Bull Case For Banco BPM Stock Could Change Following Perpetual Notes Offering
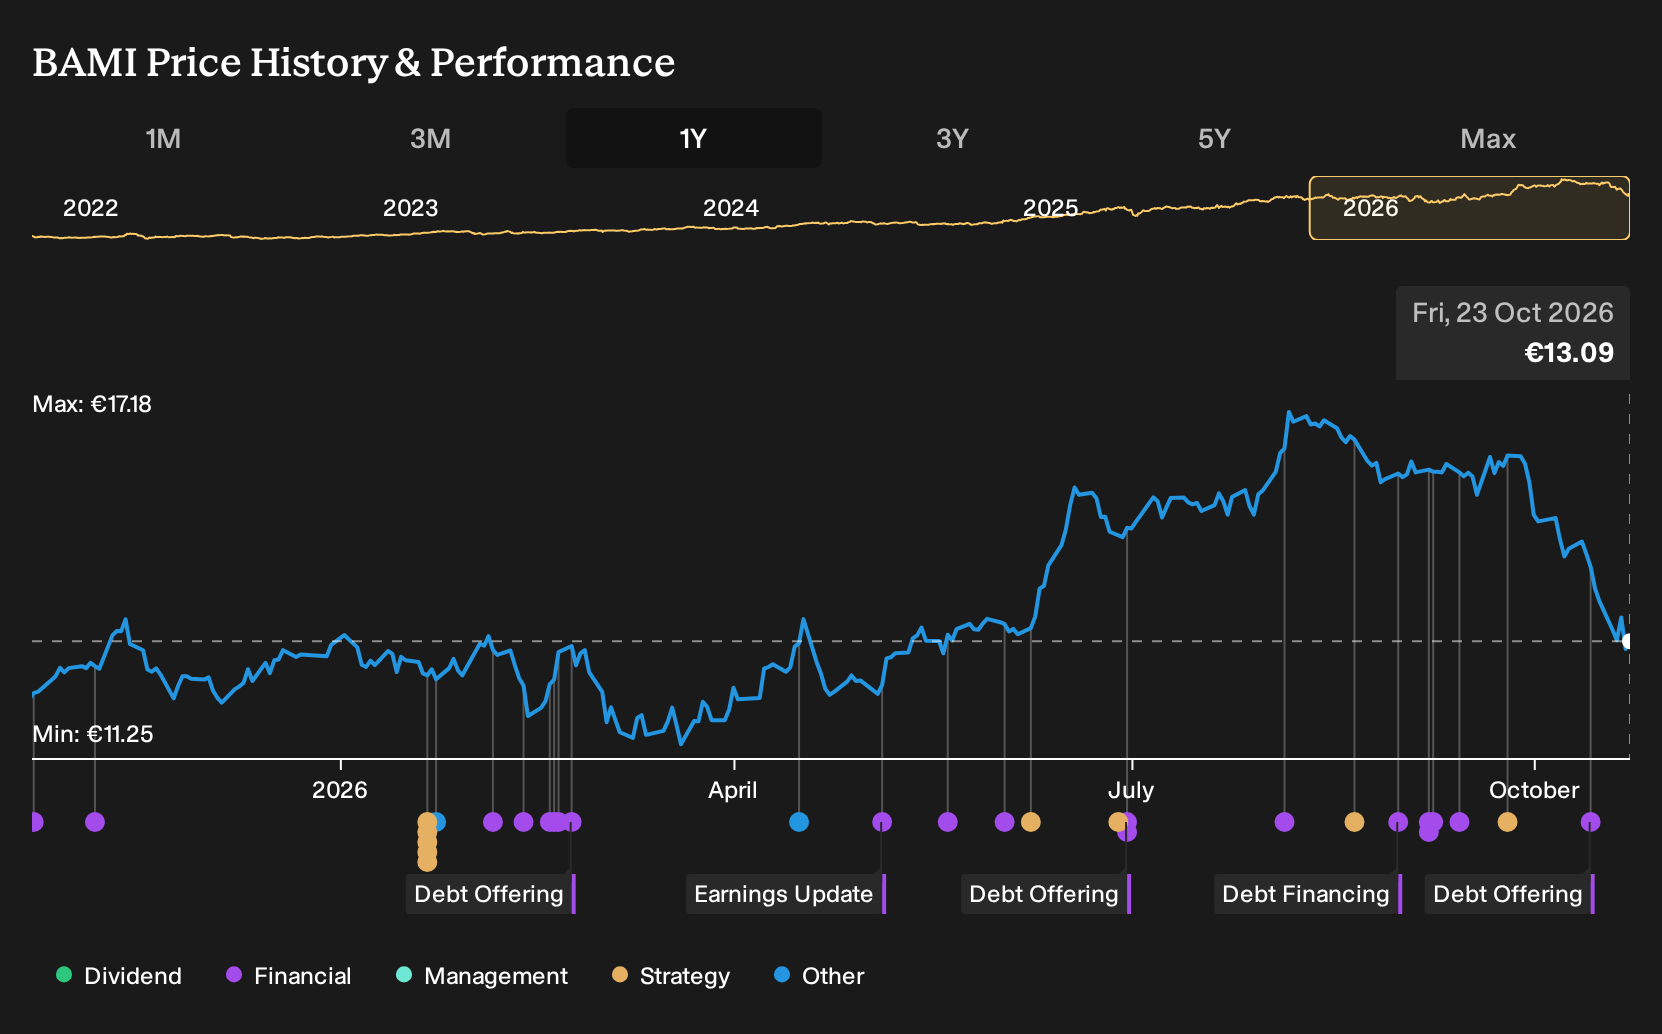
- Banco BPM has completed a €400 million fixed to floating perpetual notes offering at 100% of face value, issuing callable, variable rate, non convertible corporate bonds that add a new layer of long term funding to its capital structure.
- The perpetual, callable structure gives Banco BPM flexibility on future redemptions, while the variable coupon can help align funding costs with prevailing interest rate conditions.
- We will now look at how Banco BPM's €400 million perpetual notes offering could influence the broader investment narrative around its balance sheet.
Compare Banco BPM's funding move with other banks quietly reinforcing their capital through fresh bond and equity issuance by scanning our curated list of list of solid balance sheet and fundamentals (207 results).
Banco BPM Investment Narrative Recap
To own Banco BPM, you need to be comfortable with a bank that leans heavily on fee and insurance products, improved asset quality and a stronger capital position to support earnings. The immediate swing factor remains how well it keeps the balance between net interest income and fees, while tax and sector charges absorb more of its profit pool.
The new €400m perpetual notes add another funding line but do not radically change that operating story in the near term. The bigger watchpoint still sits in revenue mix resilience if funding conditions soften, and in how any future consolidation move might affect integration costs and net margins.
The fixed to floating perpetual notes transaction sits alongside Banco BPM’s already strengthened CET1 ratio of 14.4% and a larger MDA buffer by June 2026. Together, these datapoints matter for investors who are tracking how the bank can support planned shareholder remuneration while still funding growth and risk management.
Extra loss absorbing capital instruments such as these notes can interact with the wider plan to run with a lower cost of risk, keep the gross NPE ratio around recent levels and defend a 42% to 43% cost income ratio. Execution on those operational levers will likely matter more to the equity story than the pricing of this single bond.
Banco BPM's current analyst narrative points to €6.8 billion of revenue and €2.3 billion of earnings by 2029, built on 8.3% yearly revenue growth and an earnings increase of about €0.4 billion from €1.9 billion today.
Uncover why Banco BPM's fair value indicates a 21% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster tightly between €15.88 and €16.60, so even a small shift in Banco BPM assumptions can change the upside story. Higher recurring taxes or sector charges could pull those projections lower. Explore several community viewpoints before anchoring on any single number.
Explore another Banco BPM fair value estimate, including one that suggests up to 27% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Banco BPM research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Banco BPM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Banco BPM's overall financial health at a glance.
Looking for more Banco BPM style investment ideas?
If you like the structured way Banco BPM manages its capital stack, it can be useful to widen your watchlist with companies that show different strengths across quality, value and resilience. The Simply Wall St Screener gives you a simple way to sort through that wider universe using fundamentals rather than headlines.
- If you want quality at a discount, you can scan a curated set of companies trading on appealing valuations and strong fundamentals through the 197 high quality undervalued stocks.
- If reliability matters more to you than rapid gains, you can focus on resilience and balance sheet strength by reviewing the 223 resilient stocks with low risk scores.
- If you prefer stocks with income potential, you can narrow your search to companies with higher yields and solid payout profiles using the 230 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com