


What Core & Main Holders Got Wrong Before The Slide
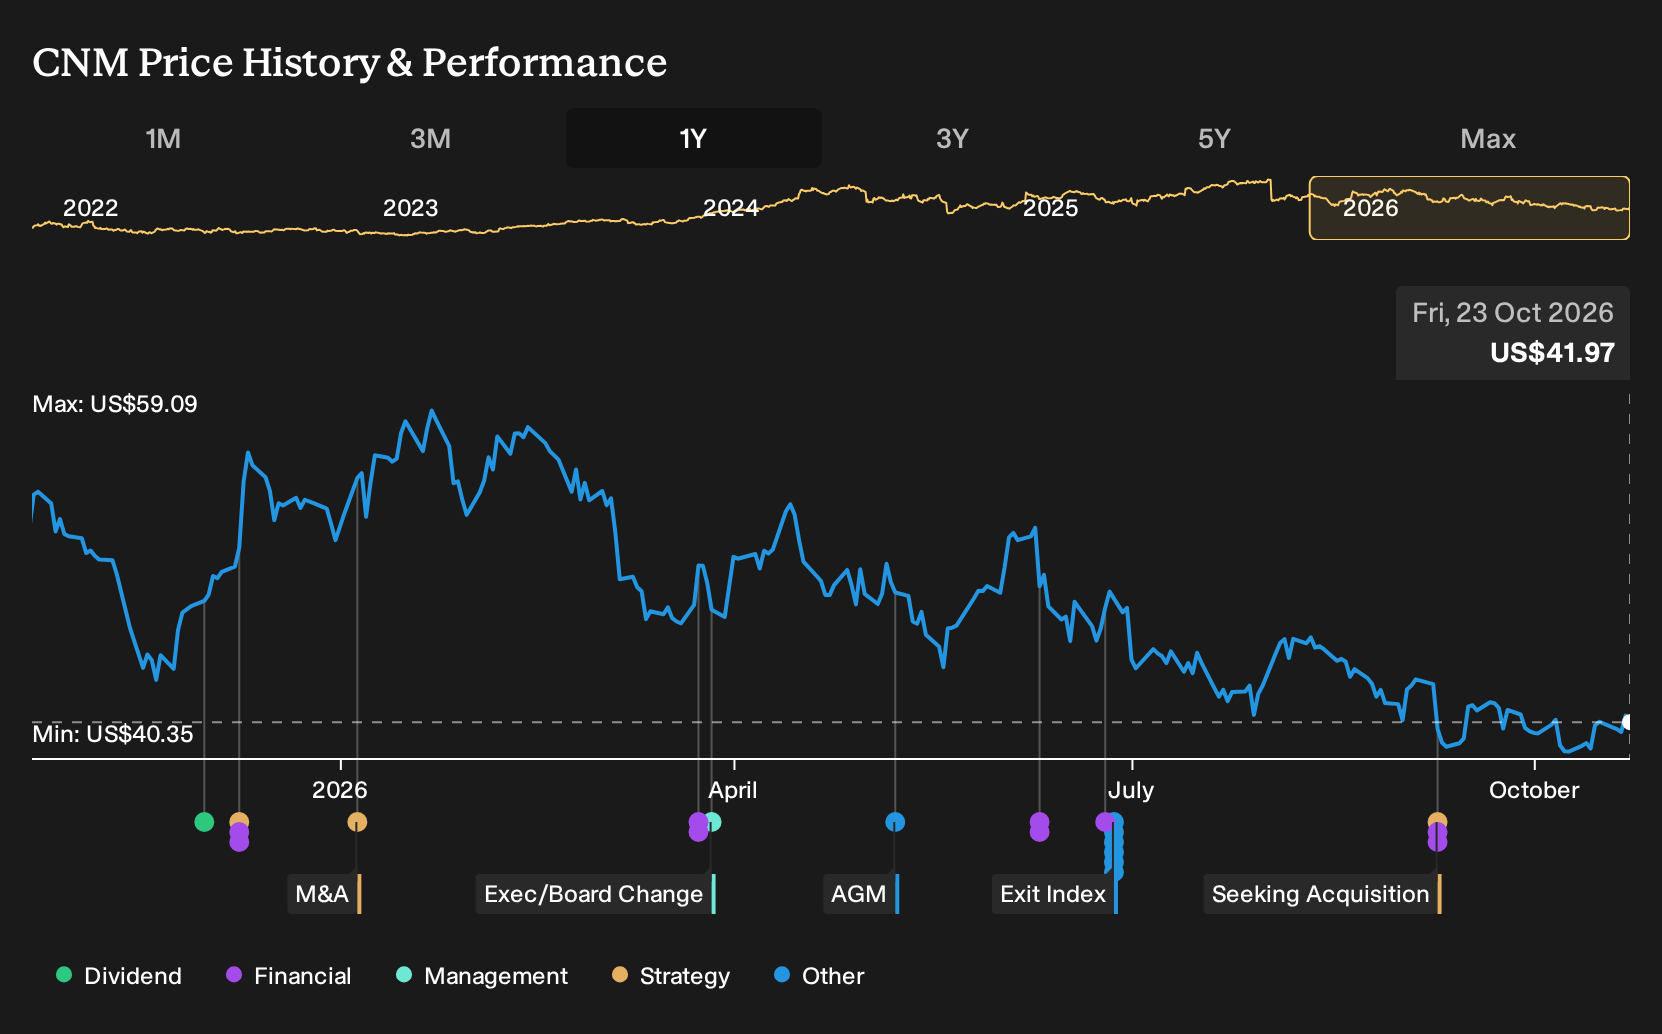
If you had bought Core & Main on 23 October 2025 and simply held it, the result would feel harsh. Investors who held Core & Main over the past year are down 22.2%, including dividends. That sits awkwardly beside later headlines about strong municipal demand, margin expansion and new locations. So what did the original case for 3.8% revenue growth, a 7.1% profit margin and a 23.5x P/E fail to factor in?
Core & Main has already moved. Pinpoint other ways to investigate the theme among 42 power grid technology and infrastructure stocks.
The Argument You Would Have Been Weighing Up On Core & Main
The shares cost US$54.47 at the start of the period, and Core & Main sat between two very different stories about where value might sit.
On the optimistic side, the bull case saw a Fair Value of US$59, a rough guide to what that scenario implied the stock could be worth if its 3.8% revenue growth and 7.1% profit margin assumptions played out.
The more cautious narrative pointed to a Fair Value of US$40, reflecting worries that digital platforms and direct-to-manufacturer sales could squeeze Core & Main's market share and profitability.
What The Results Changed For The Core & Main Argument
Core & Main kept talking about municipal demand and opened new locations, and the fiscal 2026 Q1 and Q2 reports backed that up. Net sales reached US$1.9b in Q1 2026, then US$2.15b in Q2 with higher adjusted EBITDA and earnings per share, and net margin edged from 6.4% to 6.7%. That supported the optimistic case on execution, while digital disruption concerns were not directly resolved.
The useful takeaway is simple. When a thesis leans on margin expansion and new sites, you track reported net margin and the pace of openings or acquisitions, not just the revenue line.
What You Are Paying For In Core & Main Today
Core & Main now trades at US$41.97, after a 22.2% loss over the past year. The selected Narrative sees Fair Value above that level and ties the gap to how municipal water work, smart utility projects and complex jobs are treated in the current price.
On this view, anyone buying today is effectively betting that higher margin private label products, smart utility solutions and complex infrastructure projects can keep supporting margins and cash generation.
"Core & Main needs its shift toward higher margin private label products, smart utility contracts and complex projects such as data centers and treatment plants to continue to support margins and cash generation while residential demand remains under pressure. The current valuation suggests the market is discounting Core & Main’s ability to sustain margin expansion, strong free cash flow and ongoing buybacks."
One Narrative disagrees with today's price. → See where this Narrative says Core & Main should trade
Looking Past Core & Main
Core & Main is tied to pipes in the ground and projects you can see. Your next step could be infrastructure you never touch.
Cities that upgrade water networks often rely on precise location data and reliable connectivity. The same desire for resilience pushes utilities to monitor assets from orbit.
One specialist aims to build that orbital backbone. It designs rockets and hardware so others can run communications, imaging and timing services in space.
If that framework holds together, more everyday services could ride on it. The lingering tension is how that extra value gets shared as the space economy thickens.
One Narrative has already put a figure on it. → Uncover the company trading 46% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com