


Affirm (AFRM) Stock Could Be 15% Overvalued Despite An Exclusive Payment Deal
Affirm Holdings has seen its share price move sharply at different points over the past few years, which puts fresh attention on a simple question for you as an investor: Is the current valuation of Affirm justified by the returns the business earns on the capital it puts to work in its buy now, pay later model.
- Over the past 3 years, Affirm Holdings has delivered a very large share price gain of about 3.1x. This makes it important to ask whether the company’s underlying returns on capital support that kind of outcome.
- The new multi-year, exclusive role as the pay over time provider for Sam’s Club online purchases may support expectations for higher transaction volumes. This could influence how effectively Affirm converts its funding base into profitable lending returns.
- What if you looked at Affirm Holdings through its earnings instead? See why Affirm Holdings's 12.3x P/E tells a different valuation story.
The stock's next move may depend on whether Affirm’s current price can be explained by the returns it earns on the capital it commits to its lending agreements and partnerships.
If you want to test the same question about returns on capital across a wider field, compare Affirm Holdings with companies in the 29 high quality undervalued stocks.
Is Affirm Holdings Getting Expensive on Excess Returns?
The Excess Returns model looks at how effectively Affirm Holdings turns its equity base into profits above its cost of capital. In this framework, an estimated stable earnings power of $3.49 per share is compared with a book value starting point of $16.26 per share and an average Return on Equity of 15.12%. After charging a cost of equity of $1.85 per share, the model leaves an excess return of $1.64 per share, which is then projected onto a higher stable book value of $23.08 per share over time.
Those inputs translate into an intrinsic value estimate that sits modestly below the current share price of $70.08, so the market is assigning a rich multiple to the future return profile implied by these assumptions. Because the recent exclusive pay over time deal with Sam’s Club concentrates a lot of future volume expectations into a single partnership, the current premium over the Excess Returns estimate may reflect how much investors already credit that agreement. This model can help you decide whether that gap between business returns and market pricing feels comfortable. Find out what Affirm Holdings could be worth using our Excess Returns estimate.
The Affirm Holdings Narrative: What Would Justify Today's Price?
Affirm Holdings' valuation puzzle only really comes into focus once you spell out the future that would need to unfold for the current share price to look either restrained or stretched. Narratives on Simply Wall St’s Community page do that by laying out different paths for growth, margins and earnings, and instead of a single multiple or model output, they describe the assumptions behind each fair value view so you can later compare those expectations with the results the business actually reports.
One of the top community narratives on Affirm Holdings: 29% undervalued
"Affirm's differentiated technology and underwriting (evidenced by the success with 0% APR loans and high user repeat rates) should improve customer lifetime value..."
Discover why this Narrative puts Affirm Holdings at 29% undervalued.
One more piece of the Affirm Holdings puzzle that could shift your view
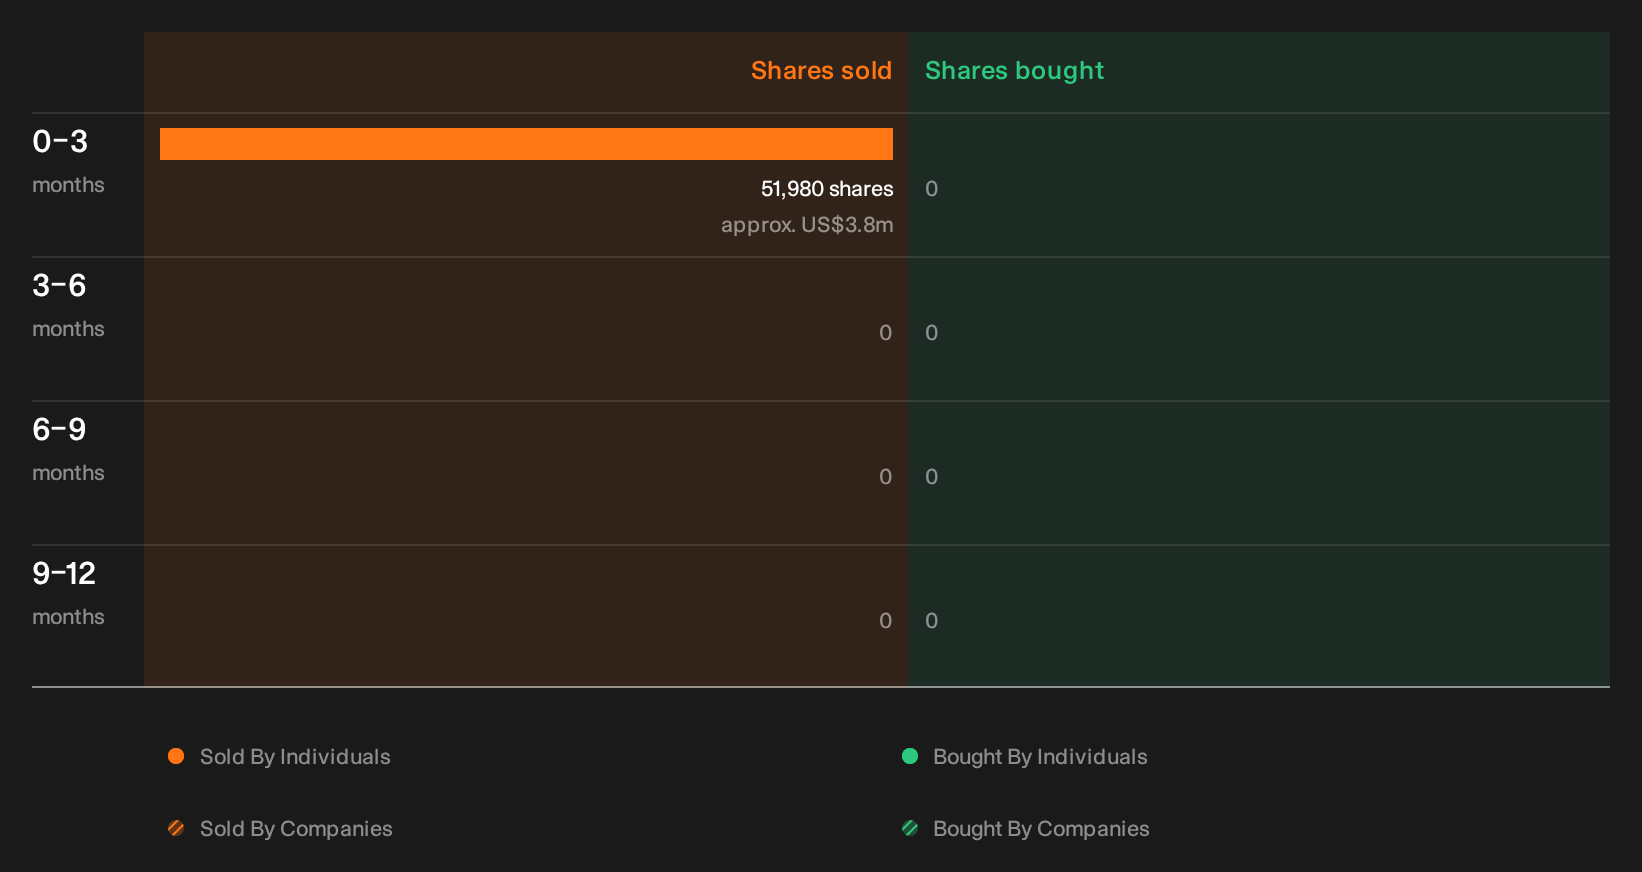
Affirm Holdings' story on returns and pricing is only part of what matters, because recent insider share activity has also been flagged by our checks, and the individuals involved, the scale and what it might signal are still for you to unpack. See the recent insider selling flagged for Affirm Holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com