


How Real World Ablation Data Will Impact Medtronic Stock (MDT)
- Medtronic reported positive real world registry data for its Affera Mapping and Ablation System with Sphere-9 catheter and PulseSelect PFA System, with high acute success and low major complication rates across more than 2,200 atrial fibrillation patients and 46 ventricular tachycardia patients enrolled globally.
- The breadth of prospective registry data across multiple regions and complex arrhythmia types gives investors a clearer view of how Medtronic’s cardiac ablation technologies perform in everyday practice rather than only in tightly controlled trials.
- We will now look at how Medtronic’s investment narrative could be influenced by stronger real world outcomes for its cardiac ablation portfolio.
Scan how Medtronic’s real world cardiac ablation results compare with peers by reviewing a hand picked 34 healthcare AI stocks that are also tying medical devices to advanced data driven care.
Medtronic Investment Narrative Recap
To own Medtronic, you need to believe the shift toward higher vitality cardiac and neuromodulation therapies offsets slower spots like Structural Heart and the lower margin Diabetes portfolio. The real world ablation data fits that view by reinforcing that cardiac procedures can support steadier utilization and, by extension, recurring device and service revenue.
The key near term swing factor is still execution on portfolio reshaping and mix, particularly whether higher growth but lower margin units keep diluting gross margin gains from pricing and cost work. These ablation results alone do not change that risk, although they slightly ease concerns that Cardiac Ablation Solutions growth might come with unacceptable safety trade offs.
The PulseSelect and Sphere 9 registry results speak directly to one of Medtronic's core catalysts, the push to build a larger, procedure driven cardiac ablation franchise that can compound over time as installed systems and physician familiarity increase. High acute success and low major complication rates in routine practice help support continued adoption by electrophysiologists.
On the flip side, mix matters. Cardiac Ablation Solutions is described as a lower margin business, so even strong uptake can pressure gross margins if Structural Heart or other higher margin cardiovascular lines lag. That is where the news is most relevant for investors: it supports the demand side of the catalyst while leaving the margin trade off and broader portfolio underperformance risks very much in play.
How Current Expectations Frame Medtronic’s Cardiac Ablation Upside
Analysts currently bake a fairly steady glide path into Medtronic’s story, with revenue modeled to grow by 4.4% each year over the next three years and profit margins shifting from 13.9% today to 16.7% by 2029. Consensus earnings are projected to move from US$5.2b currently to about US$7.1b, with a more cautious band down at US$6.4b. This effectively asks investors to underwrite a materially higher profit pool while accepting some dispersion in outcomes. Against that backdrop, cleaner real world data in cardiac ablation does not rewrite the earnings script on its own. However, it does speak to how comfortably Medtronic might meet those expectations if procedure volumes and physician confidence in Affera and PulseSelect systems stay supportive.
On valuation, the current set of forecasts implies that by 2029 Medtronic would be generating US$42.8b of revenue and US$7.1b of earnings while trading on a P/E of 23.8x, up from 21.3x today and slightly below the broader US medical equipment peer multiple of 24.7x. That profile asks you to see the stock as capable of modest multiple expansion on higher margins and bigger absolute earnings, without requiring a premium to the sector. Stronger real world performance in the ablation portfolio mainly affects how credible those 2029 numbers feel, rather than changing the math itself, since the same revenue and profit targets can be supported by a broader mix of devices and procedures if cardiac ablation continues to prove usable and safe in routine care.
Medtronic's narrative projects US$42.8b revenue and US$7.1b earnings by 2029. This setup assumes 4.4% yearly revenue growth and an earnings increase of about US$1.9b from current earnings of US$5.2b.
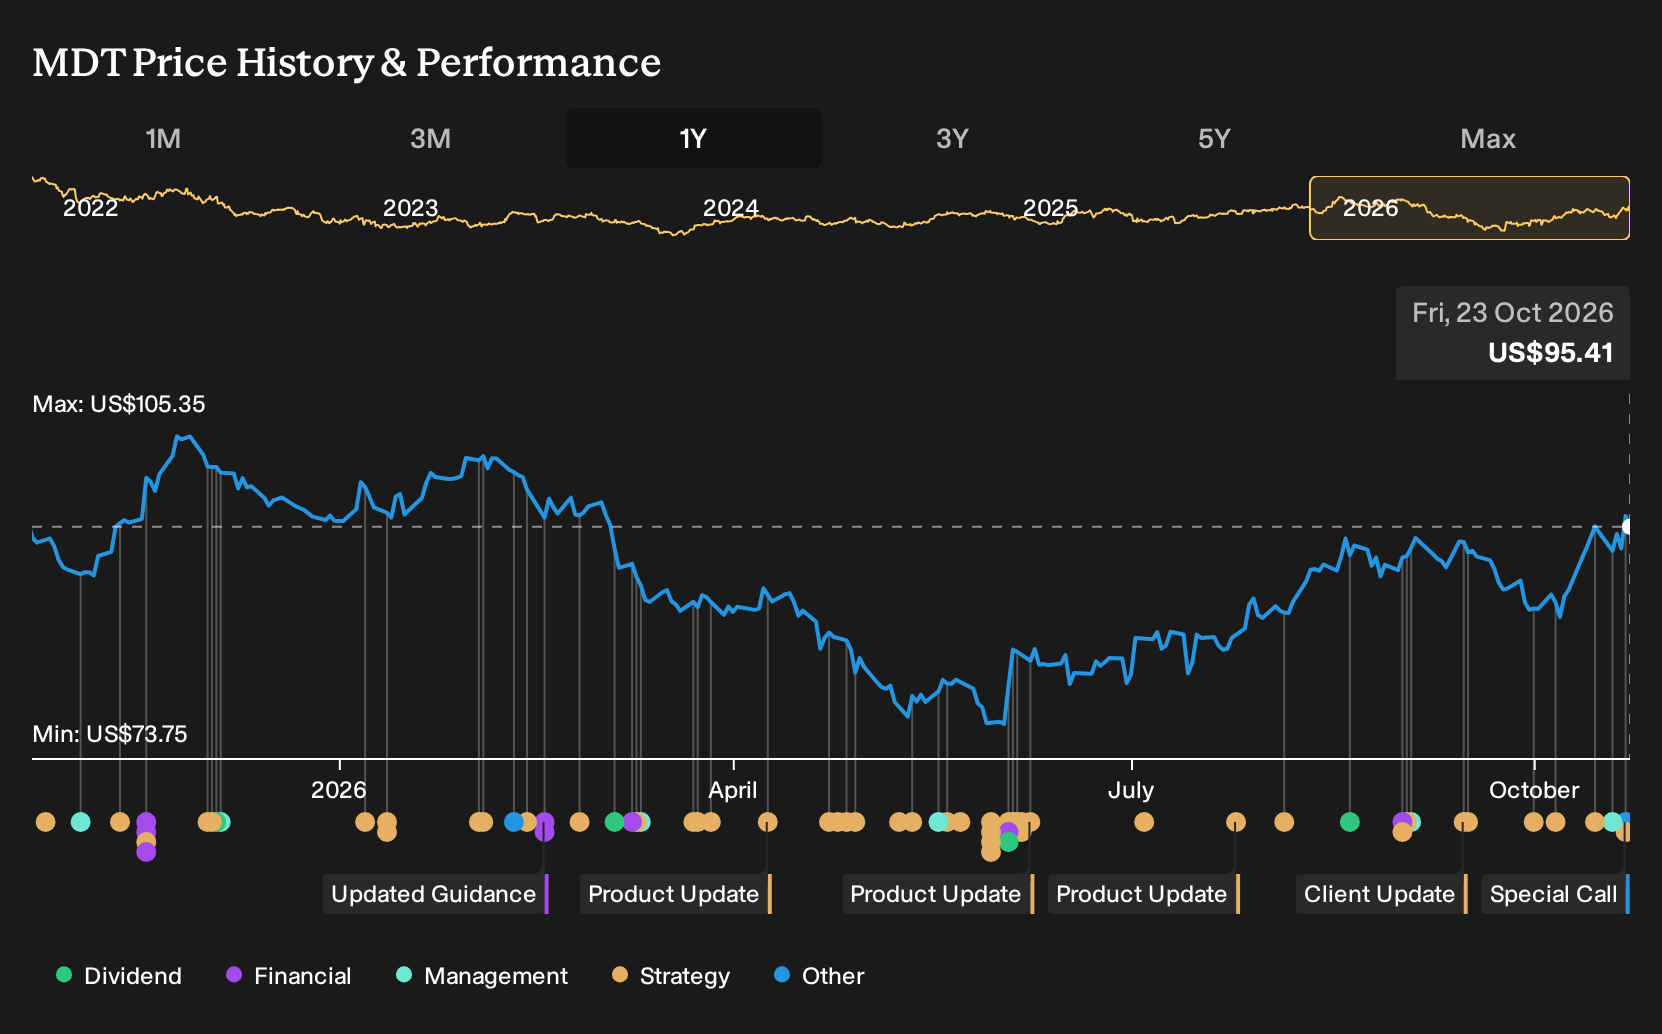
Discover how Medtronic's fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One optimistic angle on Medtronic focuses on how fast Cardiac Ablation Solutions could scale. The most bullish analysts were already penciling in 6.6% annual revenue growth and earnings of about US$7.1b by 2029, versus roughly US$4.8b today. That view leaned heavily on Affera and Sphere-9 adoption even before this new registry data. You may want to compare these higher expectations with more cautious forecasts and decide which storyline feels closer to your own read of the company.
Explore 8 other Medtronic fair value estimates, including one that suggests as much as 21% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Medtronic research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Medtronic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Medtronic's overall financial health at a glance.
Looking For More Investment Ideas Beyond Medtronic?
If you want to stress test your Medtronic view against alternatives, it can help to scan other companies with clear financial stories using the Simply Wall St Screener.
- For investors who care most about resilience, review a curated set of 30 resilient stocks with low risk scores that keep risk scores in focus.
- If income matters to your plan, check out a group of 5 dividend fortresses that combine higher yields with detailed payout data.
- When you want quality without overpaying, scan through a 29 high quality undervalued stocks that filters for stronger fundamentals at more modest prices.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com