


Where Papa John's International Goes After A 64% Drop
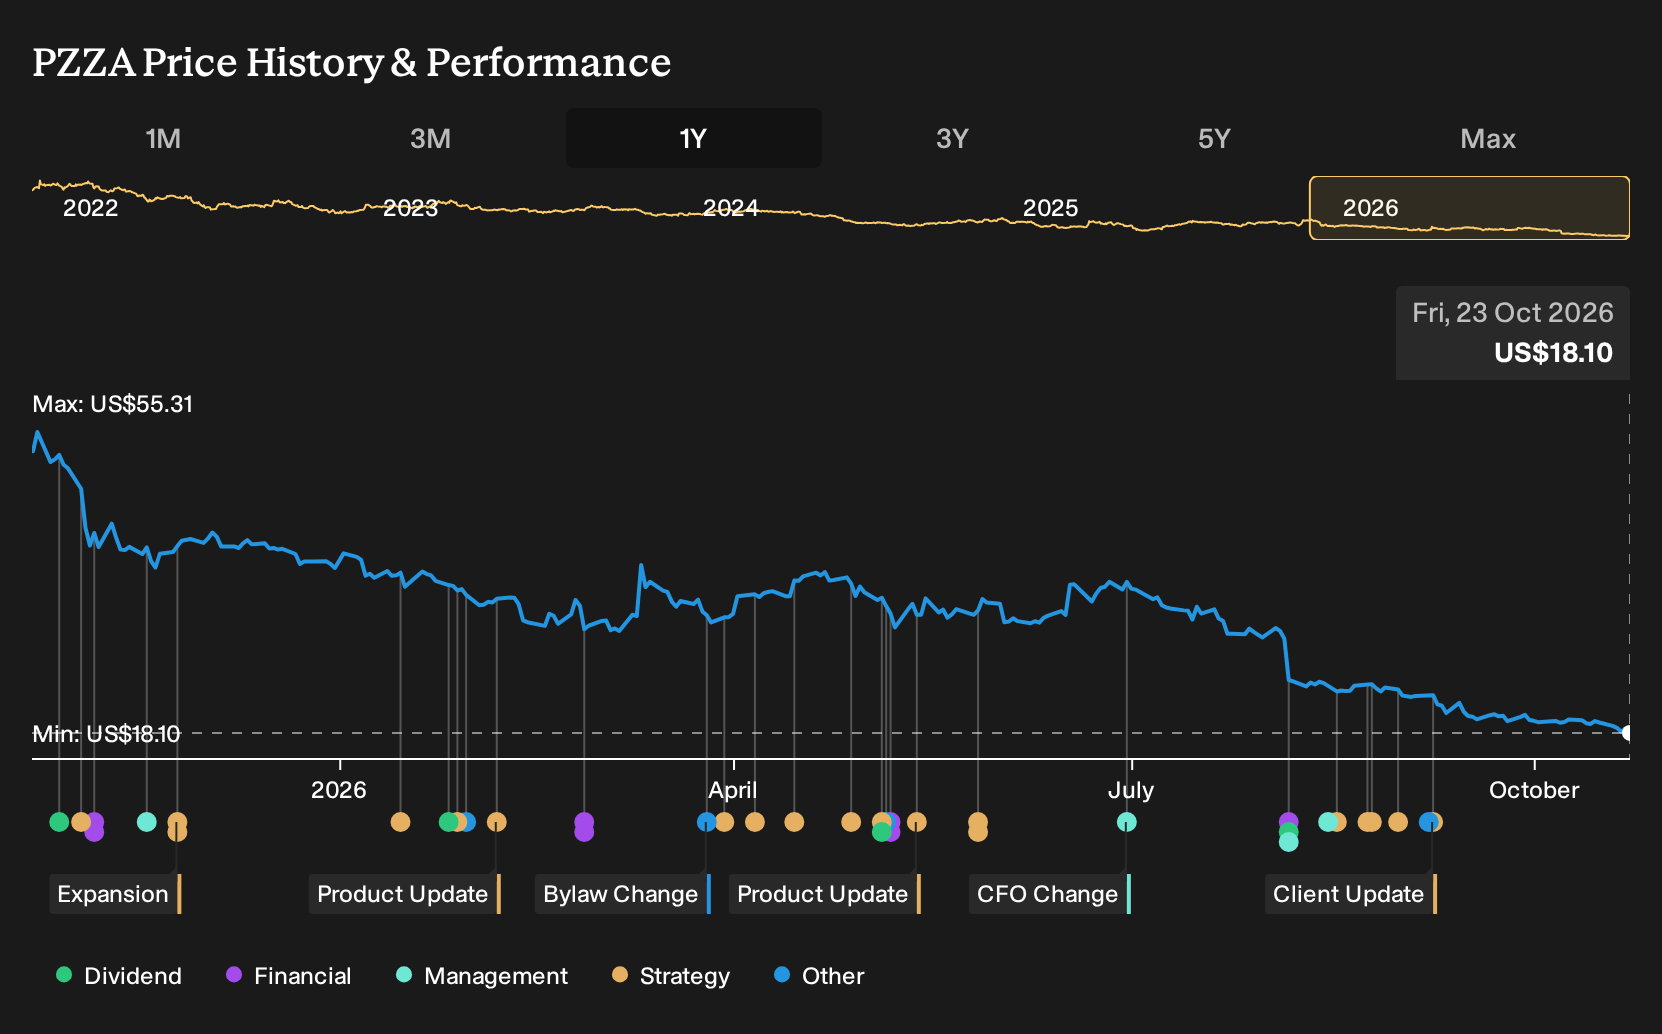
Papa John's International has been juggling takeover talks, a fresh class action lawsuit and a dividend suspension after reporting weaker North American sales and softer profitability. For Papa John's International shareholders, the loss over the past year was 63.6%, including dividends. If you had bought on the back of the bullish or bearish research in October 2025, how should you now weigh those earlier claims against a business that just pulled its dividend and faces legal scrutiny over past statements?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Papa John's International. Zero in on 29 high quality undervalued stocks for companies trading below our estimates.
The Argument Papa John's Investors Were Weighing Up
The shares cost US$52.92 at the start of the period, and anyone looking at Papa John's International then had to choose between two very different stories that both sounded reasonable.
On the optimistic side, the bull narrative put Fair Value at US$61.75. This was based on the idea that digital ordering, AI-driven personalization and faster international expansion could lift revenues by 2.7% a year while margins moved from 3.6% to 4.5%.
The bear narrative marked Fair Value at US$38. It argued that rising labor and commodity costs, store closures and a 0.3% annual revenue decline risked pushing profit margins down from 3.6% to 3.0%.
What The Results Changed For Papa John's International
Papa John's Q2 2026 update undercut the bullish story on accelerating earnings. Revenue moved from US$529.2m in Q2 2025 to US$482.4m in Q2 2026, net income slipped from US$9.3m to US$8.1m, and net margin edged down from 1.8% to 1.7%. The dividend suspension, weaker North American sales and class action filings all leaned toward the cautious case.
The key lesson is simple. When a thesis depends on margin expansion and steady sales, track reported net margin and segment revenue closely. Then test any upbeat guidance or narrative against those hard numbers each quarter.
What Today's Papa John's Share Price Already Assumes
Papa John's International now trades at US$18.1, after the stock fell 63.6% over the past year. The selected Narrative places its Fair Value above that level, based on a turnaround built more on digital ordering, AI tools and refranchising than raw store growth.
The key assumption for you to test is whether cost savings, restaurant closures and loyalty driven ordering can strengthen restaurant level economics enough to counter ongoing sales pressure.
"The main thing that has to go right is that supply chain savings, refranchising, and closure of about 300 weaker North America stores together rebuild restaurant-level economics enough to offset current sales declines and higher franchisee support spending."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Which Company Could Surprise You Next?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 33% below our estimate - targets surging AI data centre demand that challenges power and chip infrastructure.
- Company 2 - 24% below our estimate - embeds AI features across cloud, productivity, security and developer tools on one platform.
- Company 3 - 37% below our estimate - advises on technical failures and regulatory issues as products integrate AI and software.
That is three of the list. See the full list of 24 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com