


Is Bravida Holding (OM:BRAV) Fully Valued On Stronger Q3 Earnings And Backlog?
Q3 earnings put Bravida Holding in focus
Bravida Holding (OM:BRAV) moved back onto investor radar after reporting third quarter 2026 results, with higher sales, improved earnings per share and a stronger EBITA margin supported by a sizeable project backlog.
At a share price of SEK147.0, Bravida Holding has had a strong run, with a year-to-date share price return of 66.29% and a 1-year total shareholder return of 81.10%. This points to momentum that has been building rather than fading over a multi-year period, where the 3-year total shareholder return is 148.85%.
Scan beyond Bravida Holding and explore other infrastructure and construction specialists with solid fundamentals in our curated list of solid balance sheet and fundamentals (207 results)
After Bravida Holding’s sharp rerating and a backlog that now carries more earnings power, the question shifts: Does the current price still leave enough upside to justify fresh risk, or has most of the payoff already been pulled forward?
Most Popular Narrative: 0% Undervalued
The most followed narrative pegs Bravida Holding’s fair value at SEK147.71, almost identical to the latest close at SEK147.0. This implies the recent share price surge is roughly in line with the cash flow and earnings profile now on the table.
The growing portfolio of large data center projects across Norway, Finland, Sweden and Denmark, including multi year contracts with frame agreements and repeat clients, is set to convert record order backlog into higher installation revenue and a mix that supports EBITA margin expansion.
See why 10 investors see Bravida Holding as 0% undervalued.
Result: Fair Value of SEK147.71 (ABOUT RIGHT)
Still, the Bravida Holding story can break if order intake softens from current record levels or if fresh restructuring waves eat into EBITA and cash generation.
Find out about the key risks to this Bravida Holding narrative.
Another View on Bravida Holding’s valuation
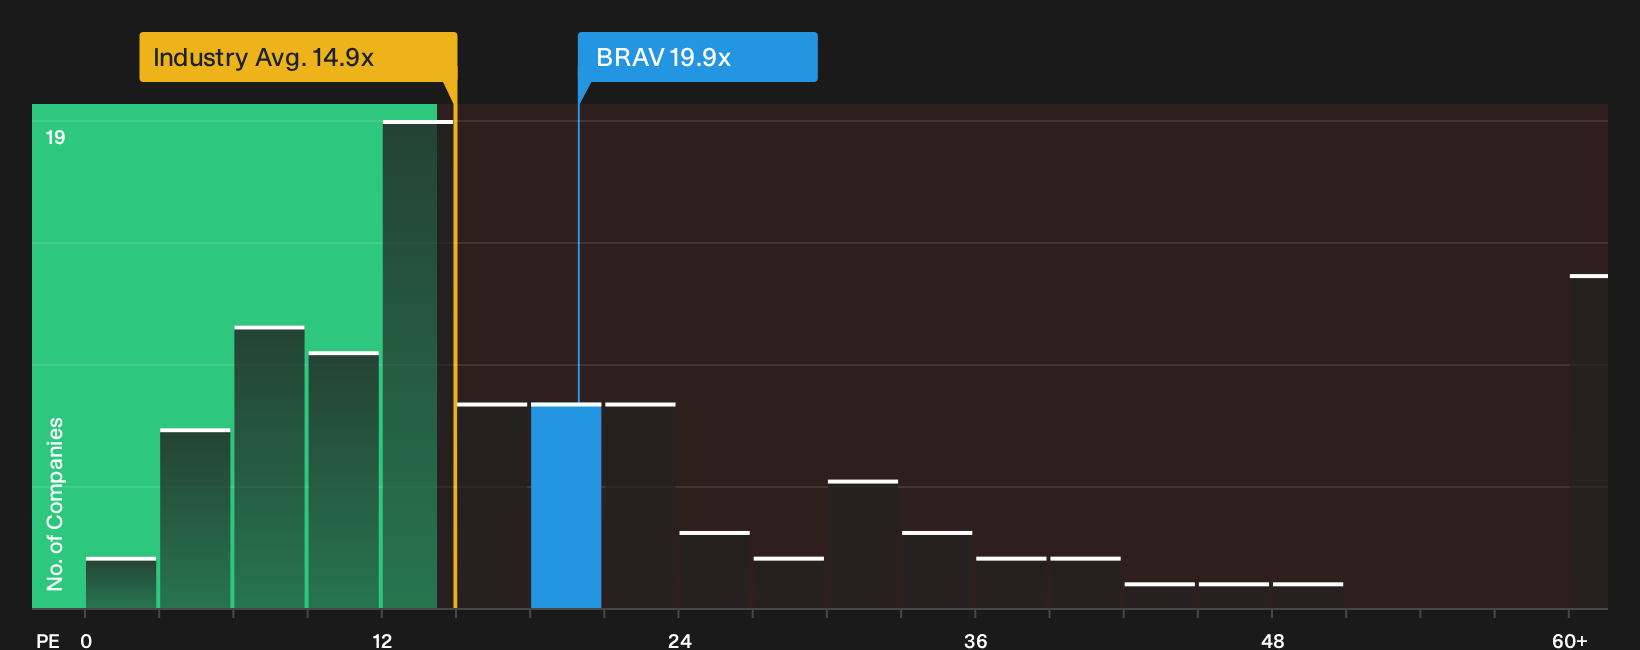
On simple earnings multiples, Bravida Holding does not look cheap. The stock trades on a P/E of 19.9x, above both the European Commercial Services average of 14.9x and the peer group at 18x, even though the fair ratio sits slightly higher at 20.3x. Is the market paying up for quality, or is this simply crowding in late?
To see how that price tag lines up with the earnings profile, valuation assumptions and fair ratio in more detail, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this read has left you sensing optimism around Bravida Holding but still unsure where you stand, move quickly and work through the data yourself. To see which factors investors are excited about, review the 4 key rewards
Looking for more investment ideas beyond Bravida Holding?
If Bravida Holding has sharpened your appetite for opportunity, let fresh data driven shortlists guide your next move before the market prices them in.
- Spot potential turnarounds early by scanning 122 elite penny stocks with strong financials that already show stronger balance sheets and improving financial quality.
- Zero in on quality at a measured price using our curated set of 194 high quality undervalued stocks that pair solid fundamentals with grounded valuations.
- Build a steadier income stream by reviewing 230 dividend fortresses that combine higher yields with business resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com