


Alarm.com Holdings (ALRM) Lifts 2026 Outlook As Fair Value Debate Gets Harder To Ignore
Why Alarm.com Holdings Raised Its 2026 Revenue Outlook
Alarm.com Holdings (ALRM) lifted its 2026 revenue forecast after strong SaaS and license momentum, coupled with a broader product lineup that has fed into fresh optimism around the company’s projected cash flows and valuation.
Recent trading has reflected that optimism. Alarm.com Holdings has logged a 25.2% year-to-date share price return and a 20.2% one-month share price return, while the one-year total shareholder return of 23.9% points to momentum that has been building rather than fading.
Scan hand-picked software and connected-device stocks showing similar SaaS momentum and potential valuation gaps with Alarm.com Holdings through the 29 high quality undervalued stocks.
Alarm.com Holdings has already rewarded early 2026 buyers, yet the current price still sits below both analyst targets and some cash flow estimates. Is most of the upside already in the rear-view mirror, or is it not yet fully priced in?
Most Popular Narrative: 1.8% Overvalued
Alarm.com Holdings closed at $64.14, slightly above the most followed fair value estimate of $63 that is based on a 9.16% discount rate and long term earnings assumptions. The gap is small, so the real question is whether the growth engines in that narrative still feel robust enough to justify paying a bit more than the modeled value.
Expansion of growth initiatives such as EnergyHub, commercial offerings and international operations, which represented roughly 35% of revenue in Q2 2026 and grew a little over 30% year over year, points to a larger contribution from these higher growth areas that can influence consolidated revenue and earnings beyond current guidance.
Find out how 2 investors see Alarm.com Holdings as 2% overvalued.
Result: Fair Value of $63 (OVERVALUED)
Still, tariff related pressure on hardware and the risk of slower new account growth could challenge the upbeat Alarm.com Holdings narrative that investors are leaning on.
Find out about the key risks to this Alarm.com Holdings narrative.
Another View: SWS DCF Signals a Deeper Discount
The analyst narrative describes Alarm.com Holdings as slightly overvalued at $64.14 versus a $63 fair value, yet the SWS DCF model presents a very different perspective. On that cash flow view, the stock trades at $64.14 against an estimated value of $100.90, which frames Alarm.com as trading at a steep discount. This raises a key question: does the more accurate picture come from a near inline target price or from a wide DCF gap?
For a closer look at how those projected cash flows were modeled and discounted, Look into how the SWS DCF model arrives at its fair value.
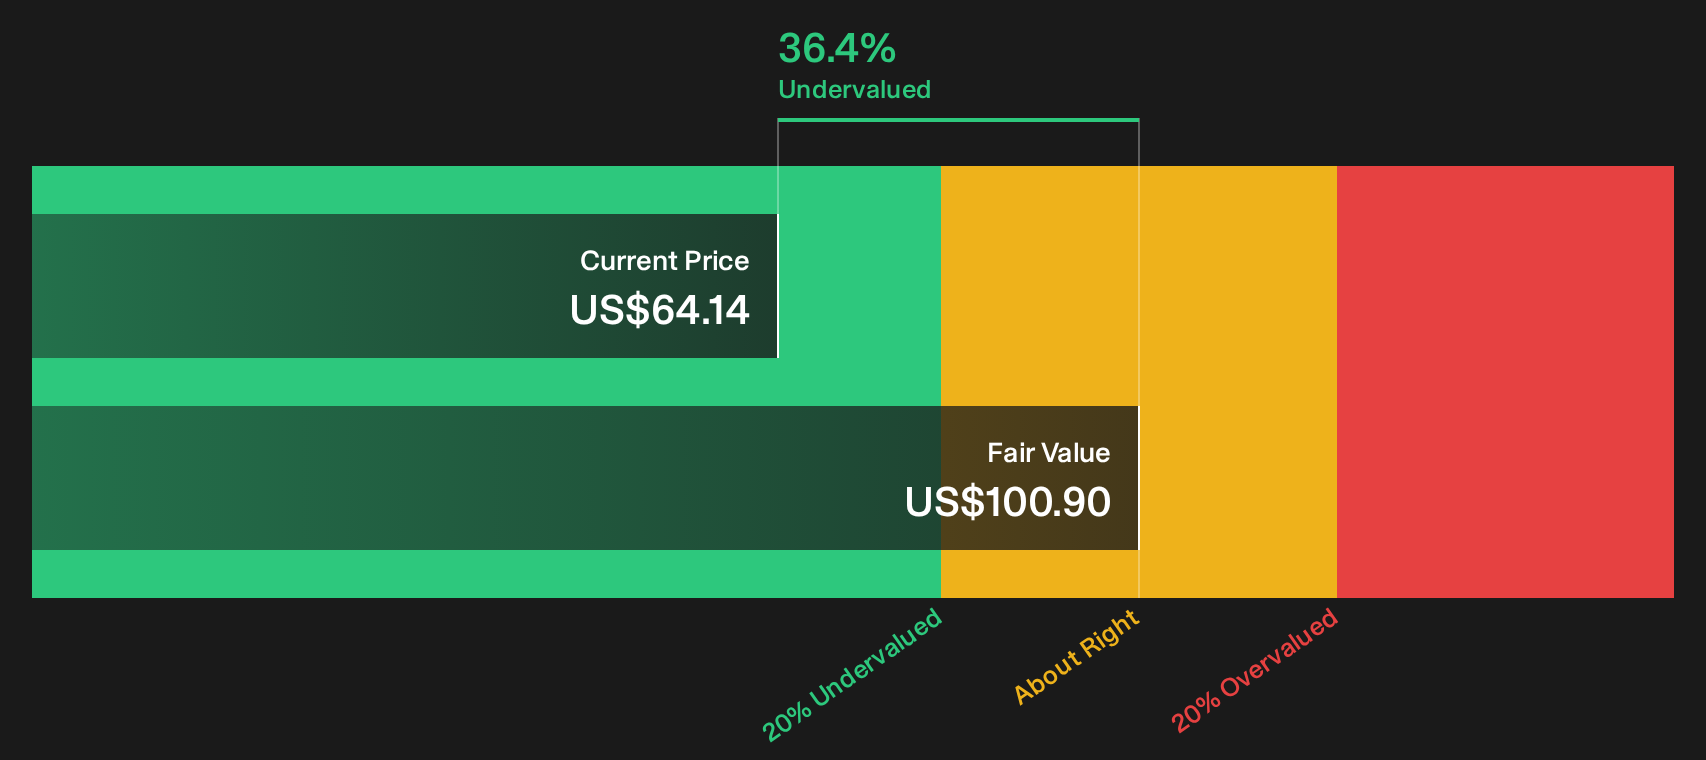
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Alarm.com Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Alarm.com Holdings story so far. Act while the data is fresh and pressure test both sides of the argument using the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Alarm.com Holdings?
Alarm.com Holdings might already be on your radar, but the next opportunity could be sitting in plain sight if you scan a wider watchlist today.
- Target resilience by checking companies with dependable finances and low risk scores through the 30 resilient stocks with low risk scores.
- Hunt for potential mispricings by reviewing a curated set of quality businesses that appear underappreciated using the 29 high quality undervalued stocks.
- Stack potential income and strength together by scanning a 5 dividend fortresses that pairs higher yields with robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com