


3 Rare Earth Stocks Investors May Revisit Before The Pentagon’s 2027 Ban
The Pentagon’s 2027 ban on Chinese-origin rare earths in U.S. weapons systems turns an obscure materials niche into a real fork in the road for investor capital. Supply chains are being rewired on a deadline, and that kind of forced change can reward some stocks and sideline others. This article walks through three companies exposed to that policy shift and explains what the news could mean for their future risk and reward.
The three stocks reviewed below are only a sample, and the full screen surfaced 22 more U.S. defense-oriented rare earth and critical minerals companies with similarly detailed stories that are not covered here. If you want to move straight from idea to action, head into the U.S. Defense-Oriented Rare Earths and Critical Minerals screener to identify, analyze, and prioritize the highest-conviction candidates for your watchlist.
Amaroq (AMRQ.F)
Overview: Amaroq is a Toronto based miner focused on gold and critical minerals exploration in Greenland, a U.S. aligned Arctic jurisdiction.
Operations: The business generates about CA$80 million from acquiring, exploring, and developing mineral properties in Greenland, concentrated in gold and critical minerals.
Market Cap: US$625 million
Amaroq provides direct exposure to Greenland gold and critical minerals at a time when Western governments are seeking non Chinese sources for sensitive materials. The miner combines producing gold assets with early stage rare earth and critical metals prospects in a jurisdiction closely watched by U.S. and European buyers. Changes in how future demand is contracted could significantly influence investment outcomes.
Those contracting shifts could quickly separate hype from resilience, so review the 3 key rewards and 2 important warning signs (1 is major!) to see how Amaroq’s upside compares with its biggest pressure points.

Foraco International (TSX:FAR)
Overview: Foraco International is a global contract driller, sinking holes for mining projects that target critical minerals, rare earths, and gold.
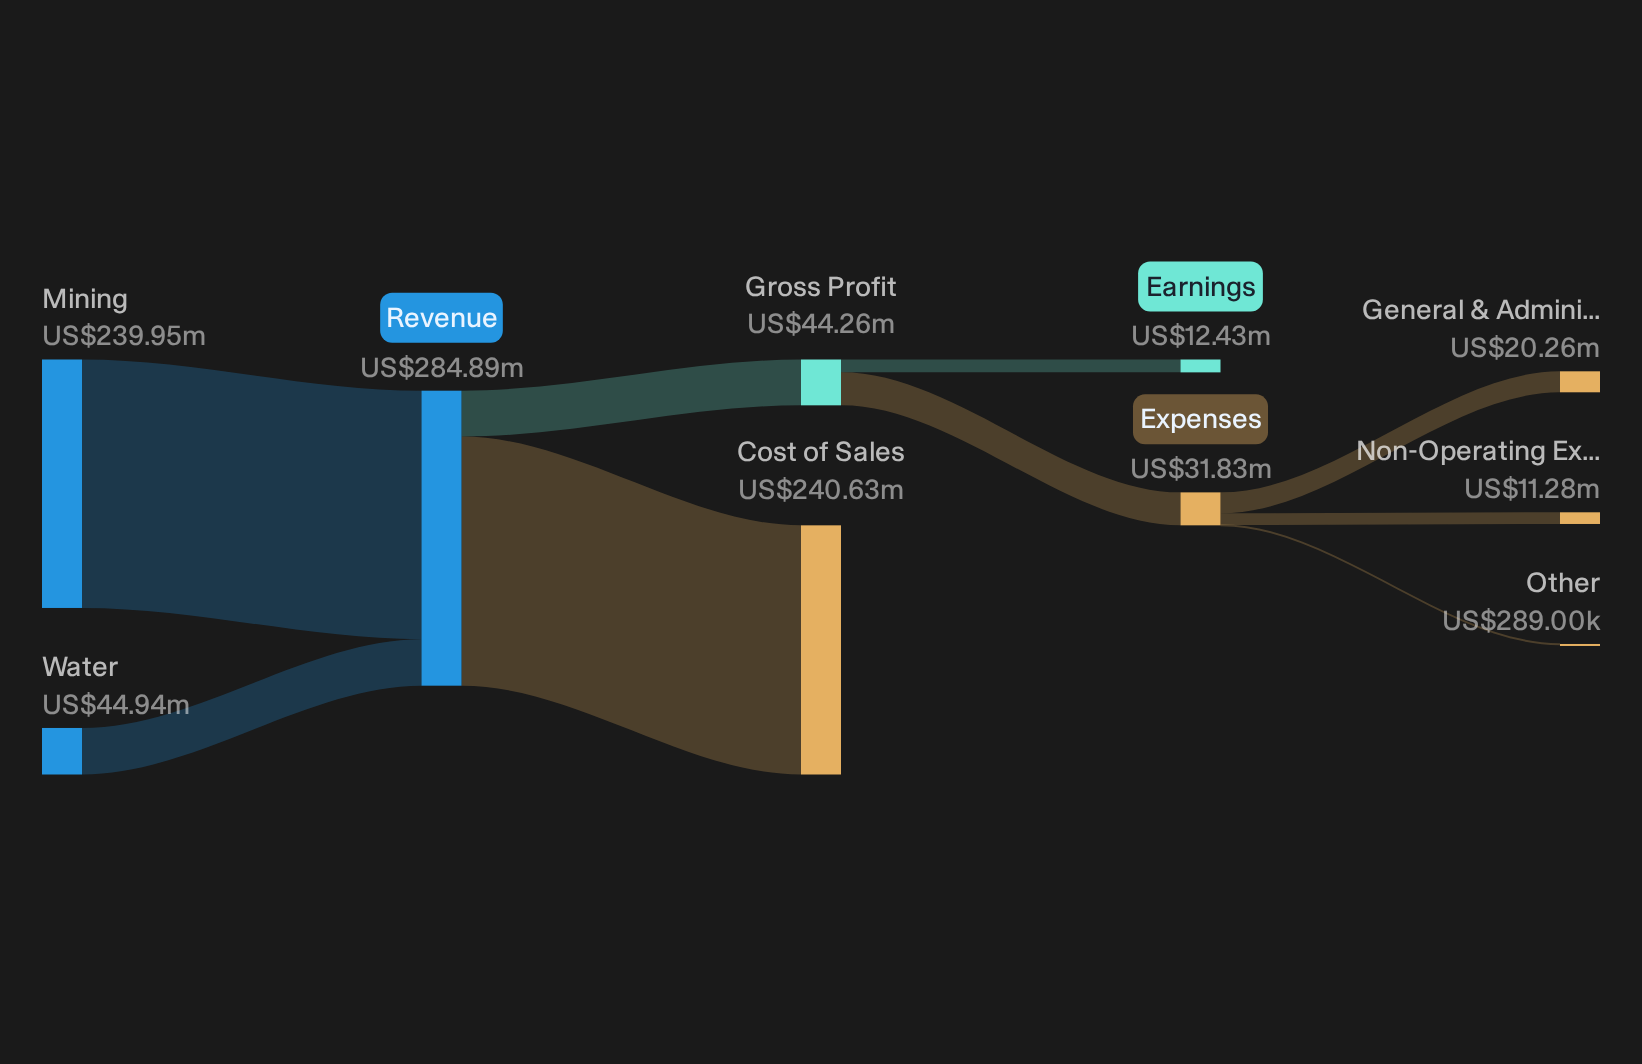
Operations: The business generates about US$240 million from mining drilling and US$45 million from water projects, with activity spread across Asia Pacific, North America, South America, and EMEA.
Market Cap: CA$234 million
Foraco International matters for this rare earths and critical minerals theme because rigs are the pickaxes of modern supply chains, and the company is positioned where new non Chinese deposits move from maps to mine plans.
"The accelerating global demand for copper, gold and metals linked to electrification and clean energy continues to underpin a high level of nonferrous exploration budgets. If higher labor, consumable and mobilization costs are not effectively offset by contract repricing, the company could see weaker profitability and lower earnings than implied by the current narrative."
What really moves the needle for Foraco International is how one shifting pressure on its drilling contracts ultimately affects shareholder outcomes.
If that contract tension is what catches your eye, read the full narrative for Foraco International to see how drilling demand, pricing power, and execution risk could be decoupling.
Integra Resources (TSXV:ITR)
Overview: Integra Resources is a Vancouver based precious metals producer exploring and developing gold and silver projects across the U.S. Great Basin.
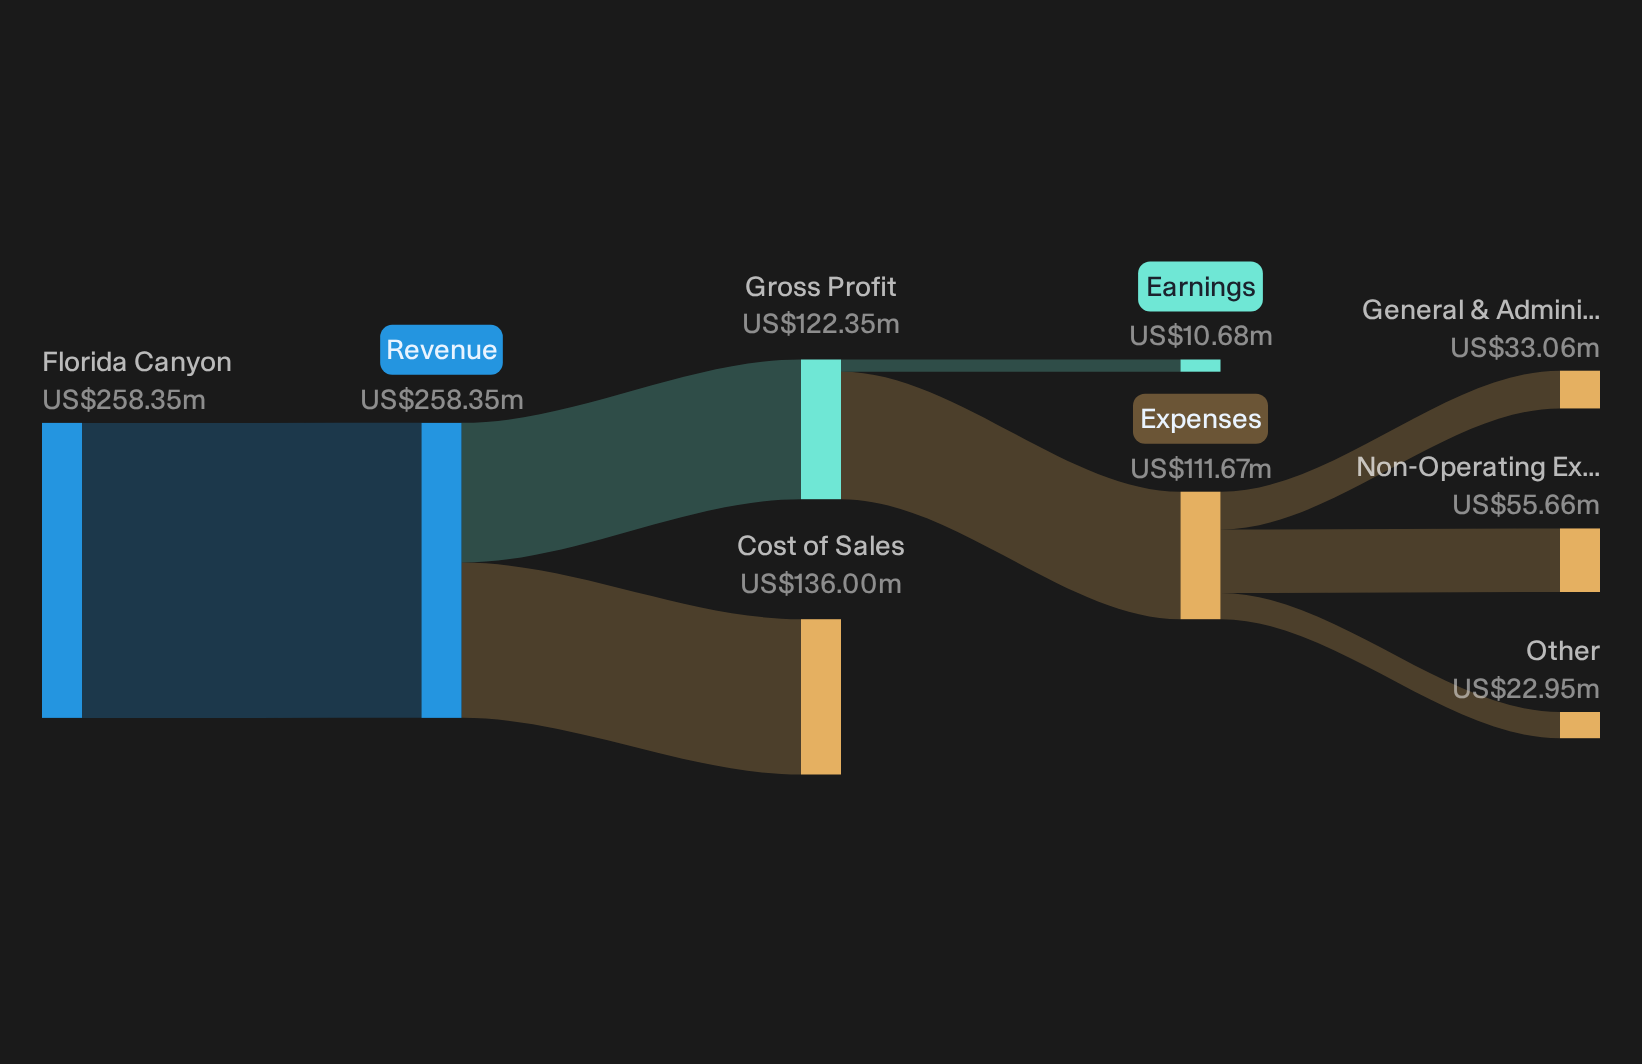
Operations: The business currently generates about $258 million from the Florida Canyon mine, with all reported revenue attributed to Canada.
Market Cap: CA$629 million
Integra Resources matters in this defense oriented rare earths and critical minerals screen because its Great Basin footprint ties precious metals development to the same U.S. permitting, infrastructure and policy momentum reshaping critical mineral supply chains.
"Although Integra Resources highlights an 8 year mine plan and sizeable free cash flow potential at Florida Canyon, the recent mine site AISC of US$3,310 per ounce and cash costs of US$2,422 per ounce in Q1 2026, both above the guided ranges, point to a cost base that could stay structurally higher and compress net margins if input pressures persist."
What ultimately matters for Integra Resources is how a single moving piece in its Great Basin build out reshapes future cash generation.
If that single moving piece has you thinking about what could still go right for Integra Resources, read the full narrative for Integra Resources to see whether current worries are masking a stronger setup.
Seeking Alternatives Before Momentum Flies
Fresh opportunities can move from quiet to crowded quickly. Before the next breakout run gets caught by the crowd, consider these under the radar ideas while it matters and aim to move early.
- Scan for fast moving underpriced operators that still show disciplined balance sheets with the 29 high quality undervalued stocks before stronger momentum pulls them onto everyone else’s radar.
- Track where real cash generation meets AI buzz by reviewing the 39 profitable AI stocks that aren't just burning cash and focus on businesses that are not just burning capital for headlines.
- Review the curated 35 elite gold producer stocks for ideas in the metals space and concentrate on producers already structured for operational leverage if momentum improves.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com