


Capital Southwest (CSWC) Draws Value Interest As Deal Flow Supports The Undervalued Narrative
Capital Southwest Stock Performance Snapshot
Capital Southwest (CSWC) has drawn investor attention after recent price weakness, with the share price edging down over the past week and month, and recording a similar decline over the past 3 months.
Despite the recent pullback, Capital Southwest shows mixed momentum, with the 1-day, 7-day, 30-day and 90-day share price returns all in decline, while the year-to-date share price return is slightly positive and the 1-year total shareholder return of 20.86% points to stronger longer term gains.
Scan beyond Capital Southwest and line up other potential rebound candidates using our curated list of 29 high quality undervalued stocks, which combine balance sheet strength with disciplined cash generation.
For Capital Southwest, the recent dip can signal either pressure on the underlying lending portfolio or just cooler sentiment after a strong year. The valuation work now is to separate those two forces.
Most Popular Narrative: 11.6% Undervalued
On the most followed narrative, Capital Southwest screens as undervalued, with a fair value estimate of $25.30 against a last close of $22.37. This puts the recent pullback in a different light for long term holders sizing up risk and reward.
Robust private equity sponsor relationships and rising lower middle market deal screens, with management reviewing roughly 1,300 opportunities over the last 12 months and committing US$762 million in FY26 plus US$222 million in Q1 FY27, support the view that Capital Southwest can keep adding income producing assets that underpin revenue and earnings.
See why 37 investors see Capital Southwest as 12% undervalued.
Result: Fair Value of $25.30 (UNDERVALUED)
Still, analyst expectations can be knocked off course if spread compression persists and if ongoing share issuance through the ATM program dilutes per share earnings power.
Find out about the key risks to this Capital Southwest narrative.
Another View: Capital Southwest Through The P/E Lens
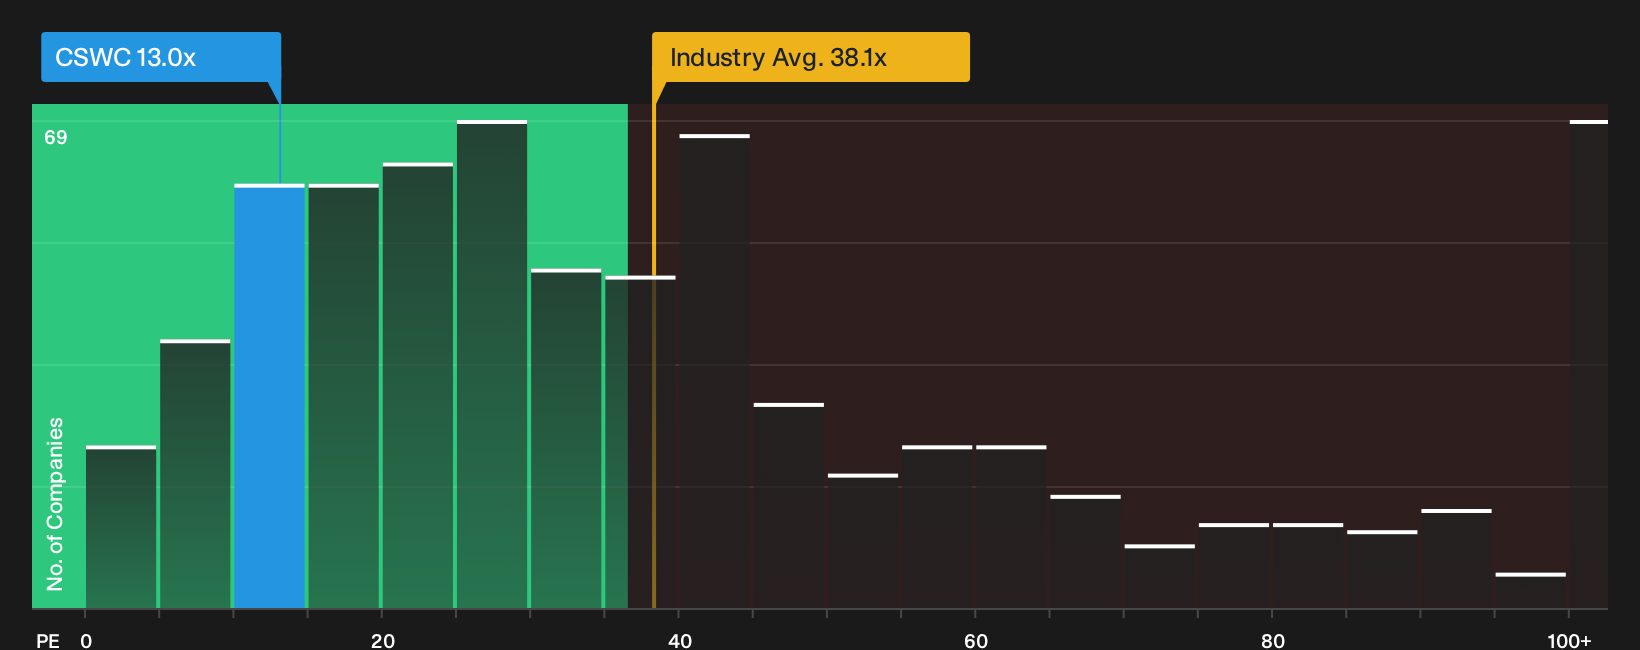
Look at Capital Southwest through a simple P/E filter and the picture is less generous. The stock trades at about 13x earnings, which is above the estimated fair ratio of 11.4x and also slightly higher than close peers at 12.5x. That gap can signal extra valuation risk if returns slip or growth expectations soften.
For a closer look at what this pricing gap might mean in practice, including how it could close over time, see the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals can feel uncomfortable, especially when Capital Southwest shows both pressure and promise in the same snapshot. Consider your options before the narrative hardens and weigh the balance of concerns and upsides for yourself by checking the 3 key rewards and 3 important warning signs
Looking For More Investment Ideas Beyond Capital Southwest?
If Capital Southwest has you thinking harder about value and risk, do not stop here. Line up fresh ideas now so you are not reacting later.
- Target sturdier portfolios by scanning a list of solid balance sheet and fundamentals (24 results) that can help you focus on businesses backed by stronger finances and cleaner fundamentals.
- Hunt for mispriced opportunities with the 21 high quality undiscovered gems, where lesser known stocks with strong numbers might not yet be fully appreciated by the market.
- Dial down portfolio stress by checking a 30 resilient stocks with low risk scores that filters for companies with calmer risk profiles and more resilient characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com