


Will Q3 Earnings Resilience Change Thule Group (OM:THULE) Narrative
- Thule Group reported Q3 2026 sales of SEK 2,603 million and net income of SEK 393 million, with basic earnings per share from continuing operations of SEK 3.65, and maintained a 20% EBIT margin alongside solid cash generation.
- The Active with Kids and Dogs category, together with focused efficiency programs and champion product execution, helped support earnings quality despite weak RV demand and a sluggish North American market.
- We will now look at how Thule Group's 20% EBIT margin in Q3 2026 could reshape the discussion around profitability.
Thule Group Investment Narrative Recap
For Thule Group, the core belief is that focused product categories, higher margin channels and efficiency work can support profitability even when demand is patchy. The Q3 2026 print, with a 20% EBIT margin and cash generation described as strong, supports that view. The near term swing factor is execution in Active with Kids and Dogs and Sports & Cargo, while RV headwinds and a soft North American market limit top line help.
The biggest immediate risk is still weakness in RV related volumes and cautious wholesalers in North America, which management already flags as a drag. With factories running at about 70% capacity after earlier expansion, a prolonged volume lull could keep utilization and net margins under pressure, even if Thule Group continues to push mix and cost programmes.
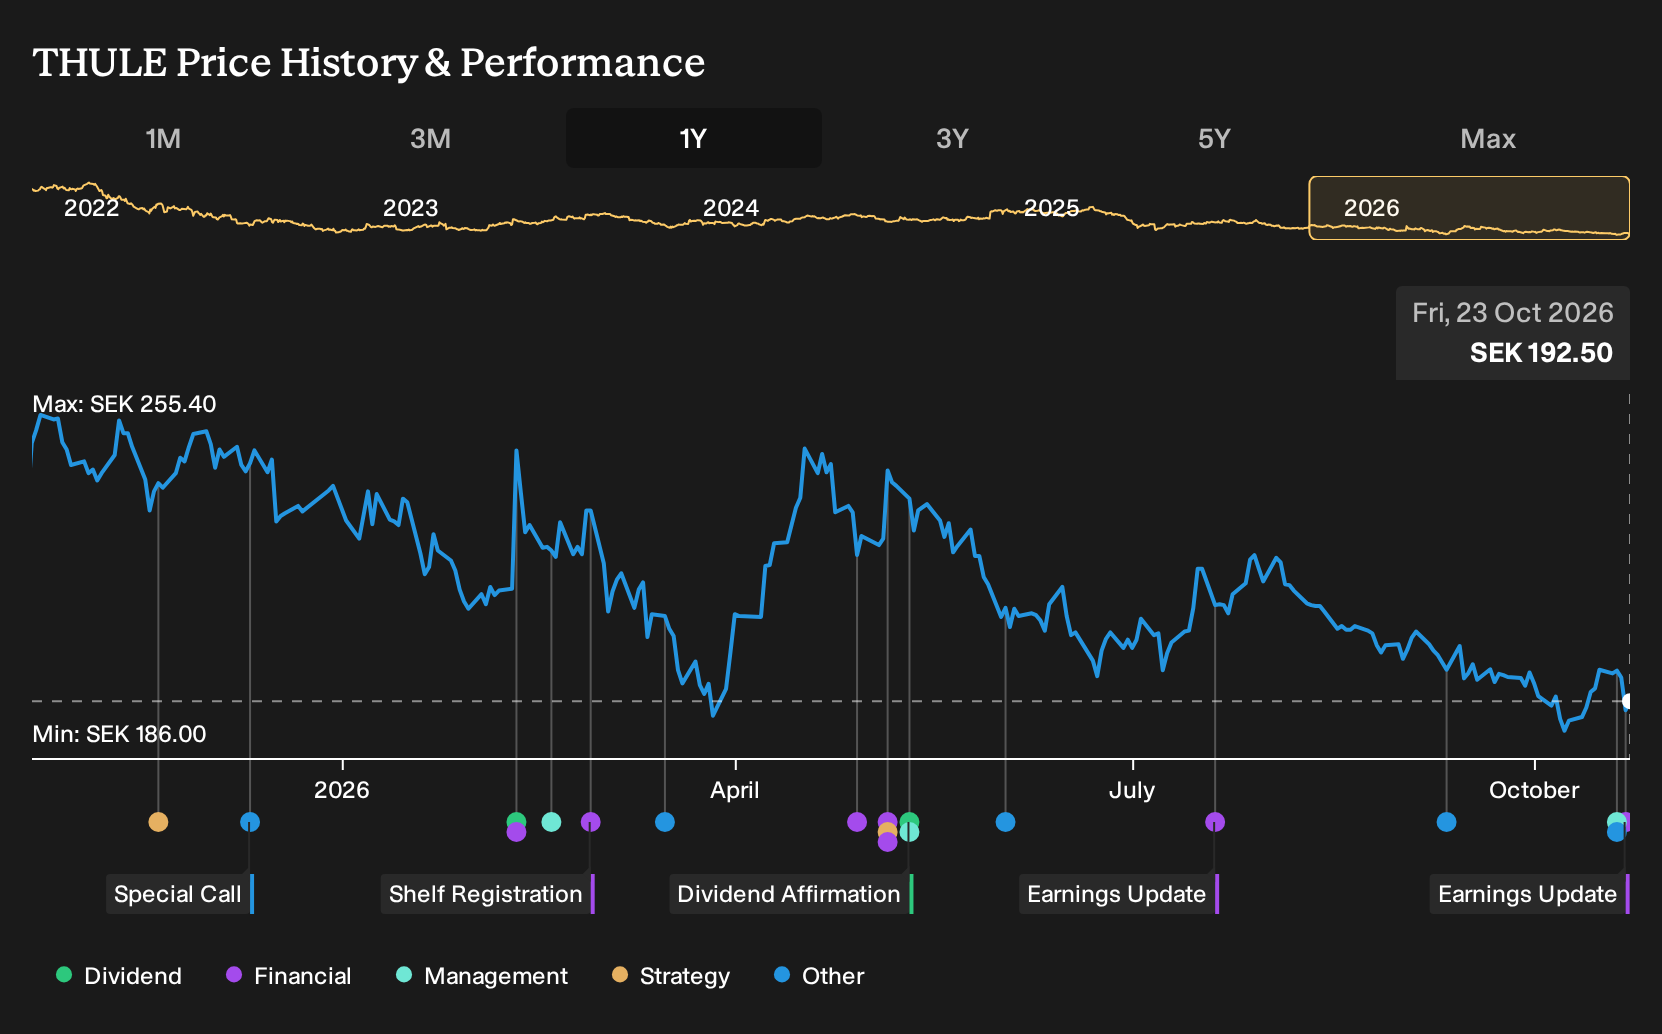
The most relevant development around this story is the Q3 2026 earnings release on 22 October. Sales of SEK 2,603 million and net income of SEK 393 million for the quarter, plus nine month earnings of SEK 1,223 million, show that Thule Group is holding profitability and cash generation while leaning harder on champion categories and efficiency efforts.
That matters for catalysts because the thesis leans heavily on margin quality rather than fast revenue expansion. Stable basic EPS from continuing operations at SEK 3.65 in the quarter and SEK 11.34 for nine months, alongside a 20% EBIT margin, gives management more room to keep investing in the Active with Kids and Dogs ecosystem, direct channels and automation projects, even as RV and North American demand remain key watchpoints.
Thule Group's narrative projects SEK 12.2b revenue and SEK 1.7b earnings by 2029. This assumes 5.7% yearly revenue growth and an earnings increase of about SEK 0.5b from SEK 1.2b today.
Uncover why Thule Group's fair value indicates a 36% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One alternate view leans hard into Thule Group’s upside from underused factories. The most optimistic analysts were already working with revenue of about SEK 12.6b and earnings near SEK 1.8b by 2029, before this Q3 update. You can use those richer assumptions as a contrast point and decide which story feels closer to your own expectations.
Explore 2 other Thule Group fair value estimates, including one that suggests as much as 101% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Thule Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Thule Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Thule Group's overall financial health at a glance.
Looking for more investment ideas beyond Thule Group?
Once you have formed a view on Thule Group, it can help to line that up against a wider watchlist of potential opportunities using the Simply Wall St Screener.
- If you want potential mispricing backed by fundamentals, scan a focused set of 194 high quality undervalued stocks that combine quality traits with attractive valuations.
- If downside risk control matters most to you, start with a curated group of 221 resilient stocks with low risk scores that score well on stability and balance sheet strength.
- If you prefer finding lesser known opportunities earlier in their journey, broaden your search with a hand picked pool of 612 high quality undiscovered gems that still have relatively limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com