


Asian Growth Companies With Strong Insider Ownership October 2026
In October 2026, Asian markets have been navigating a landscape marked by global volatility driven by AI investment concerns and fluctuating oil prices. Amid this backdrop, growth companies with high insider ownership in Asia are garnering attention for their potential resilience and strategic alignment, offering investors a unique perspective on navigating uncertain times.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.8% |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| Meiko Electronics (TSE:6787) | 19.2% | 34% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 45.3% |
| HUMAN MADE (TSE:456A) | 29.1% | 28.7% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gold Circuit Electronics (TWSE:2368) | 29.9% | 46.1% |
| Fulin Precision (SZSE:300432) | 11.7% | 66.5% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's take a closer look at a couple of our picks from the screened companies.
Smartsens Technology (Shanghai) (SHSE:688213)
Simply Wall St Growth Rating: ★★★★★★
Overview: Smartsens Technology (Shanghai) Co., Ltd. operates in the semiconductor industry, focusing on the design and development of CMOS image sensors, with a market cap of CN¥44.26 billion.
Operations: The company's revenue primarily comes from its Semiconductor Integrated Circuit Chips segment, which generated CN¥9.84 billion.
Insider Ownership: 23.3%
SmartSens Technology (Shanghai) is experiencing robust growth, with earnings projected to grow significantly over the next three years and revenue anticipated to increase by 21.5% annually, outpacing the Chinese market. The company recently raised CNY 3.17 billion through a private placement, enhancing its financial position for future expansion. SmartSens' innovative product offerings in automotive imaging solutions highlight its commitment to technological advancement, supporting its trajectory as a high-growth entity with substantial insider ownership influence.
- Navigate through the intricacies of Smartsens Technology (Shanghai) with our comprehensive analyst estimates report here.
- Our valuation report here indicates Smartsens Technology (Shanghai) may be undervalued.
Ingenic Semiconductor (SZSE:300223)
Simply Wall St Growth Rating: ★★★★★★
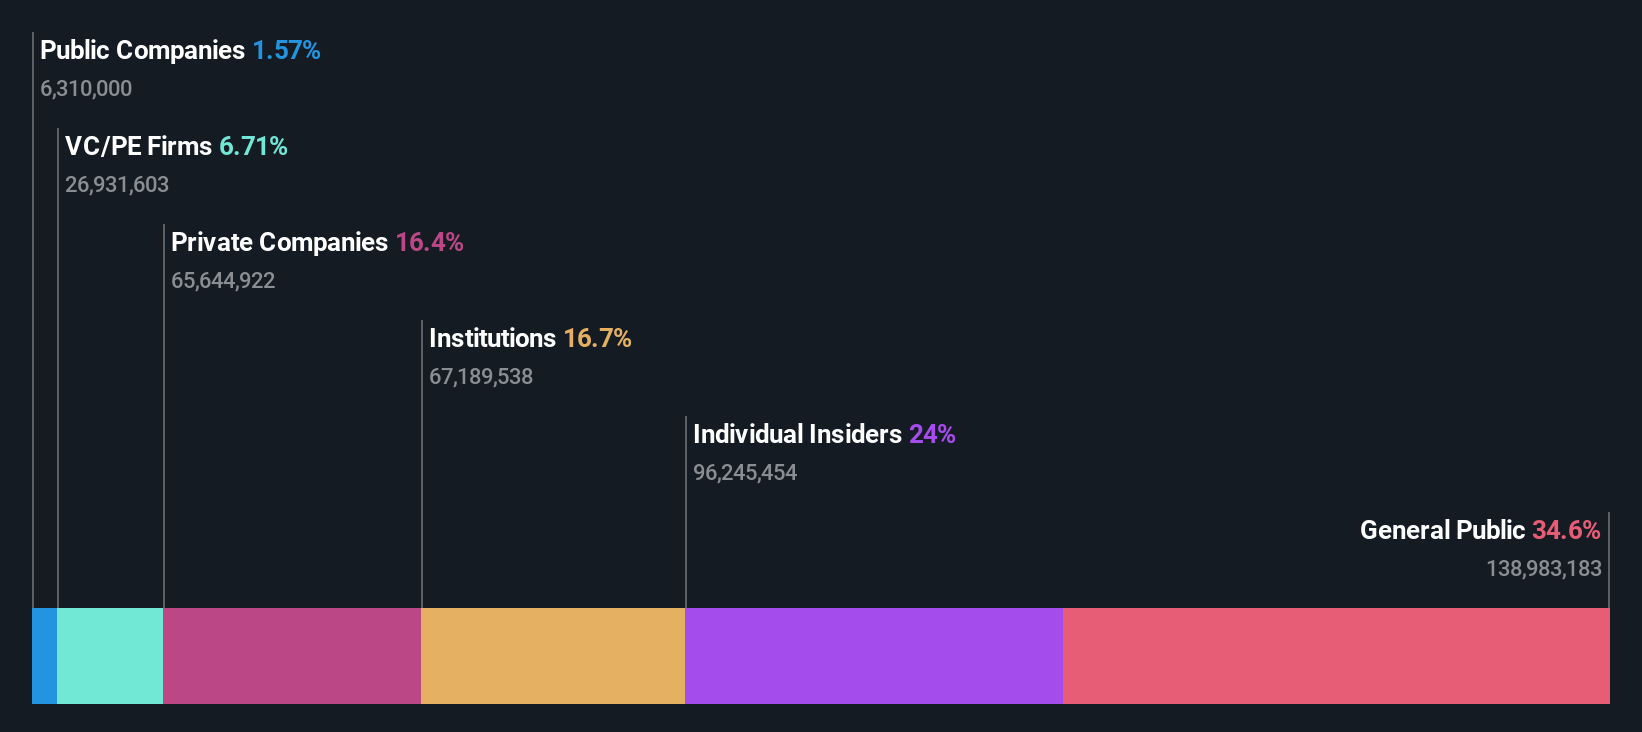
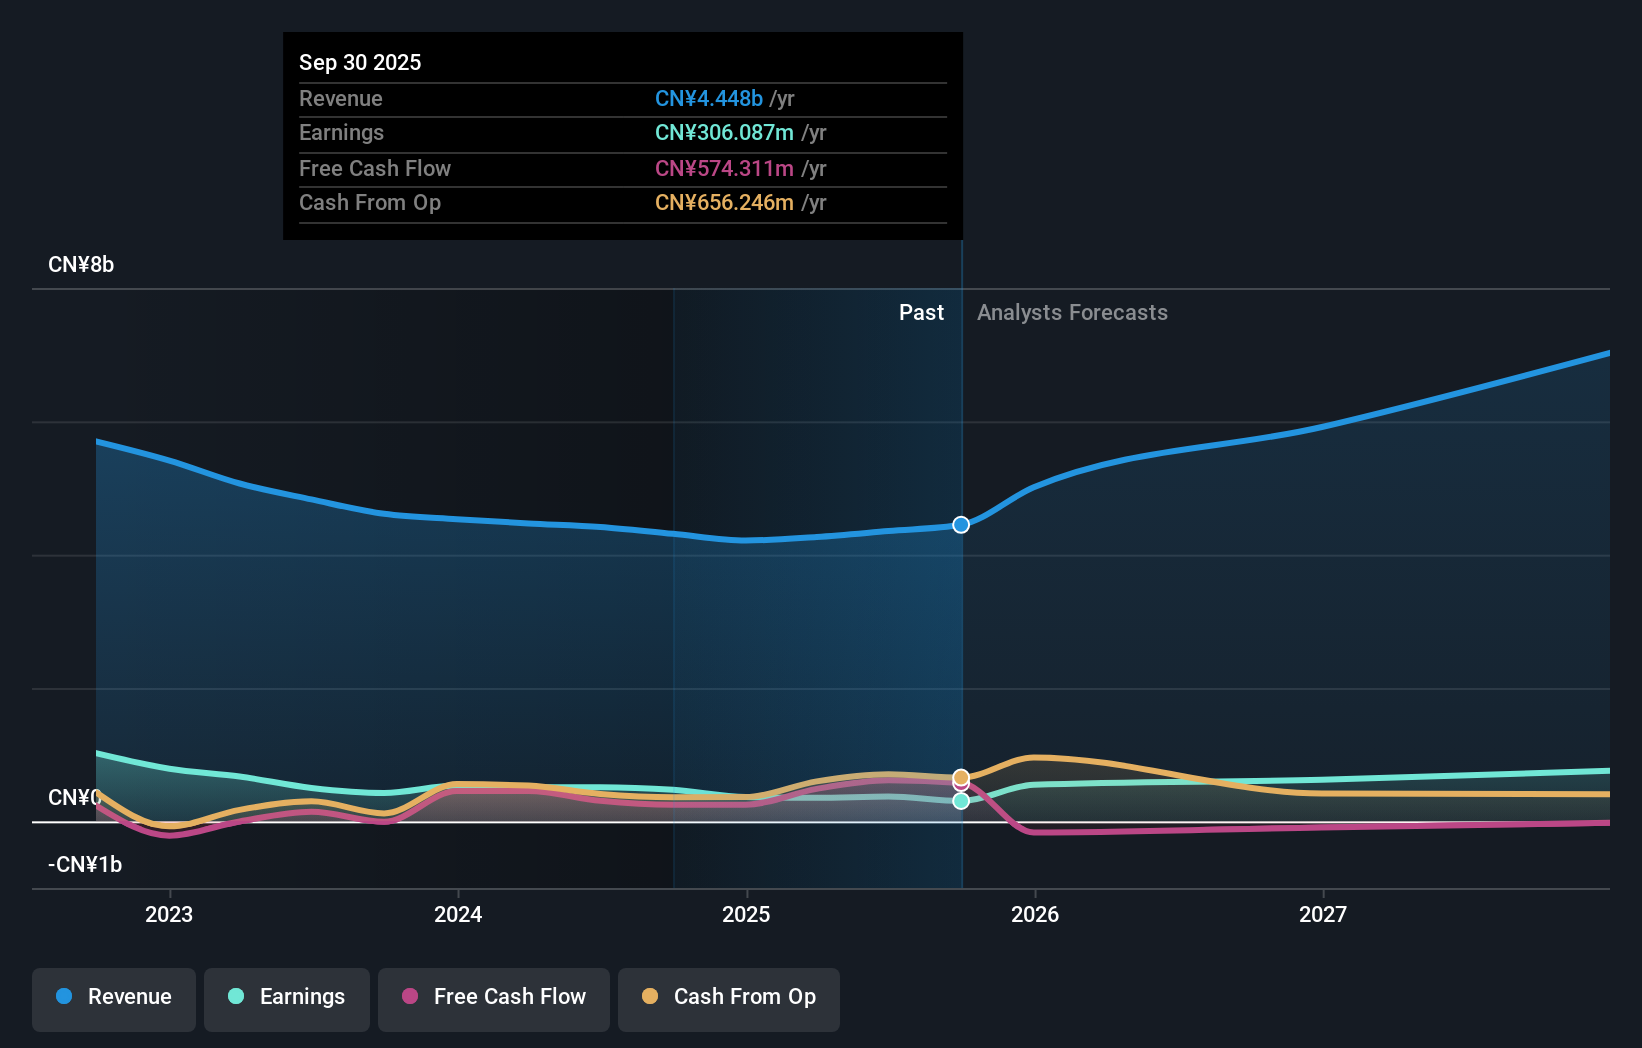
Overview: Ingenic Semiconductor Co., Ltd. designs, develops, and sells system-on-a-chip (SoC) products for various electronic devices worldwide, with a market cap of CN¥52.83 billion.
Operations: Ingenic Semiconductor generates revenue primarily from the design, development, and sale of system-on-a-chip (SoC) products for a range of electronic devices globally.
Insider Ownership: 16.5%
Ingenic Semiconductor demonstrates strong growth potential, with earnings expected to rise significantly at 41.9% annually, surpassing the Chinese market's 26.6%. Revenue is also projected to grow robustly at 33.1% per year. Recent financial results show a substantial profit increase of CNY 1.20 billion for H1 2026 from CNY 203.12 million last year. The company completed a share buyback worth CNY 150 million and raised HKD 3.13 billion in equity offerings, bolstering its capital structure amid high insider ownership influence.
- Dive into the specifics of Ingenic Semiconductor here with our thorough growth forecast report.
- The valuation report we've compiled suggests that Ingenic Semiconductor's current price could be quite moderate.
Maxscend Microelectronics (SZSE:300782)
Simply Wall St Growth Rating: ★★★★☆☆
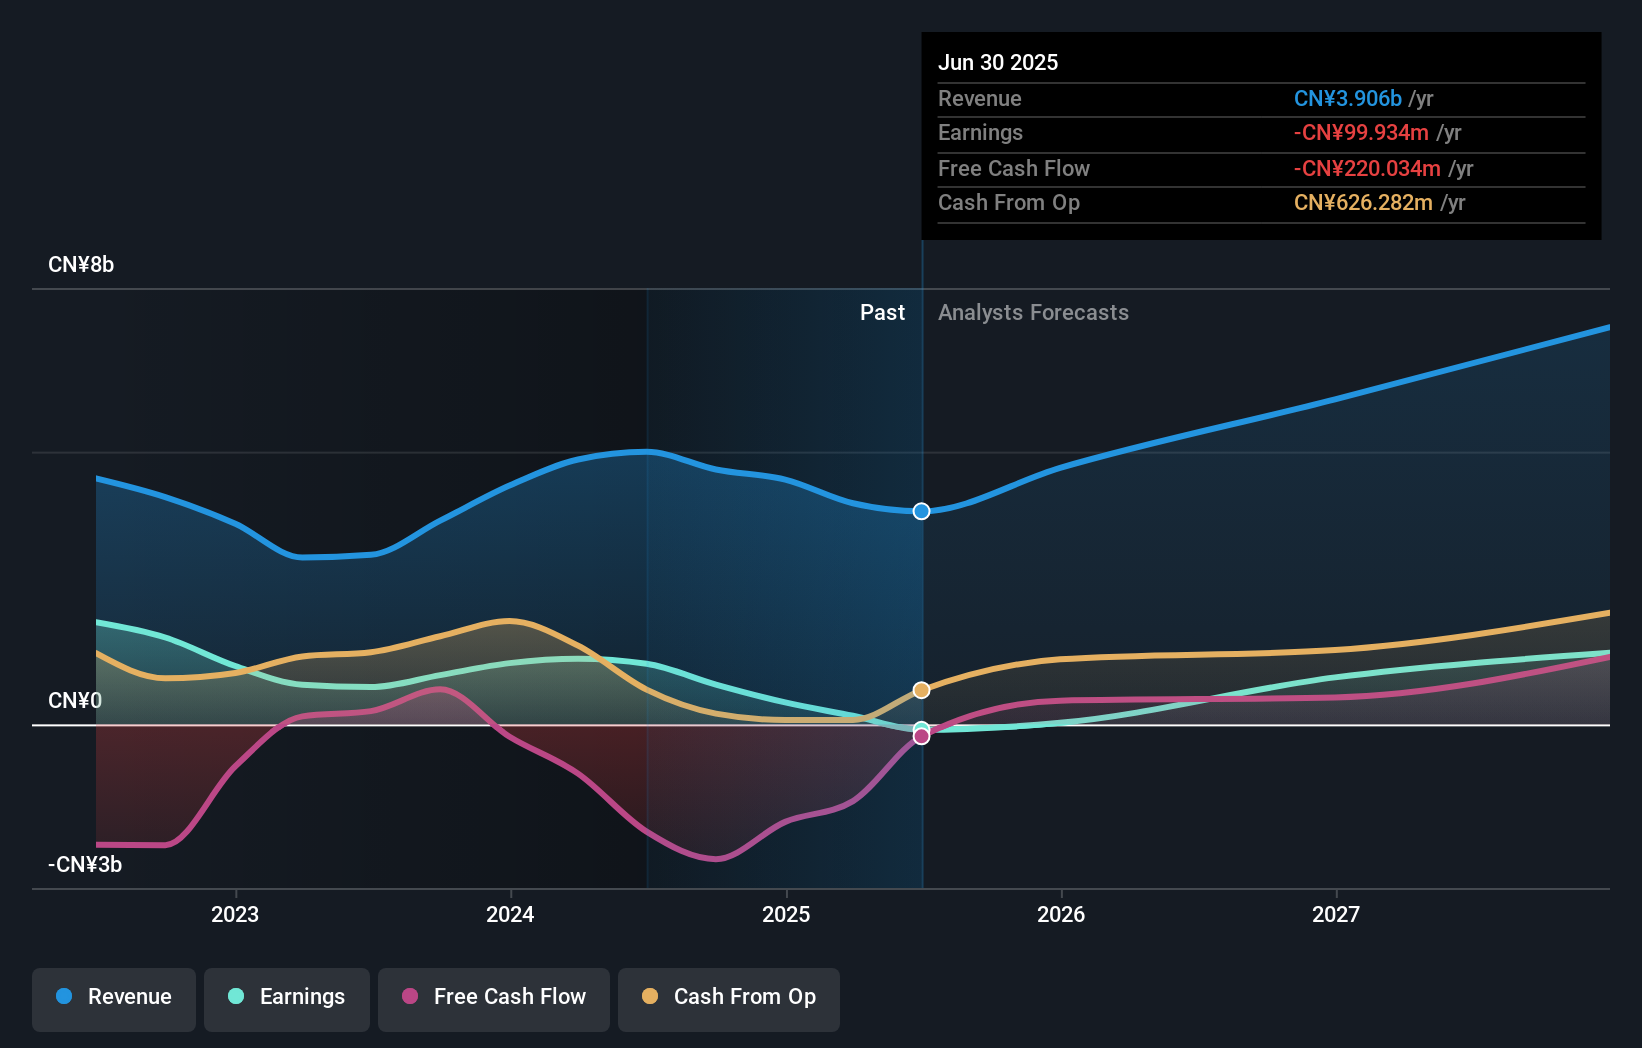
Overview: Maxscend Microelectronics Company Limited, with a market cap of CN¥33.27 billion, is involved in the research, development, production, and sale of radio frequency integrated circuits both in China and internationally.
Operations: Maxscend Microelectronics Company Limited's revenue is primarily derived from its operations in the research, development, production, and sale of radio frequency integrated circuits across domestic and international markets.
Insider Ownership: 24.9%
Maxscend Microelectronics is experiencing robust revenue growth, forecasted at 19% annually, exceeding the broader Chinese market's growth. Despite a net loss of CNY 370.75 million for H1 2026, the company anticipates becoming profitable within three years. Recent changes in directors and amendments to company bylaws suggest strategic shifts potentially influenced by high insider ownership. The stock trades slightly below its estimated fair value, although its projected return on equity remains modest at 6.8%.
- Unlock comprehensive insights into our analysis of Maxscend Microelectronics stock in this growth report.
- Our valuation report here indicates Maxscend Microelectronics may be overvalued.
Seize The Opportunity
- Unlock more gems! Our Fast Growing Asian Companies With High Insider Ownership screener has unearthed 511 more companies for you to explore.Click here to unveil our expertly curated list of 514 Fast Growing Asian Companies With High Insider Ownership.
- Ready To Venture Into Other Investment Styles? The latest GPUs need a type of rare earth metal called Dysprosium and there are only 33 companies in the world exploring or producing it. Find the list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com