


Undiscovered Gems in Asia to Explore This October 2026
As of October 2026, the Asian markets are experiencing a dynamic shift, with small-cap stocks gaining attention against the backdrop of global economic fluctuations and rising oil prices. This environment presents an intriguing opportunity for investors to explore lesser-known companies that demonstrate resilience and potential for growth amidst these changing conditions.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| SPRIX | 13.12% | 6.95% | -5.71% | ★★★★★★ |
| AMPAK Technology | 34.99% | -10.73% | -19.52% | ★★★★★☆ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Silvery Dragon Group Tianjin | 25.01% | 2.55% | 25.62% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Chengtun Mining Group | 99.24% | -6.93% | 33.44% | ★★★☆☆☆ |
| Primo Global Holdings | 64.63% | 9.93% | 28.27% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Here's a peek at a few of the choices from the screener.
Shiyue Daotian Group (SEHK:9676)
Simply Wall St Value Rating: ★★★★★★
Overview: Shiyue Daotian Group Co., Ltd. focuses on manufacturing and selling pantry staple foods in China, with a market capitalization of HK$4.40 billion.
Operations: The company generates revenue primarily from rice products (CN¥5.38 billion) and corn products (CN¥708.59 million), with additional contributions from dried food and other products, as well as whole grain, bean, and other products.
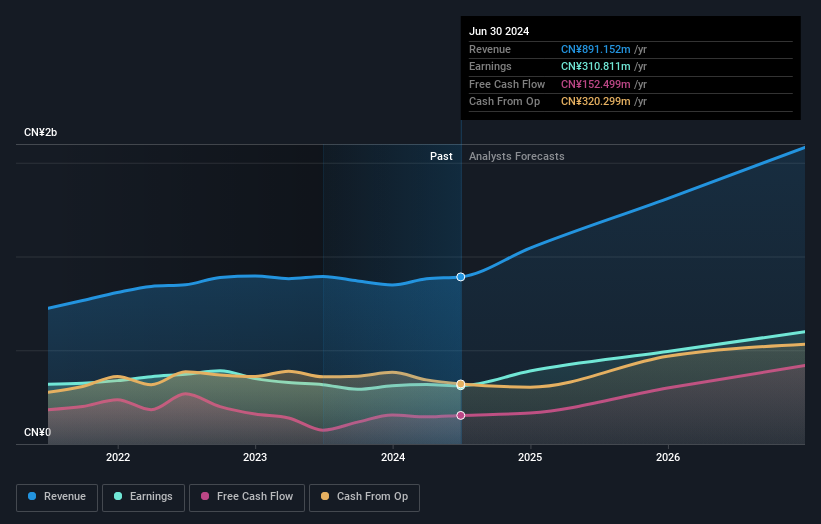
Shiyue Daotian Group seems to be carving a niche in the market with its recent performance. The company reported sales of CNY 3.81 billion for the first half of 2026, up from CNY 3.06 billion last year, and net income rose to CNY 157.31 million from CNY 116.23 million. With earnings growth at an impressive 140.9% over the past year, it outpaced the Food industry's modest growth of just 0.8%. Additionally, its debt-to-equity ratio improved significantly from five years ago, dropping to a more manageable level of 26.9%. Despite not being free cash flow positive yet, Shiyue Daotian is trading at good value compared to peers and industry standards while maintaining profitability without concerns about cash runway or interest coverage issues.
- Delve into the full analysis health report here for a deeper understanding of Shiyue Daotian Group.
Explore historical data to track Shiyue Daotian Group's performance over time in our Past section.
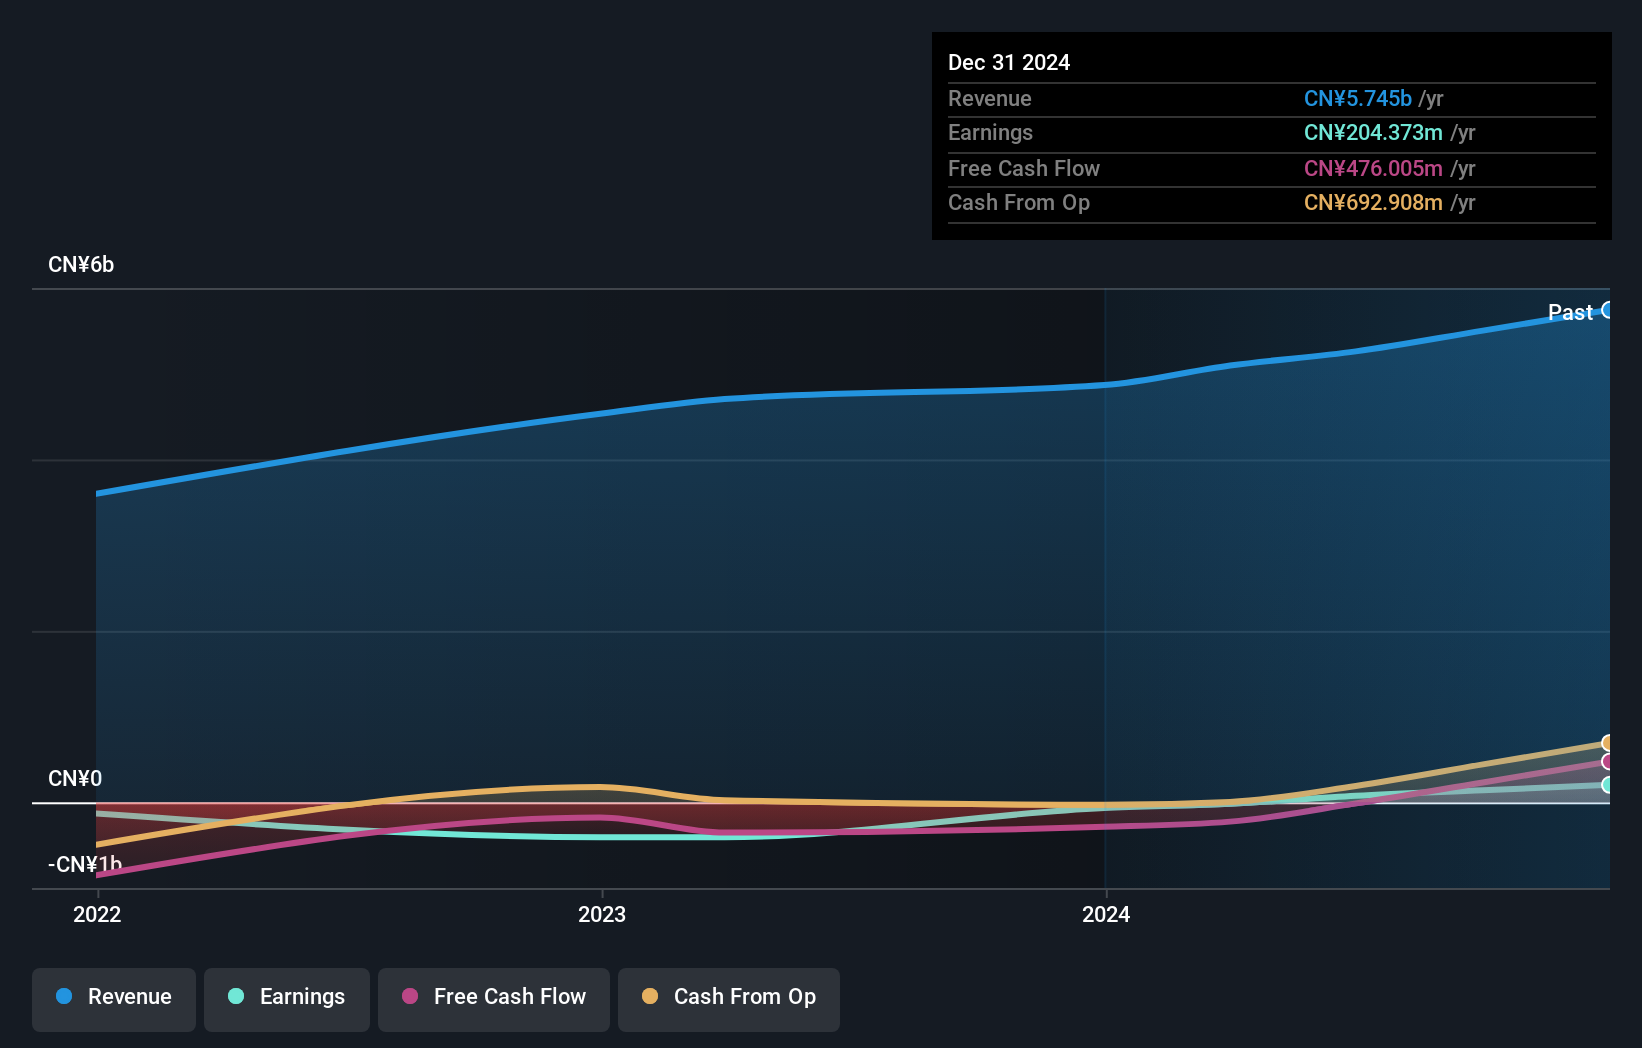
Shantui Construction Machinery (SZSE:000680)
Simply Wall St Value Rating: ★★★★★☆
Overview: Shantui Construction Machinery Co., Ltd. is a company that manufactures and sells construction machinery products both in China and internationally, with a market capitalization of approximately CN¥13.53 billion.
Operations: Shantui Construction Machinery generates revenue primarily from commercial product sales amounting to CN¥164.76 million and sales of industrial products totaling CN¥14.64 billion.
Shantui Construction Machinery, a notable player in the machinery sector, has shown remarkable growth with earnings increasing by 14.6% over the past year, outpacing the industry average of -0.2%. The company's sales for H1 2026 reached CNY 7.68 billion, up from CNY 6.49 billion last year, while net income improved to CNY 681 million from CNY 572 million. Trading at a value that's reportedly 20.6% below its estimated fair value indicates potential upside for investors seeking undervalued opportunities in Asia's market landscape. Additionally, Shantui's interest payments are comfortably covered by EBIT at an impressive ratio of nearly 180 times.
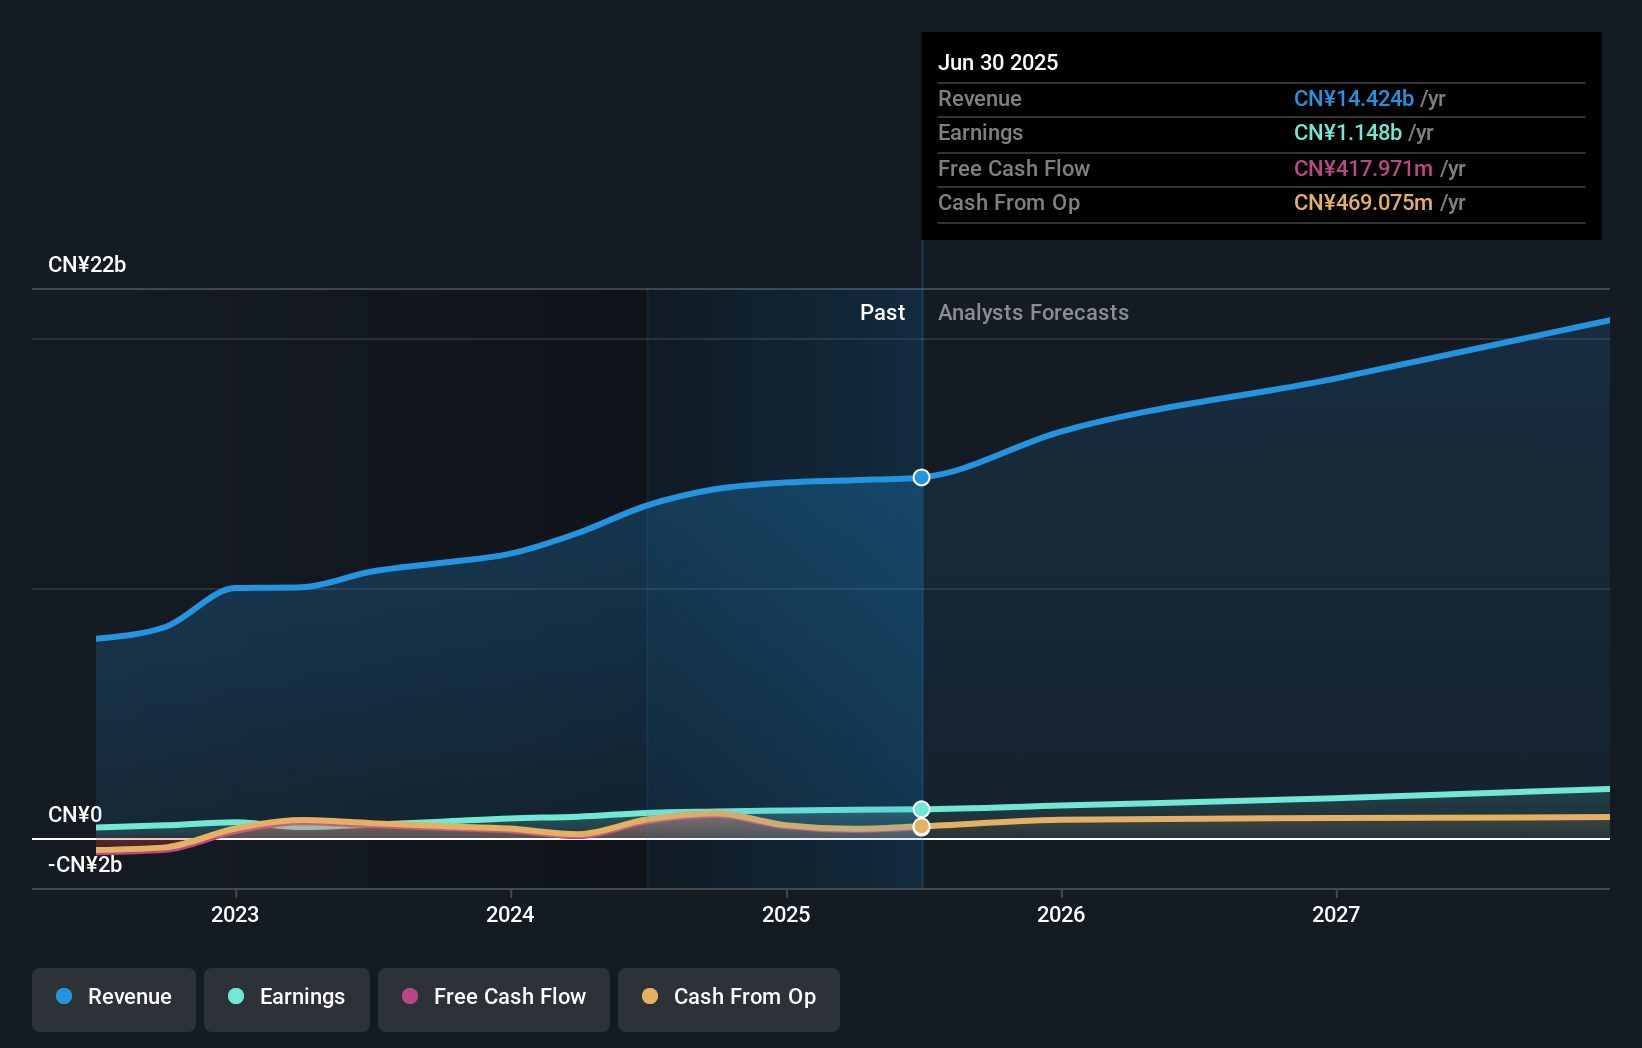
Zhejiang Wolwo Bio-Pharmaceutical (SZSE:300357)
Simply Wall St Value Rating: ★★★★★☆
Overview: Zhejiang Wolwo Bio-Pharmaceutical Co., Ltd. is a company engaged in the research, development, and production of bio-pharmaceutical products with a market cap of CN¥10.15 billion.
Operations: Wolwo Bio-Pharmaceutical generates revenue primarily through the sale of bio-pharmaceutical products. The company's financial performance is reflected in its market capitalization of CN¥10.15 billion, indicating its valuation within the industry.
Zhejiang Wolwo Bio-Pharmaceutical, a dynamic player in the pharma space, has shown robust financial health with earnings growth of 9.5% over the past year, outpacing industry averages. The company trades at a significant discount of 26.5% below its estimated fair value and boasts high-quality earnings. With net income rising to CNY 391 million from CNY 345 million year-on-year for the nine months ending September 2026, it reflects strong operational performance. Additionally, basic earnings per share increased to CNY 0.75 from CNY 0.66 in the same period last year, indicating solid profitability trends amidst industry challenges.
Turning Ideas Into Actions
- Investigate our full lineup of 128 Asian Undiscovered Gems With Strong Fundamentals right here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com