


Did Earnings And Dividend Stability Just Shift Home BancShares (HOMB) Investment Narrative?
- Home BancShares reported third quarter 2026 results with net interest income of US$241.99 million and net income of US$129.45 million, alongside reported net loan charge offs of US$2.149 million and a reaffirmed regular quarterly dividend of US$0.23 per share, payable on December 2, 2026.
- The combination of higher reported net interest income and net income, relatively low net loan charge offs and an 82 quarter dividend track record reinforces Home BancShares' image as a bank focused on consistent earnings and income generation for shareholders, including retirees seeking regular cash flows.
- The next area of attention is how Home BancShares' steady dividend declaration and recent earnings numbers could influence the broader investment narrative.
Home BancShares Investment Narrative Recap
To own Home BancShares, you need to believe in a fairly steady banking story. Earnings and net interest income for the third quarter of 2026 came in solid, supported by relatively low net loan charge offs of US$2.149 million. The near term swing factor is still how well the bank can hold its roughly targeted core net interest margin while competing against peers offering higher deposit rates.
The biggest operational risk remains choppy loan growth and payoff behavior, which can leave earning assets flat at times and make it harder to sustain current profit levels. Recent results and the modest charge offs do not materially change that equation, so your view probably hinges more on credit discipline and future acquisition execution than this quarter alone.
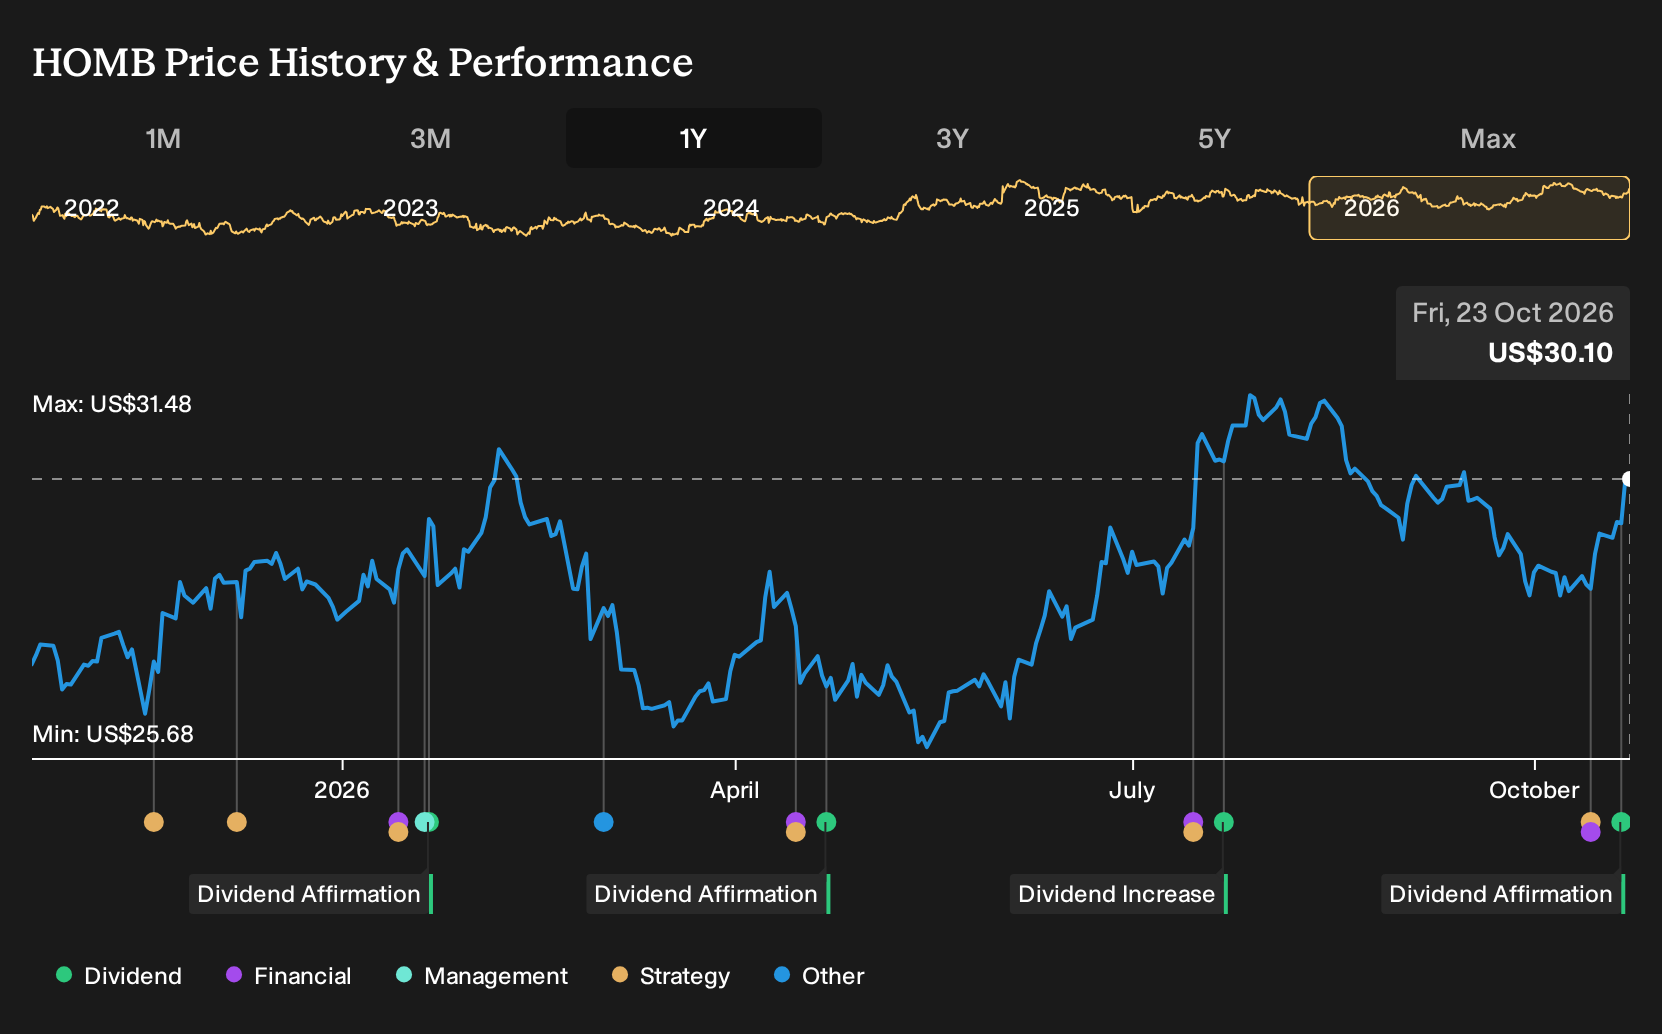
The most relevant update for this income focused story is the reaffirmed US$0.23 per share quarterly dividend, payable on December 2, 2026, which marks 82 consecutive quarterly cash dividends. For investors using Home BancShares as an income anchor, that kind of continuity can matter more than short term share price moves.
That payout sits alongside a dividend yield of about 3.05% and an annual dividend growth rate of 11.11%, according to the provided data. The key question is whether the bank can keep generating enough earnings through disciplined loan and deposit pricing, integration of deals like Mountain Commerce Bank, and controlled credit costs to comfortably support that level of cash return while managing the competitive and acquisition related risks already flagged.
Home BancShares' current analyst storyline points to forecast revenue of about US$1.3b and expected earnings of US$537.3m by 2029, based on an assumed 5.0% yearly revenue growth rate and a rise in earnings of roughly US$57.9m from US$479.4m today.
Uncover how Home BancShares' fair value indicates a 10% potential upside to its current price that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$33 to almost US$50 per share. Fellow private investors are therefore assigning very different long term payoffs to Home BancShares. Set that against acquisition and loan growth uncertainty, and you can see why opinions split. Use these contrasting views to stress test your own thesis.
Explore another Home BancShares fair value estimate, including one that suggests as much as 66% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Home BancShares research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Home BancShares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Home BancShares' overall financial health at a glance.
Looking For More Ideas Beyond Home BancShares?
If you like the income angle with Home BancShares but want a broader watchlist, the Simply Wall St Screener can surface other opportunities that match different goals, risk levels, and balance sheet profiles.
- For investors who care most about consistent income streams, scan a curated set of 5 dividend fortresses that prioritize ongoing cash returns.
- If capital preservation and stability matter more to you than chasing the highest upside, focus on a 30 resilient stocks with low risk scores to see which businesses have lower risk scores.
- When you want strong fundamentals that are not already crowded trades, filter for a 21 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com