


Waters (WAT) Partnerships Expand HPV Testing Access On A Fairly Valued Stock View
Waters (WAT) just put cervical cancer screening at the center of its story by signing new partnerships with Labcorp and Quest Diagnostics to widen access to the BD Onclarity HPV Assay across clinical and at-home channels.
Recent announcements with Quest Diagnostics, Labcorp, and IMU Biosciences have come alongside a strong run in Waters’ shares, with an 18.8% year to date share price return and a 22.2% 90 day share price return contributing to a 26.2% 1 year total shareholder return.
Scan how cervical cancer testing momentum around Waters compares to other healthcare screening plays by reviewing the hand-picked 34 healthcare AI stocks shaping diagnostics with data and automation.
Waters shares have raced ahead while still sitting a little below the average analyst target and a sizeable discount to one intrinsic value estimate. Does that gap reflect opportunity, or does it show the market’s caution on this new cervical screening push?
Most Popular Narrative: 1% Undervalued
Against a last close of $453.67, the most followed narrative pegs Waters' fair value at about $458.22, leaving only a narrow implied discount that puts execution risk and cervical screening upside under the microscope.
Waters is set up to benefit from a prolonged instrument replacement and pharma reshoring cycle, with LC and LC MS instruments showing a strong replacement backlog that management expects to run at least through 2027 and an additional outfitting wave linked to about US$100b of U.S. pharma CapEx from 2027 to 2030. This can support sustained equipment revenue and related service growth.
See why 16 investors see Waters as 1% undervalued.
Result: Fair Value of $458.22 (ABOUT RIGHT)
Still, heavy reliance on smooth BD integration and on a recovery in weaker China diagnostics leaves the Waters story exposed if either stalls or reverses.
Find out about the key risks to this Waters narrative.
Another View: What Multiples Say About Waters
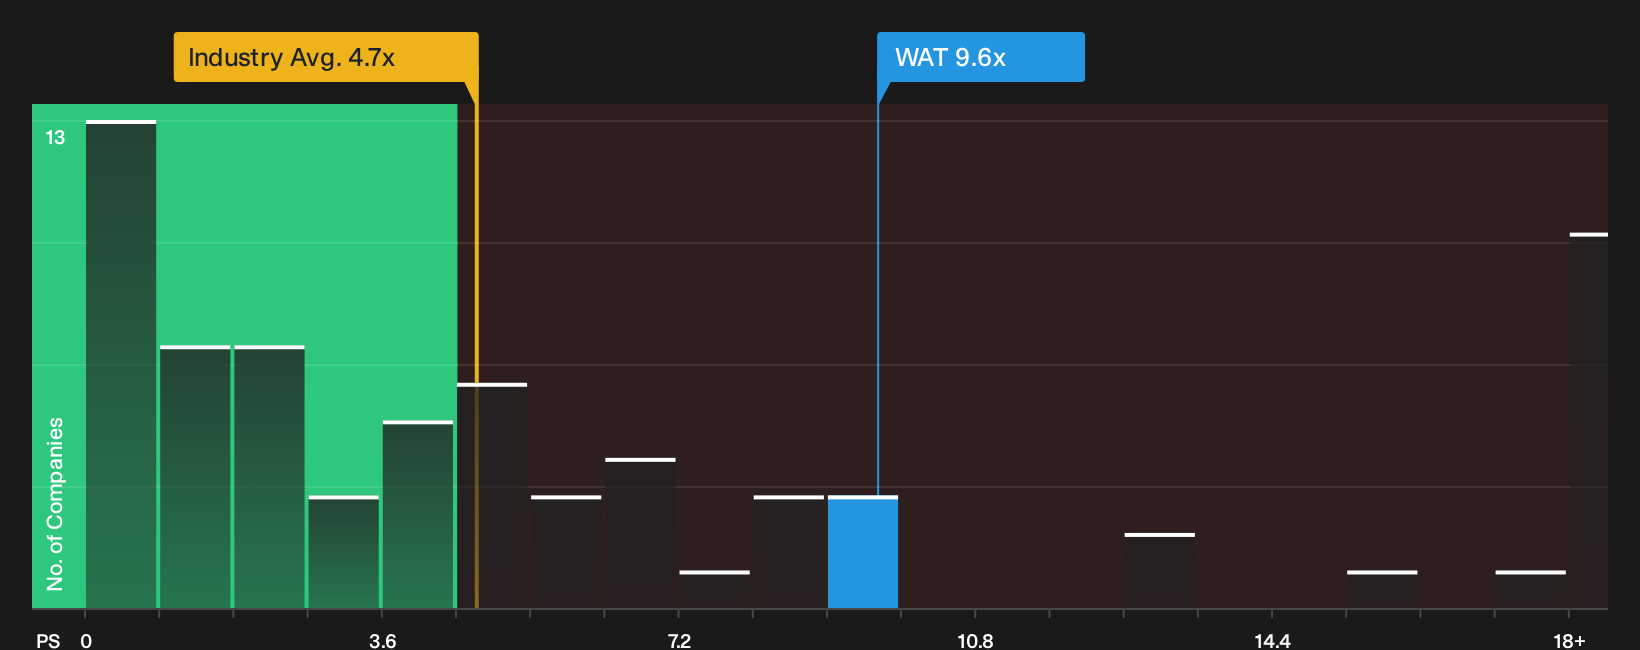
Fair value around $458 per share suggests Waters is roughly in line with the most followed narrative, yet the current P/S of 9.6x paints a richer picture than many peers. The US Life Sciences group averages 4.7x and the fair ratio sits closer to 7.9x, which points to less room for error if expectations slip.
For a closer look at how that pricing stacks up against fundamentals, see what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Cautious or optimistic after everything about Waters so far, the real edge comes from testing the data yourself and reacting faster than the crowd by weighing 1 key reward and 3 important warning signs
Looking for more investment ideas beyond Waters?
If Waters has sharpened your thinking, do not stop here. Fresh opportunities often appear where other investors are not looking yet.
- Target potential mispricing by scanning companies that combine quality metrics with appealing valuations through the 29 high quality undervalued stocks.
- Fortify your income stream by reviewing a curated set of higher yielding payers using the 5 dividend fortresses.
- Reduce portfolio stress by focusing on financially resilient businesses highlighted in the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com