


Compass (COMP) Faces MLS Legal Fights As Fair Value Narrative Stays In Focus
Compass (COMP) is back in focus after a series of legal and regulatory flashpoints, including clashes with multiple MLS organizations over listing rules and securities class actions alleging misleading compliance disclosures.
Against this backdrop of legal disputes and boardroom changes, Compass shares now trade at US$9.75, after a 6.79% 7 day share price gain that comes on the heels of a 17.37% decline over 90 days and a 21.42% 1 year total shareholder return. This sits on top of a very large 3 year total shareholder return, suggesting long term holders have seen strong compounding even as shorter term momentum has recently been under pressure.
Scan for other real estate platforms facing legal, regulatory, or business model pressure and compare them with Compass using our curated 30 resilient stocks with low risk scores to evaluate potential resilience and balance sheet strength.
After a sharp multi year climb and a choppy few months around lawsuits and board changes, the real question is whether Compass at US$9.75 still offers meaningful upside, or if most of the easy gains are already behind it.
Most Popular Narrative: 35% Undervalued
On the most followed narrative, Compass looks materially cheaper than its assessed fair value of $14.92 compared with the latest close at $9.75. This puts legal noise up against a story built around platform economics and earnings potential.
Rapid adoption and continuous improvement of Compass's AI-powered, end-to-end technology platform is increasing agent productivity, driving higher transaction volumes, improving retention, and is expected to widen margins as AI-driven process efficiencies scale throughout the organization, positively impacting revenue, EBITDA, and net margins.
See why 16 investors see Compass as 35% undervalued.
Result: Fair Value of $14.92 (UNDERVALUED)
Still, the Compass story can change quickly if commission focused revenue comes under pressure, or if ongoing legal disputes around MLS rules and merger disclosures escalate.
Find out about the key risks to this Compass narrative.
Another View On Compass Valuation
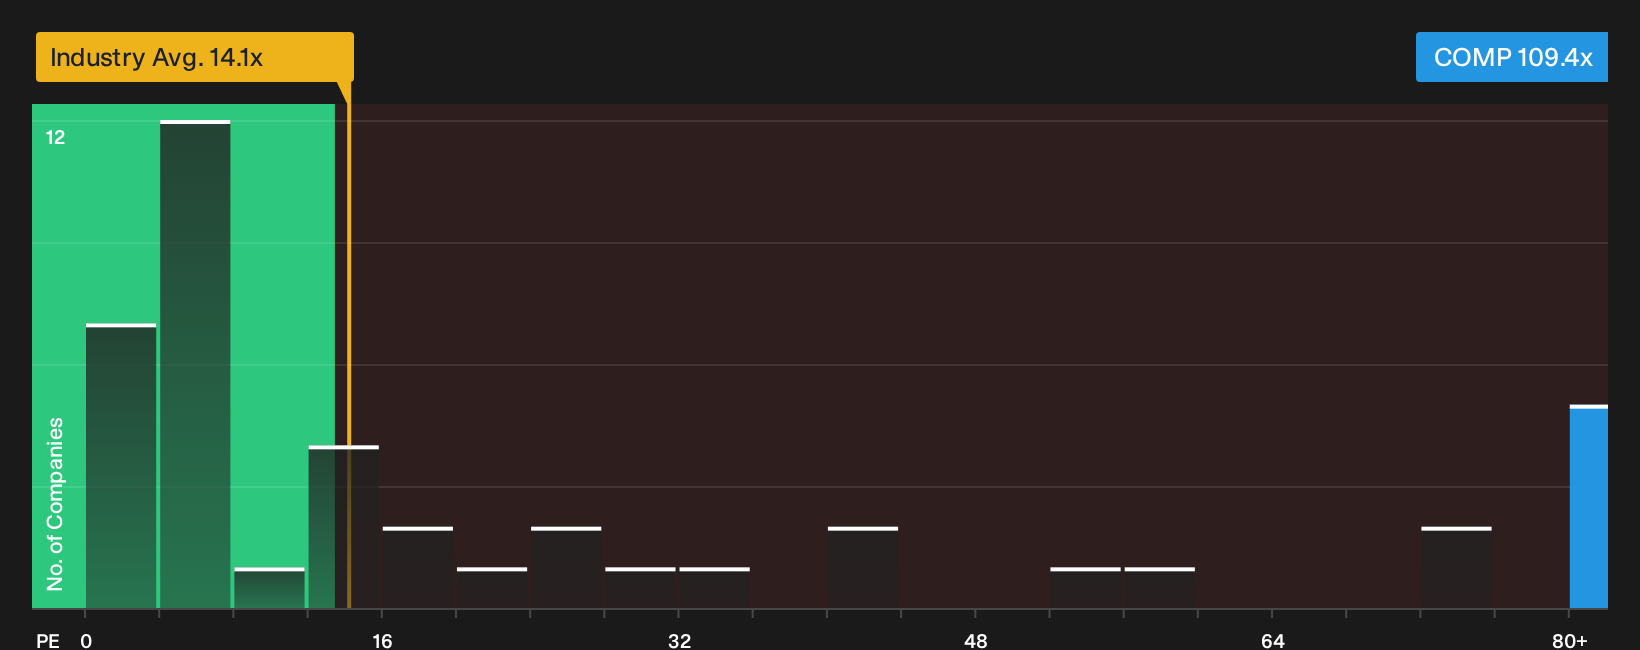
The story flips when you look at Compass through its P/E. The shares trade on about 109.4x earnings, compared with 88.2x for peers and 14.1x for the broader US Real Estate group, while the fair ratio sits at 45.7x. That gap points to meaningful valuation risk if sentiment or forecasts cool.
For a closer read on what that premium might mean in practice for Compass investors, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Compass so far. If you want to act while sentiment is split, consider weighing the competing signals yourself, starting with 3 key rewards and 3 important warning signs.
Looking For More Compass Investment Ideas?
If Compass has your attention, do not stop with a single ticker. Broaden your watchlist now so you are not chasing opportunities after they move.
- Target stronger potential value by scanning companies that combine quality fundamentals with appealing prices using the 29 high quality undervalued stocks.
- Strengthen your income stream by focusing on reliable payers through the 5 dividend fortresses.
- Prioritize resilience by filtering for businesses with healthier finances using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com