


How New Royalty Deals Will Impact Royalty Pharma Stock Investors
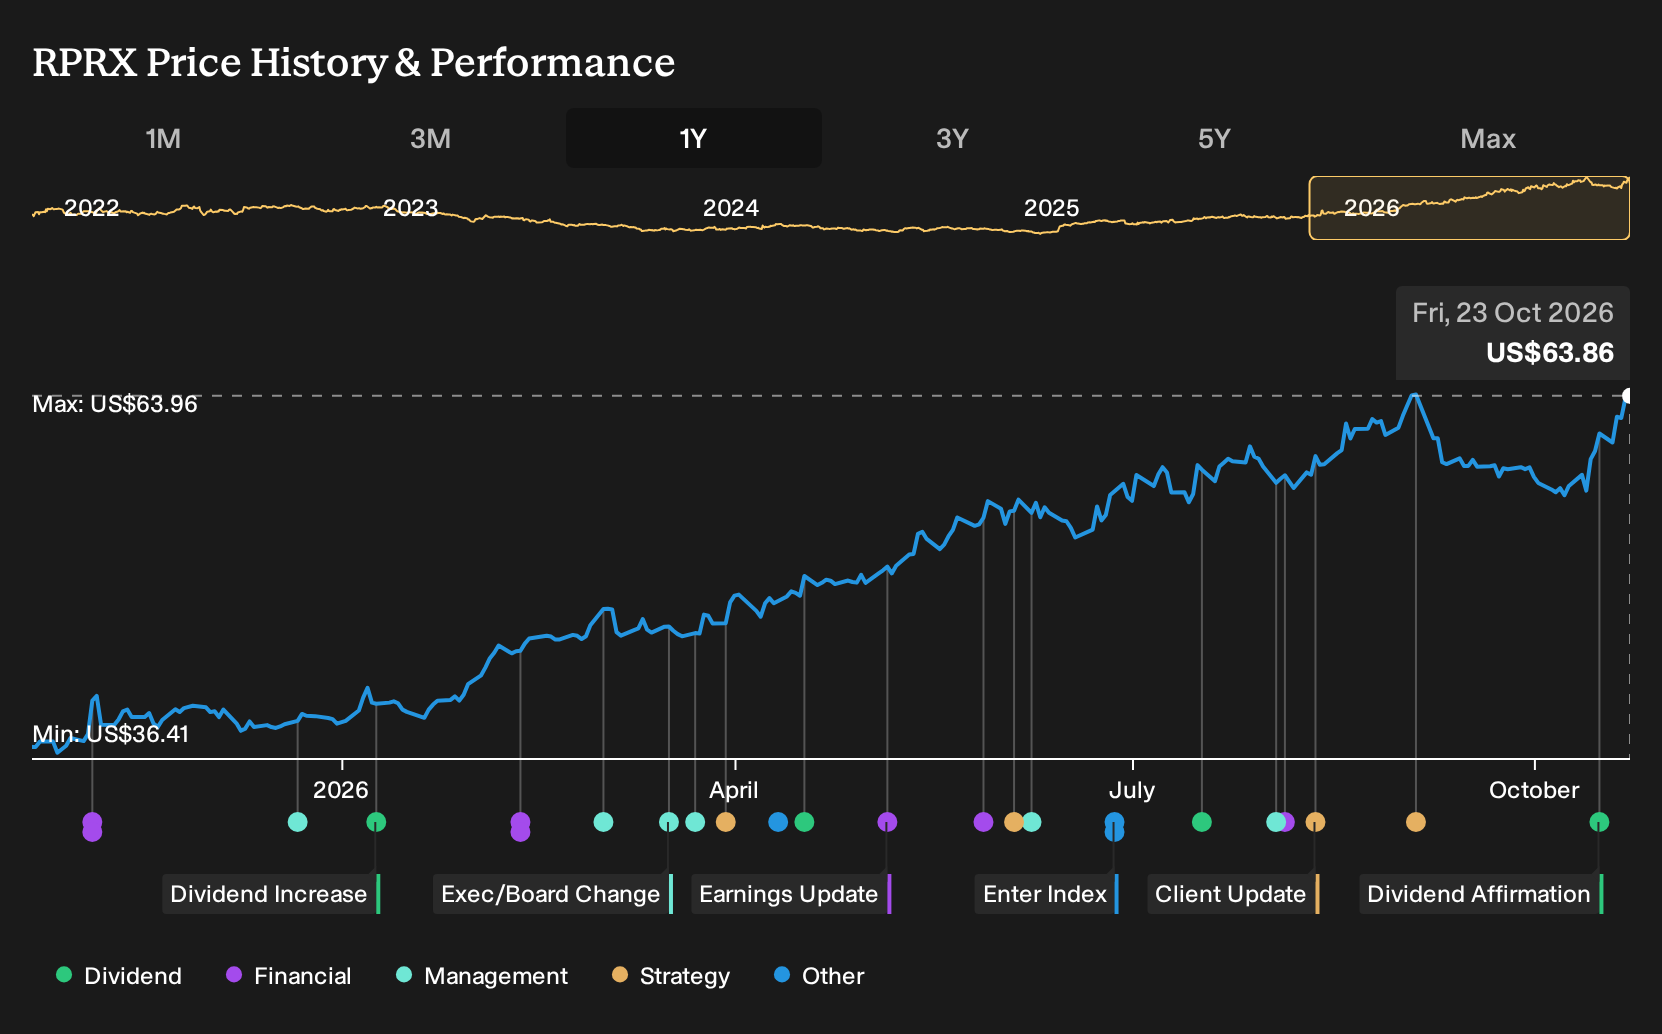
- Royalty Pharma's board approved a past fourth quarter 2026 dividend of $0.235 per Class A ordinary share, payable on December 10, 2026, to holders on record as of November 13, 2026.
- Alongside the dividend, Royalty Pharma expanded its portfolio with late stage royalties such as cliramitug and rusfertide. At the same time, tighter net margins highlight the execution risk in scaling its R&D co funding model.
- We will now look at how Royalty Pharma's expanded late stage royalty pipeline could reshape the investment narrative that was built before this news.
Royalty Pharma Investment Narrative Recap
To own Royalty Pharma, you need to be comfortable with a royalty funding model where capital intensive deals are recycled into a wider stream of cash flows. The key belief is that management can keep sourcing attractive late stage royalties and R&D co funding opportunities while holding the current 32% net margin line after the recent compression.
The immediate swing factor is whether the expanded pipeline can start translating into higher royalty receipts without further pressure on profitability. The biggest operational risk is that returns on new deals fail to keep pace with funding costs and debt, especially if free cash flow coverage of the dividend remains tight.
The recent approval of the US$0.235 fourth quarter 2026 dividend is particularly relevant. It signals that Royalty Pharma is comfortable maintaining cash returns to shareholders even as it leans into new development stage deals like cliramitug and rusfertide, and absorbs the impact of net margins moving from 44.4% last year to 32% now.
For you as an investor, the link between this payout and the broader catalyst is straightforward. Sustaining the dividend while expanding the late stage royalty portfolio increases the focus on whether future receipts from assets such as cliramitug can cover both funding costs and shareholder distributions without stretching the balance sheet further.
Royalty Pharma Forecasts Behind The Dividend Story
Royalty Pharma's narrative projects US$4.4b revenue and US$1.9b earnings by 2029. This implies analysts are projecting 20.3% yearly revenue growth and an earnings increase of about 2.3x from US$812.0m today.
Uncover why Royalty Pharma's fair value is essentially aligned with its current price.
Exploring Other Perspectives
One alternate Royalty Pharma story leans heavily on margin risk. The most cautious analysts already saw rising investment needs as a drag and were only penciling in about US$4.2b revenue and US$1.5b earnings by 2029. That is far below the top forecasts, and this fresh dividend decision could nudge those views in either direction.
Explore 3 other Royalty Pharma fair value estimates, including one that suggests it could be worth just $65.12.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Royalty Pharma research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Royalty Pharma. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Royalty Pharma's overall financial health at a glance.
Looking For More Investment Ideas Beyond Royalty Pharma?
Once you have a view on Royalty Pharma, it can help to compare it with other opportunities that share similar qualities or offer a very different risk and income profile. The Simply Wall St Screener makes that comparison easier by letting you filter for the traits that matter most to you.
- If you want stronger income potential from your portfolio, start with companies that offer robust cash payouts by reviewing 5 dividend fortresses.
- If capital preservation and steadier earnings matter more to you, narrow the field to resilient businesses using the 30 resilient stocks with low risk scores.
- If you prefer to focus on financial strength and cleaner balance sheets, set your filters around leverage and liquidity and work through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com