


Should Cleaner Credit Costs Require Action From First Financial Bankshares (FFIN) Investors?
- First Financial Bankshares reported third quarter 2026 results with net interest income of US$138.51 million and net income of US$74.31 million, alongside basic earnings per share from continuing operations of US$0.52.
- The sharp reduction in net charge offs to US$935,000 for the quarter points to meaningfully cleaner credit performance alongside those higher earnings.
- We will now look at how First Financial Bankshares' stronger earnings and sharply lower net charge offs could influence its investment narrative.
First Financial Bankshares Investment Narrative Recap
To own First Financial Bankshares, you need to be comfortable with a Texas focused bank that leans on credit discipline, steady earnings and a premium valuation relative to much of the sector. The latest quarter fits that picture. Higher net interest income and a larger profit base give management more room to keep funding tech, talent and selective branch growth.
The near term swing factor is whether loan and fee growth can justify the current P/E while sector sentiment toward premium banks has softened at times. The biggest risk is that modest expansion in the book and slower top line growth versus peers curb operating momentum.
The earnings release is the key update for that thesis. Net income of US$74.31 million for the quarter, basic EPS of US$0.52, and nine month profit of US$217.75 million show First Financial Bankshares adding to its earnings base. Net interest income of US$410.21 million for the nine months also aligns with the story of measured, not rapid, expansion.
Net charge offs of US$935,000 for the quarter, compared with US$22.34 million a year earlier, matter just as much for the catalyst and risk balance. Cleaner credit costs support the idea that this bank can keep leaning on a conservative credit profile while it scales in Texas, although any reversal in that trend would quickly challenge the premium that investors are currently paying.
Analysts project that First Financial Bankshares could reach US$823.3 million in revenue and US$337.1 million in earnings by 2029, based on assumptions that include 7.0% yearly revenue growth and an increase in earnings of about US$46 million from US$291.1 million today.
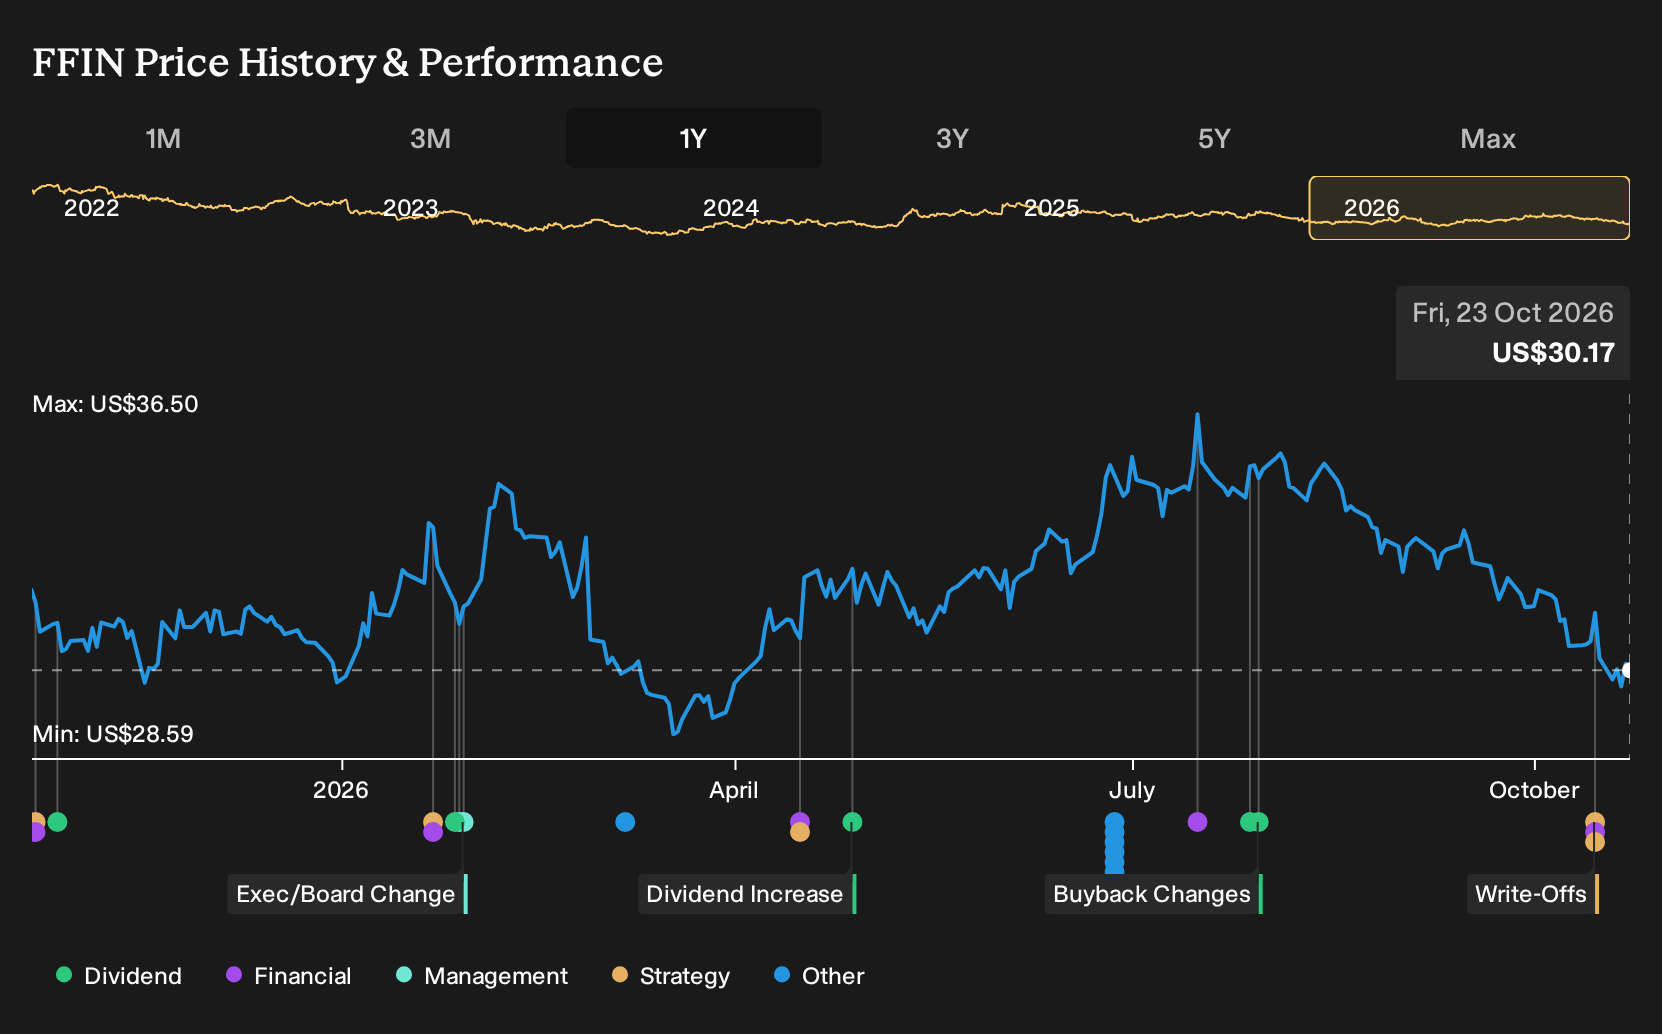
Uncover why First Financial Bankshares' fair value indicates a 15% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community both cluster at US$34.71, so retail views currently line up tightly on First Financial Bankshares. You still face very different angles: some members focus on expansion into Austin and cleaner charge offs, while others flag modest loan growth and premium P/E risk. Explore those competing views before deciding how this bank fits your portfolio.
Explore another First Financial Bankshares fair value estimate, including one that suggests it could be worth just $34.71.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your First Financial Bankshares research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Financial Bankshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Financial Bankshares' overall financial health at a glance.
Looking for more investment ideas beyond First Financial Bankshares?
If First Financial Bankshares fits your approach but you want a broader watchlist, the Simply Wall St Screener can surface other companies with similar qualities or completely different profiles that still match your risk and income goals.
- For investors who want potential upside with quality on their side, scan a focused set of 21 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
- If capital protection ranks high for you, you can filter for companies with stronger balance sheets and steadier finances using this curated list of solid balance sheet and fundamentals (24 results) to anchor the safer end of your portfolio.
- Income focused readers who rely on regular cash returns can shortlist higher yielding options through a targeted 5 dividend fortresses that concentrates on businesses paying 5%+.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com