


Is WEX (WEX) Fairly Valued Following Its Mastercard Asia Pacific Payments Launch?
The new unified fleet payments network that WEX (WEX) is rolling out with Mastercard across Asia Pacific is a clear swing at more transaction volume, fatter margins, and sturdier earnings.
That Mastercard tie-up has arrived after a strong run in WEX’s shares, with a 33.07% year to date share price return and a 23.51% 1 year total shareholder return. Recent momentum looks constructive rather than fading as investors reassess its earnings power.
Compare how WEX stacks up against other payment and fintech players by scanning the 21 high quality undiscovered gems that may be quietly building similar transaction and earnings stories.
WEX now couples a fresh Mastercard growth story with a share price that has already moved hard. Is this still a strong business at a mispriced tag, or has the market already paid up for it?
Most Popular Narrative: 1% Overvalued
The most followed narrative pegs WEX at a fair value of $195.36, almost level with the recent $197.46 close. As a result, the focus is on what can keep earnings power compounding rather than on a large valuation gap.
The main thing that has to go right is that WEX continues to execute on AI led efficiency programs, pricing initiatives in Mobility and mid teens direct AP volume growth while maintaining the funding benefits of WEX Bank.
See why 8 investors see WEX as 1% overvalued.
Result: Fair Value of $195.36 (OVERVALUED)
Still, the WEX story can be knocked off course if fuel card activity weakens faster than new offerings ramp, or if AP rivals squeeze transaction margins.
Find out about the key risks to this WEX narrative.
Another View: WEX Through A Cash Flow Lens
The first take on WEX leans on analyst targets and earnings multiples that cluster near fair value. A second approach, the Simply Wall St DCF model, points in a very different direction. On that framework, WEX at $197.46 sits well below an estimated future cash flow value of $492.54, which flags a wide gap between what is being paid for the shares and what long term cash generation suggests they could be worth. That raises a simple question for investors: Which signal carries more weight, near term earnings comparables or a much richer cash flow estimate?
Look into how the SWS DCF model arrives at its fair value.
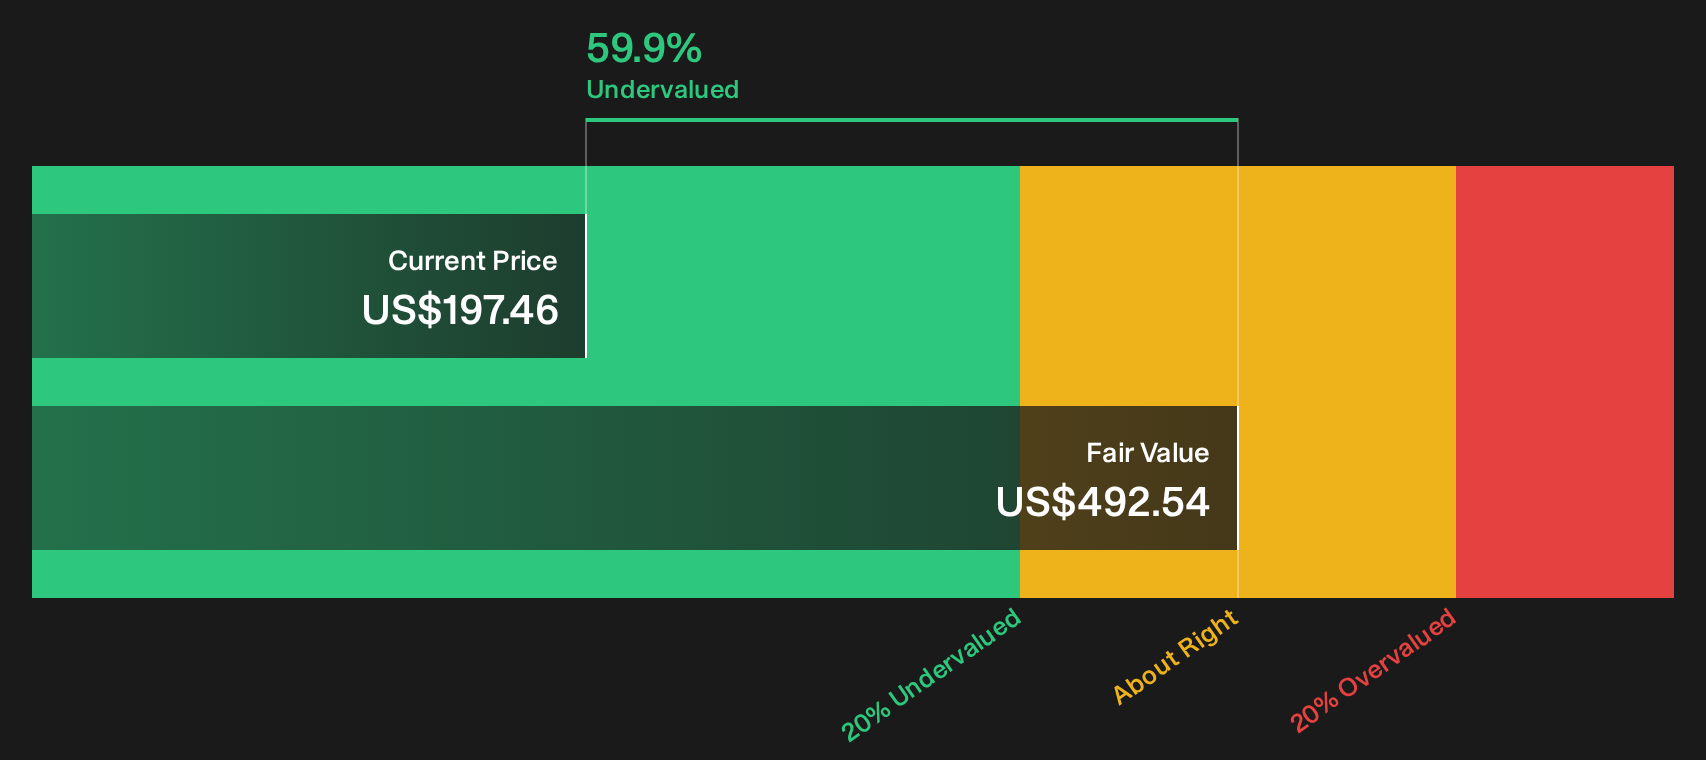
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out WEX for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages so far on WEX, so treat this as a starting point. Move quickly to the underlying numbers, and weigh the 3 key rewards and 2 important warning signs against your own judgment.
Looking for more WEX style ideas?
If WEX has sharpened your focus on quality opportunities, do not stop here. Use the Simply Wall Street Screener to surface more targeted ideas that match your approach.
- Target long term compounding potential by checking companies that look mispriced on fundamentals through the 29 high quality undervalued stocks.
- Strengthen your downside protection by scanning the 30 resilient stocks with low risk scores that show resilient balance sheets and more stable risk profiles.
- Hunt for fresher ideas by reviewing the 21 high quality undiscovered gems that combine strong financials with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com