


3 UK Mortgage Lender Stocks Facing A Big Tax Test
UK mortgage lenders and domestic financials sit right in the crosshairs of today’s tax debate, where record postwar tax levels meet rising questions about how housing and property are treated. That mix can quietly reshape earnings power, funding costs and investor sentiment. In this article you will see three UK listed stocks exposed to this policy story and how current tax choices may help or hurt their long term appeal.
The three lenders in focus below are just a starting sample, and the full screen surfaced 2 more UK listed financials with equally compelling mortgage linked narratives that are not covered in this article. To identify potential ideas that better match your own risk, size and balance sheet preferences, head straight into the UK Domestic-Focused Financials and Mortgage Lenders screener to filter, analyze and line up your highest conviction plays.
Nationwide Building Society (LSE:NBS)
Nationwide Building Society is a large UK mutual lender focused on domestic retail banking and mortgages, giving direct exposure to the UK housing finance theme. It generates £6.0b of revenue entirely in the United Kingdom and has a market cap of about £1.1b.
For UK mortgage exposure, Nationwide Building Society offers a rare mix of member-focused retail banking, a large residential loan book and a pure domestic revenue base. All of this is wrapped in a building society structure that could feel very different if one unseen pressure on its mortgage economics shifts.
If you want to see how that pressure shows up in real numbers, pull up the Nationwide Building Society financial health report for Nationwide Building Society and see what might quietly shift next.

Paragon Banking Group (LSE:PAG)
Paragon Banking Group plugs directly into the UK Domestic-Focused Financials and Mortgage Lenders theme, with a mix of residential mortgages and property-linked lending that sits alongside specialist finance for SMEs and savers who fund the loan book through deposits.
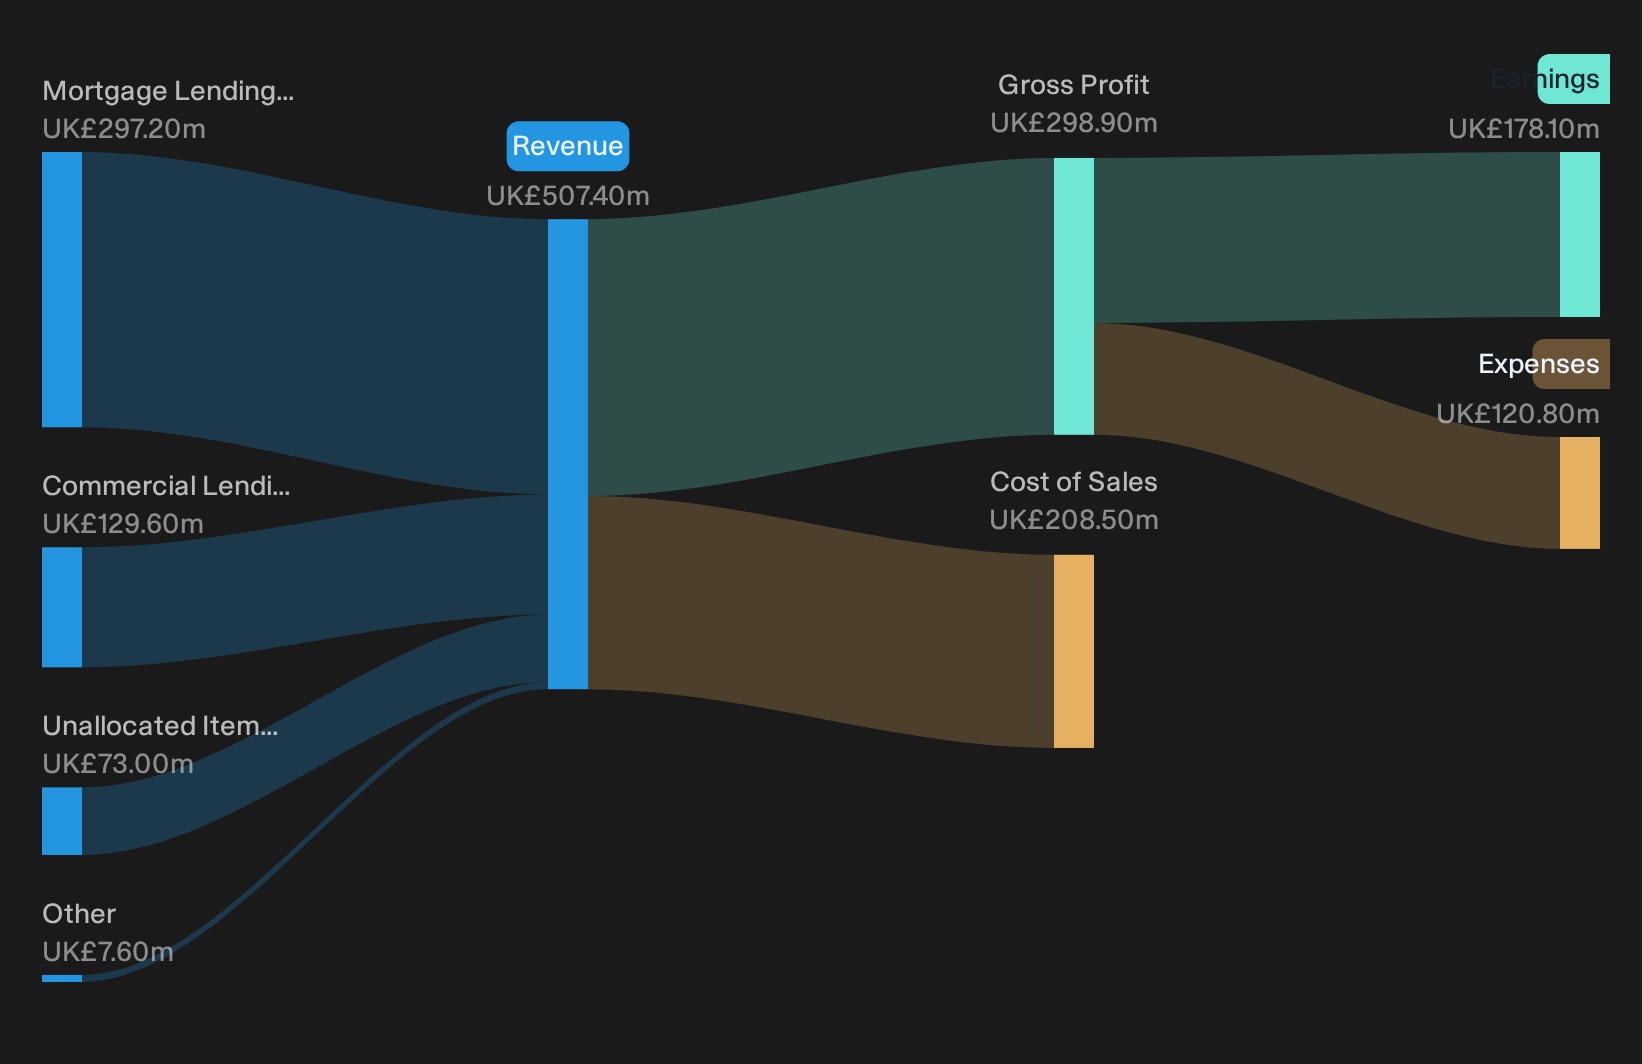
Paragon Banking Group generates £297.2 million from Mortgage Lending and £129.6 million from Commercial Lending, with £73 million reported as unallocated items, all from the UK, and has a market value of about £1.3 billion.
For investors tracking how UK housing taxes and policy tweaks ripple into lenders, Paragon Banking Group offers a blend of property-backed exposure and specialist finance that is already being shaped by management’s focus on efficiency and funding flexibility.
"Paragon Banking Group is continuing to roll out technology, cloud migration and AI tools across core systems, which is already associated with a cost/income ratio around the mid 30% range. This is viewed as a potential support for net margin and earnings resilience if the loan book grows."
The next chapter for Paragon Banking Group may hinge on how one less visible funding shift affects both pricing power and growth headroom.
That funding shift is the real swing factor, and the full narrative for Paragon Banking Group shows how Paragon Banking Group’s deposit mix, pricing power and loan growth could be quietly decoupling from peers.
OSB Group (LSE:OSB)
OSB Group plugs directly into the UK Domestic-Focused Financials and Mortgage Lenders theme as a specialist in buy-to-let, residential and other niche mortgages, with £421.8 million of income from its OneSavings Bank arm and £233.9 million from Charter Court, and a market value around £1.6b.
For investors hunting for focused UK mortgage exposure, OSB Group offers a cleaner specialist story where the real interest lies in how its operating model is being rewired behind the scenes.
"OSB Group's significant ongoing tech transformation and digital infrastructure investment are enabling them to streamline operations, modernize their lending and savings platforms, and improve overall efficiency; these advances are expected to lower cost-to-income ratios and ultimately increase net margins and earnings over the medium term.
The real test comes if one pressure point in its mortgage book behaves differently to what those refreshed systems and models currently assume.
When that pressure point shifts, the full narrative for OSB Group maps how OSB Group’s tech overhaul, funding mix and mortgage niches could quietly reset earnings power and risk.

Seeking Alternatives Before The Crowd?
Fresh momentum often gets caught early, before screens light up and headlines follow. Use that window while it matters. Track under the radar ideas now and position yourself accordingly.
- Look for early-stage breakouts in smaller companies that already have strong balance sheets and positive cash flows using the curated 8 high quality undervalued stocks before they gain wider attention.
- Focus on resilient income plays designed to handle volatility through a hand-picked 5 dividend fortresses that emphasizes high yield and robust fundamentals while prices are still normalizing.
- Monitor structural trends in AI infrastructure by reviewing the focused 55 AI infrastructure stocks and consider opportunities before they become widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com