


Marriott Vacations Worldwide (VAC) Stock May Be 19% Undervalued After Loan Securitization
Marriott Vacations Worldwide has delivered a sharp year to date run, which puts fresh attention on whether the cash the business can generate really supports the current share price. With the stock recently closing at US$109.31, the key issue is how that market tag stacks up against what its future cash flows are worth today.
- The share price is up 85.7% year to date, so a lot now depends on whether the underlying cash generation can keep justifying that kind of move.
- The company’s recent US$460m securitization of vacation ownership loans may support cash flow flexibility by recycling capital from its loan book back into the business.
- Prefer to judge Marriott Vacations Worldwide on sales? See what Marriott Vacations Worldwide's 1.1x P/S says about the price.
The issue now is whether Marriott Vacations Worldwide’s current valuation is supported by its cash flows when measured against an intrinsic value estimate based on a Discounted Cash Flow (DCF) approach.
If you want to stress test this same cash flow question across a broader field, compare Marriott Vacations Worldwide with 29 high quality undervalued stocks.
Does Marriott Vacations Worldwide Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here uses a 2 Stage Free Cash Flow to Equity framework to translate Marriott Vacations Worldwide’s expected cash generation into today’s dollars. Latest twelve month free cash flow sits at about $60.9 million, while the projections used in the model assume that annual free cash flow grows into the mid hundreds of millions over the coming decade, rather than shrinking away.
Those cash flow assumptions, when discounted back, indicate an intrinsic value that is meaningfully above the current share price of US$109.31. The recent US$460 million securitization of vacation ownership loans gives the group additional flexibility to recycle capital from its loan book. This supports the DCF case because the market price still sits below what the model suggests the cash flows are worth. Find out what Marriott Vacations Worldwide could be worth using our Discounted Cash Flow (DCF) estimate.
The Marriott Vacations Worldwide Narrative: What Would Justify Today's Price?
Narratives for Marriott Vacations Worldwide pick up where the cash flow puzzle leaves off. They outline what kind of future path for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today's price, all housed on Simply Wall St's Community page. Each scenario is built around a set of valuation assumptions rather than a single multiple or model output, so you can track those expectations against actual results as they arrive.
Community views on Marriott Vacations Worldwide split between a cash flow recovery story and a leverage and earnings quality worry.
Bull case: 11% undervalued
"Ongoing modernization initiatives that include advanced analytics, AI based propensity models and automation are now embedded in programs such as the Tour Logistics algorithm and are credited with lifting the owner arrival to tour ratio by 600 basis points and VPG by 23% to US$4,477 in Q2 2026..."
Discover why this Narrative puts Marriott Vacations Worldwide at 11% undervalued.
Bear case: 40% overvalued
"Bearish analysts expect Marriott Vacations Worldwide to keep eroding returns on capital while high net-debt-to-EBITDA leverage and inventory related margin pressure force value destructive asset sales or financing..."
Explore why this Narrative puts Marriott Vacations Worldwide at 40% overvalued.
One more question for Marriott Vacations Worldwide that the valuation does not answer
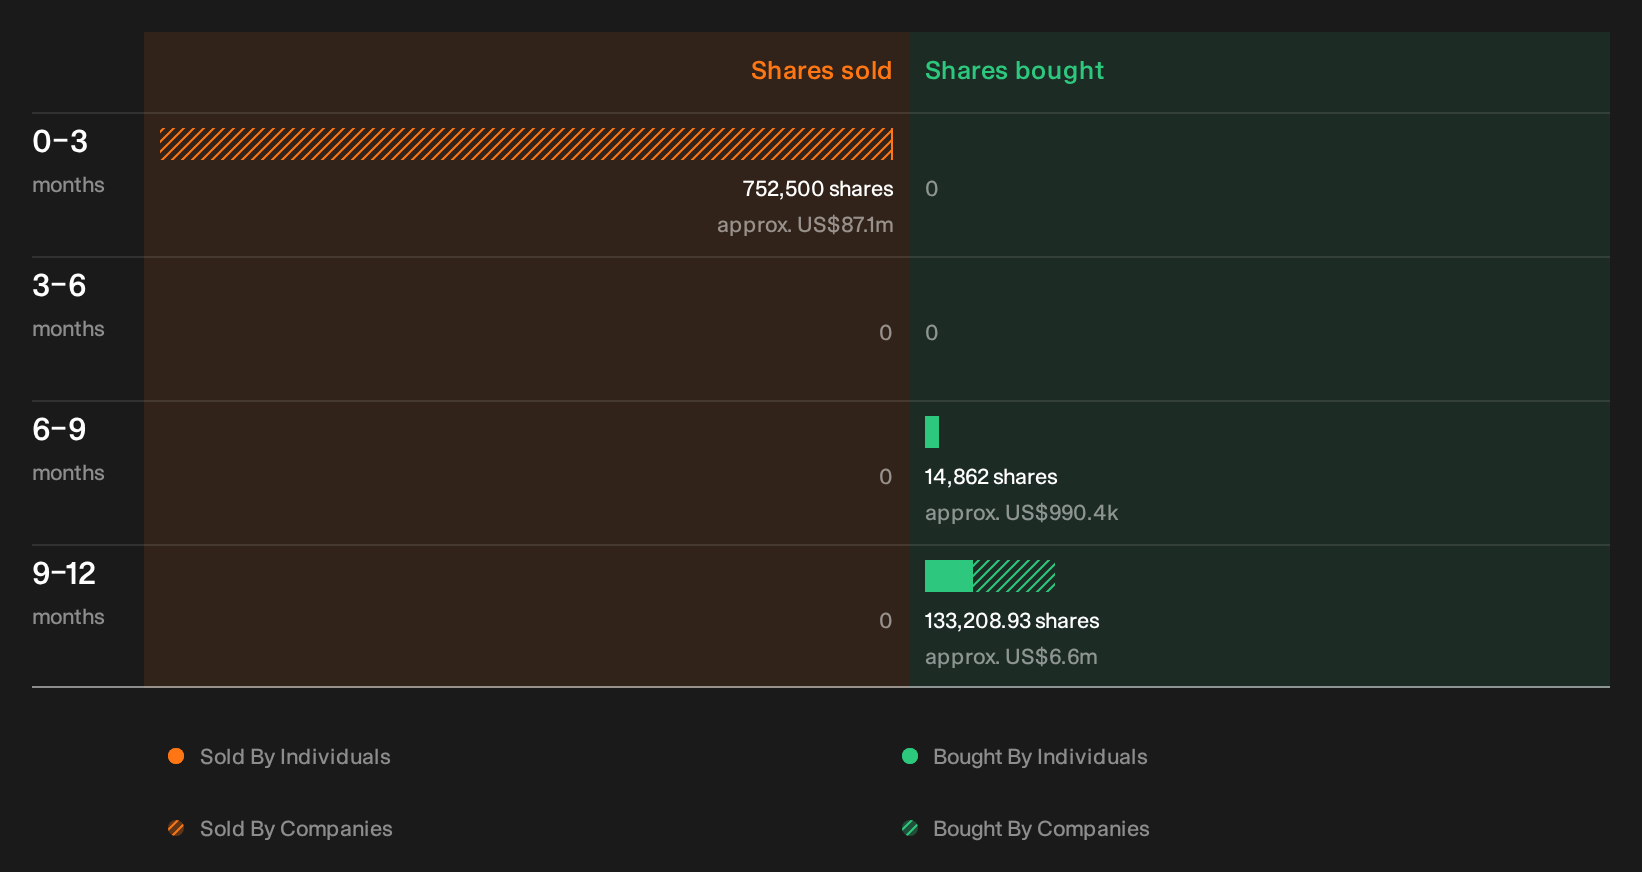
All of the cash flow work still leaves one loose thread. Recent activity from people inside Marriott Vacations Worldwide has been flagged by our checks, and the sellers, amounts and meaning are for you to unpack. See the recent insider selling flagged for Marriott Vacations Worldwide.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com