


Revenue Guidance Reaffirmed Could Matter For MBB Stock (XTRA:MBB)
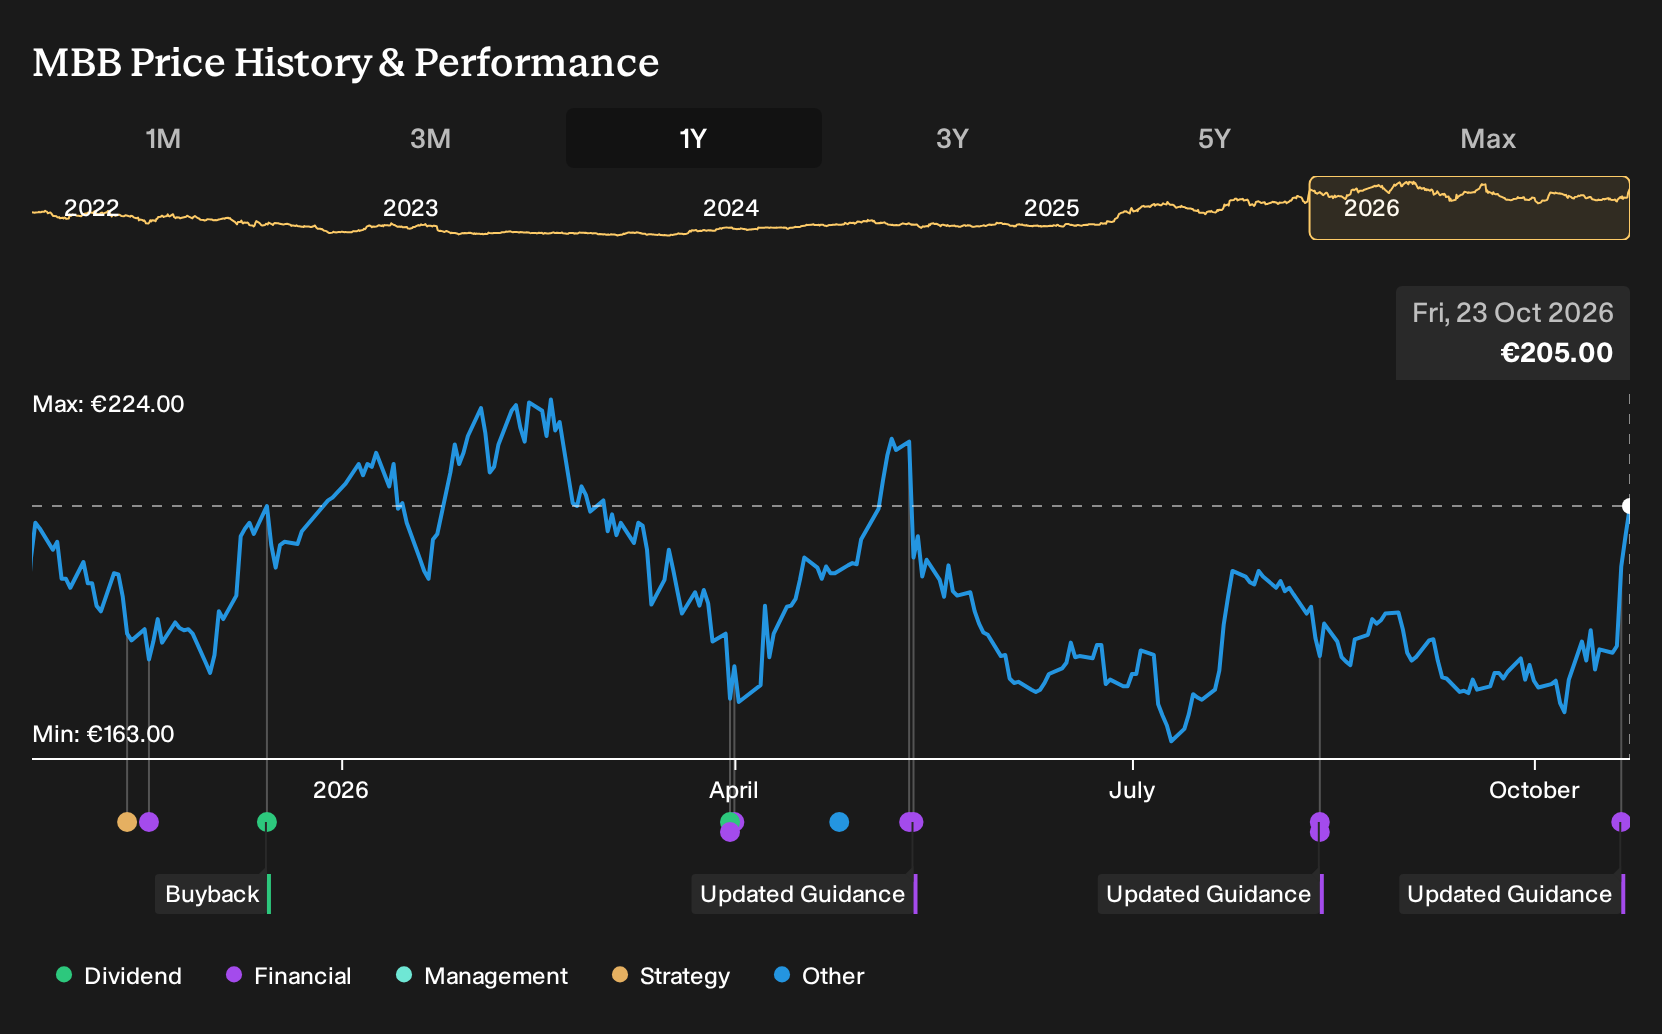
- MBB SE reaffirmed its 2026 revenue guidance in October 2026, keeping the expected range at €1.1b to €1.2b for the year.
- The unchanged outlook signals management’s confidence in current order conversion and portfolio demand, despite varied conditions across its energy, automation and IT security subsidiaries.
- We will now look at how MBB SE’s reaffirmed 2026 revenue corridor could reshape the existing investment narrative investors rely on.
Scan how other contractors and industrial groups are pricing similar order visibility by comparing MBB against our curated list of 194 high quality undervalued stocks.
MBB Investment Narrative Recap
MBB investors need to believe the group can keep turning its large energy, automation and IT security backlogs into stable cash generation while managing the more cyclical automotive exposure at Aumann and Delignit. The reaffirmed 2026 revenue corridor of €1.1b to €1.2b suggests no material change to that core thesis.
The key near term swing factor remains project execution at Friedrich Vorwerk and DTS, where timing of public infrastructure and IT spend can move earnings around. The biggest near term risk still lies in weaker vehicle demand or erratic OEM planning, which could leave the automotive activities offsetting progress in higher margin segments.
Among recent developments, the Q2 2026 update at Friedrich Vorwerk is most relevant to this guidance confirmation. Revenue of almost €200 million in the quarter, a 30.7% EBITDA margin and an order backlog above €1.4b across gas, hydrogen, electricity, LNG, district heating and CO2 work underpins a large part of MBB’s top line corridor.
For catalysts, this backlog gives MBB years of contracted work to convert, which matters if investors are weighing the reaffirmed guidance against execution risk. If you are tracking the story, the mix shift toward energy infrastructure and services, supported by this pipeline, sits opposite the exposure to more unpredictable IT project timing and automotive volumes.
MBB's current analyst narrative projects €1.4b revenue and €69.8 million earnings by 2029. This assumes yearly revenue growth of 4.8% and an earnings increase of about €9.8 million from €60.0 million today.
Uncover why MBB's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame MBB as a cleaner, higher margin story if DTS keeps leaning into services and software. They were already pencilling in €1.5b revenue and €75.6 million earnings by 2029, well above consensus. With guidance now reaffirmed, you can explore how these pre-news views might evolve.
Explore another MBB fair value estimate, including one that suggests as much as 150% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your MBB research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for MBB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MBB's overall financial health at a glance.
Looking For More Investment Ideas Beyond MBB?
Once you have a view on MBB, it often helps to line that thesis up against a few focused stock shortlists so you can compare quality, risk and income profile side by side.
- If you want potential growth with tighter risk controls, scan our 221 resilient stocks with low risk scores that may appeal if capital preservation sits high on your checklist.
- For investors who prefer to anchor on income, review our 226 dividend fortresses that group higher yielding payers with a focus on resilience.
- If you enjoy finding earlier stage opportunities before they are widely followed, check out our 122 elite penny stocks with strong financials that zero in on smaller businesses with room to mature.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com